
Anthropic IPO Scrutiny Puts Qualys Stock In Focus For AI Security Demand
Regulators just put Anthropic’s IPO under a harsh spotlight, and that changes the risk story for anything tied to advanced AI almost overnight. Investor attention is swinging toward the quieter picks and shovels of this theme, from cybersecurity arms dealers to insurers trying to price AI-related liability. If you care about where capital might flow next, this piece walks through 3 stocks exposed to that Anthropic news shock.
The three stocks covered next are only a starter slice of this theme. The full screen surfaced 14 more US-listed cybersecurity or AI-liability insurance players with equally compelling storylines that are not discussed below. To identify and analyze those additional names directly, head into the US-Listed Cybersecurity and AI-Liability Insurance Providers screener.
Qualys (QLYS)
Qualys plugs directly into the Anthropic story because its cloud security and compliance tools help enterprises keep AI-era infrastructure hardened, monitored, and audit ready when regulators and boards start asking pointed questions about cyber resilience.
"Adoption of Qualys' new cloud-native risk operations center and Agentic AI platform positions the company as a leading pre-breach risk management provider, offering unified orchestration, automation, and remediation across both Qualys and non-Qualys data, which can support higher average revenue per customer and earnings growth."
What really moves the needle from here is how one emerging pressure shapes demand for this kind of AI-linked cyber risk tooling.
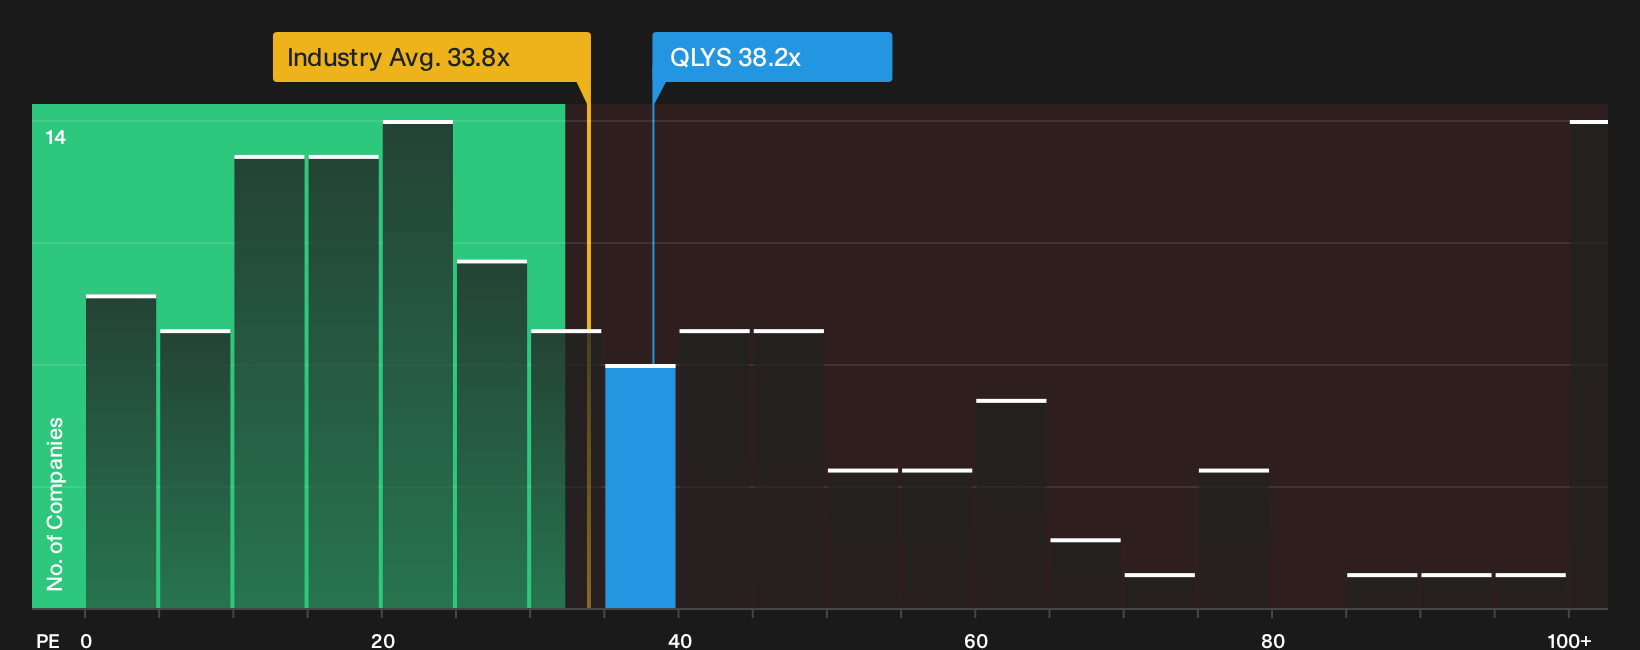
Qualys focuses on subscription-based security software and services, generating about US$703 million from this segment, and serves customers across the United States and overseas, with a market value of roughly US$7.9b.
That pressure point is exactly where Qualys could surprise investors. Read the full narrative for Qualys to see how regulatory momentum and AI risk controls might be decoupling from headline sentiment.
N-able (NABL)
N-able sits squarely in this screener because its tools give managed service providers and smaller enterprises a way to keep AI era endpoints, data, and cloud workloads secure, turning rising regulatory noise into a practical question about who actually runs the day to day cyber defense.
N-able runs a unified security and IT management platform for service providers and smaller enterprises, with about US$533 million from Internet software and services, and a market value near US$969 million.
"Accelerating adoption of cloud technologies and the shift toward unified, integrated platforms continues to support N-able’s end to end cyber resilience offering, with growing contributions from data protection and security operations expected to influence ARR growth and top-line revenue mix."
What really shifts the story from here is how one quiet change in where recurring revenue comes from feeds through to margins and investor patience.
As that revenue mix quietly tilts, read the full narrative for N-able to see how recurring security demand, pricing power, and execution risk intersect for N-able.

Box (BOX)
Box ties directly into this screener because secure cloud content management, with governance wrapped around AI workflows, is becoming infrastructure for enterprises that want AI benefits without losing control of sensitive data.
"Accelerating take up of Box AI units and agentic workflow capabilities, including new guardrails, prompt injection detection and integrations with agents such as Claude, ChatGPT, Gemini and Harvey, can increase usage based monetization and support revenue growth."
What happens to Box’s earnings power if one quiet shift in how customers bundle AI, security, and content workflows breaks in its favor?
Box runs a Software-as-a-Service cloud content platform that secures collaboration and AI-ready workflows. It generates about US$1.23b from internet software and services, with a market value near US$5.8b.
If that shift in how customers package AI and security with content really matters to you, read the full narrative for Box to better understand what could be accelerating beneath Box’s headline numbers.

Seeking Fresh Alternatives Before Crowds?
Some of the sharpest breakout stories start flying under the radar for now, and information advantage fades quickly. Scan fresh ideas before the crowd moves and consider them while they are still relatively undiscovered.
- Target durable cash generators by reviewing a curated list of solid balance sheet and fundamentals (24 results) that helps you focus on businesses where balance sheets can support momentum when sentiment swings.
- Consider upside in early movers by scanning 21 high quality undiscovered gems that spotlight under-followed companies before attention increases and potential entry ranges change.
- Explore structural growth themes by sorting through 55 AI infrastructure stocks that highlight firms supplying the picks and shovels to AI expansion while they are still building momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com