
Diebold Nixdorf (DBD) Stock Drops As Q3 Results Expose Margin Strain
Diebold Nixdorf just dropped its Q3 2026 scorecard and the market did not like it. The stock fell 12.9% on the day to US$58.07. That is a sharp move for a company that reported US$994.3m in quarterly revenue and US$6.6m in net income from ongoing operations.
The reaction tells you more about sentiment than spreadsheets. Traders focused on the earnings wobble and lowered guidance. The underlying story is about a margin squeeze in a hardware heavy, services rich financial technology business, and whether today’s flush properly reflects that pressure or instead pushes past the fundamentals.
If you like the Diebold Nixdorf story but are concerned about margin pressure in a hardware-heavy model, consider reviewing companies with stronger financial cushions by heading to the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$994.3m vs. US$945.2m (up 5.2%)
- Net Income from Ongoing Operations (Q3 2026 vs Q3 2025): US$6.6m vs. US$41.1m (down 83.9%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.20 vs. US$1.13 (down 82.6%)
- Service Gross Margin (Q3 2026): 27.7%, including roughly US$8m one time tax benefit
Prefer clean charts to another wall of earnings commentary and spreadsheets? See a full visual view of Diebold Nixdorf, with its recent earnings and valuation story presented in a simple dashboard via the company report for Diebold Nixdorf.
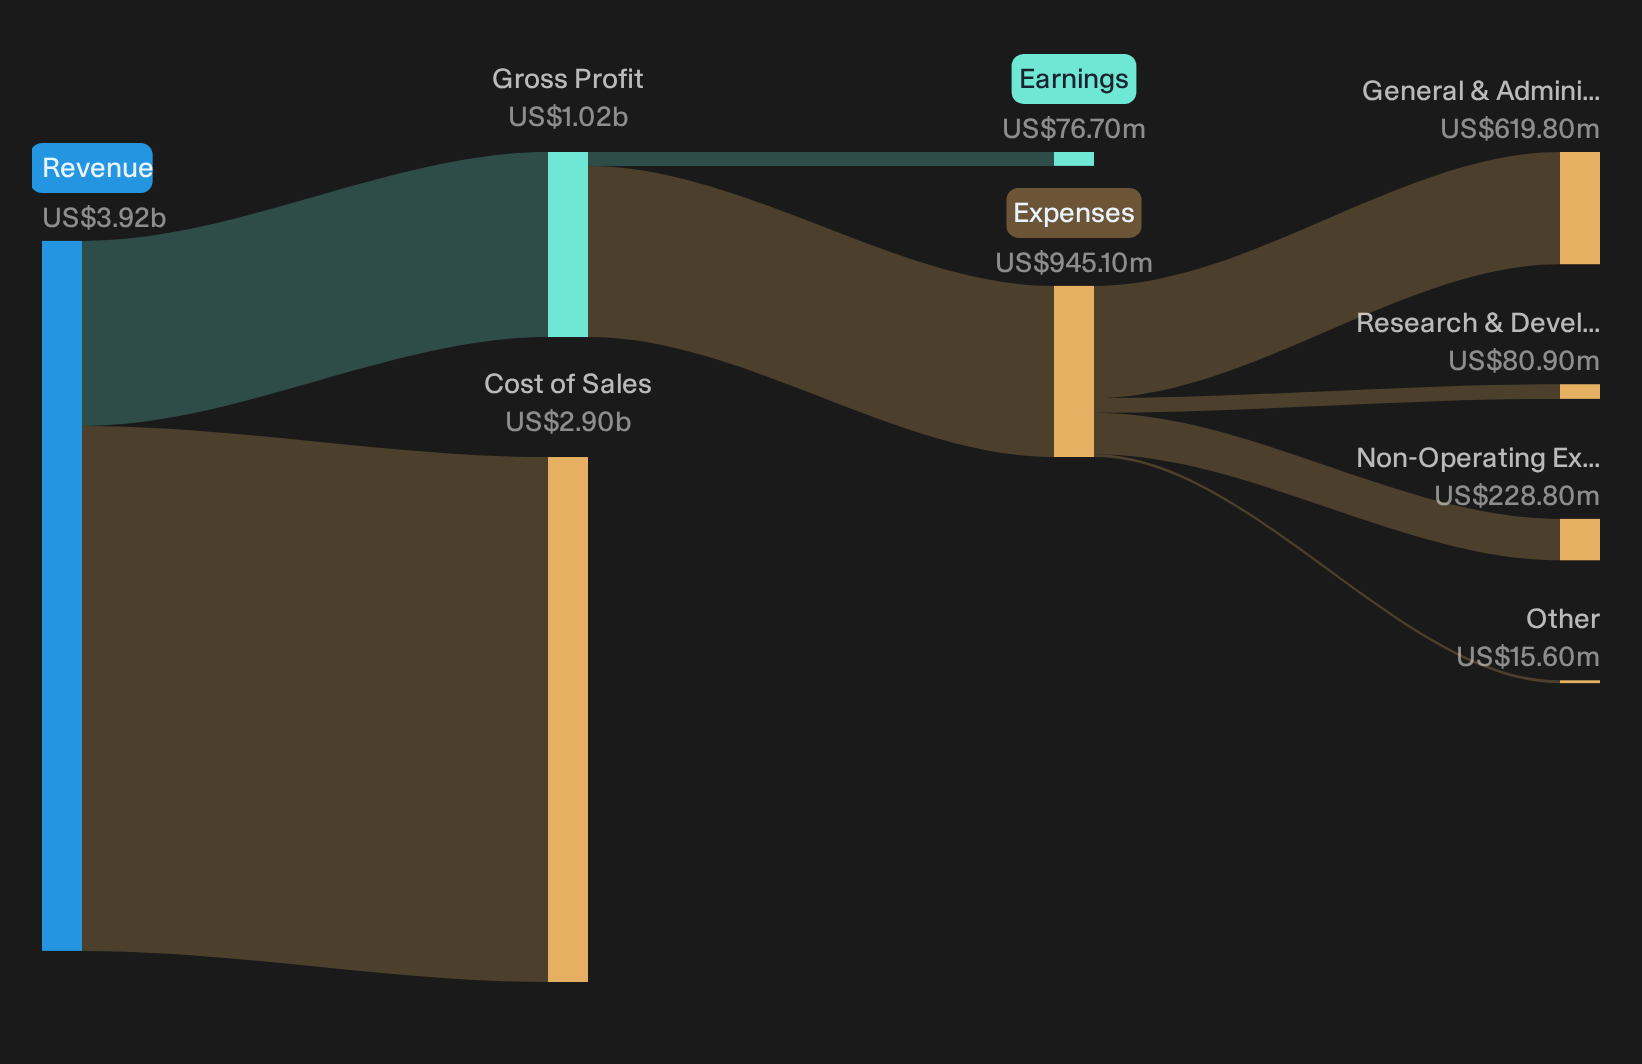
Diebold Nixdorf’s Cash Flow Story Meets Mixed Evidence
"The main thing that has to go right is continued execution on lean manufacturing, AI driven productivity and higher value managed services so that product and service margin targets and free cash flow goals are met despite cost pressures and tax headwinds."
Diebold Nixdorf is clearly pushing in this direction. Service gross margin of 27.7%, helped by fleet renewal and regional consolidation, shows progress on higher value support work. Adjusted EBITDA of US$128m on US$991m of revenue and a full year free cash flow goal of US$190m to US$210m indicate the cash engine is working, even as higher memory costs and delayed banking tenders cap how far the margin story runs right now.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Diebold Nixdorf Bear Case: Margin Gains Prove Fragile
The harsher narrative questions whether Diebold Nixdorf can protect profitability while investing heavily in its service platform.
"Although Diebold Nixdorf highlights lean practices and AI driven internal tools as structural efficiency drivers, the need to invest in a new North American service fleet, additional technicians, and field software has already coincided with lower service gross margins."
Q3 service gross margin of 27.7% includes roughly US$8m of one time tax benefit, and management guides Q4 back to about 26.7%. That step down, alongside lower full year adjusted EBITDA and EPS guidance, shows efficiency gains are not yet outrunning higher memory costs, mix drag and service reinvestment.
Track Where The Earnings Pressure Points Shift
Diebold Nixdorf shows how a single quarter can reshape expectations across a sector. The real opportunity sits in tracking where pressure points move and in stocks that could be undervalued before expectations reset.
- Company 1 - 27% below our estimate - build AI superclusters that serve as expanded cloud backbones when model training exceeds one provider.
- Company 2 - 43% below our estimate - convert a record backlog of data center and modular projects into extended service relationships with owners.
- Company 3 - 16% below our estimate - capture hyperscale data center buildouts through divisions that wire, equip and maintain facilities from construction to operations.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com