
One Stop Systems (OSS) Stock Drops As Q3 Results Expose Margin Strain
The market punished One Stop Systems today. The stock slipped 7.5% to US$6.25 by the close, even as Q3 2026 earnings showed the sharpest improvement in profitability in over a year.
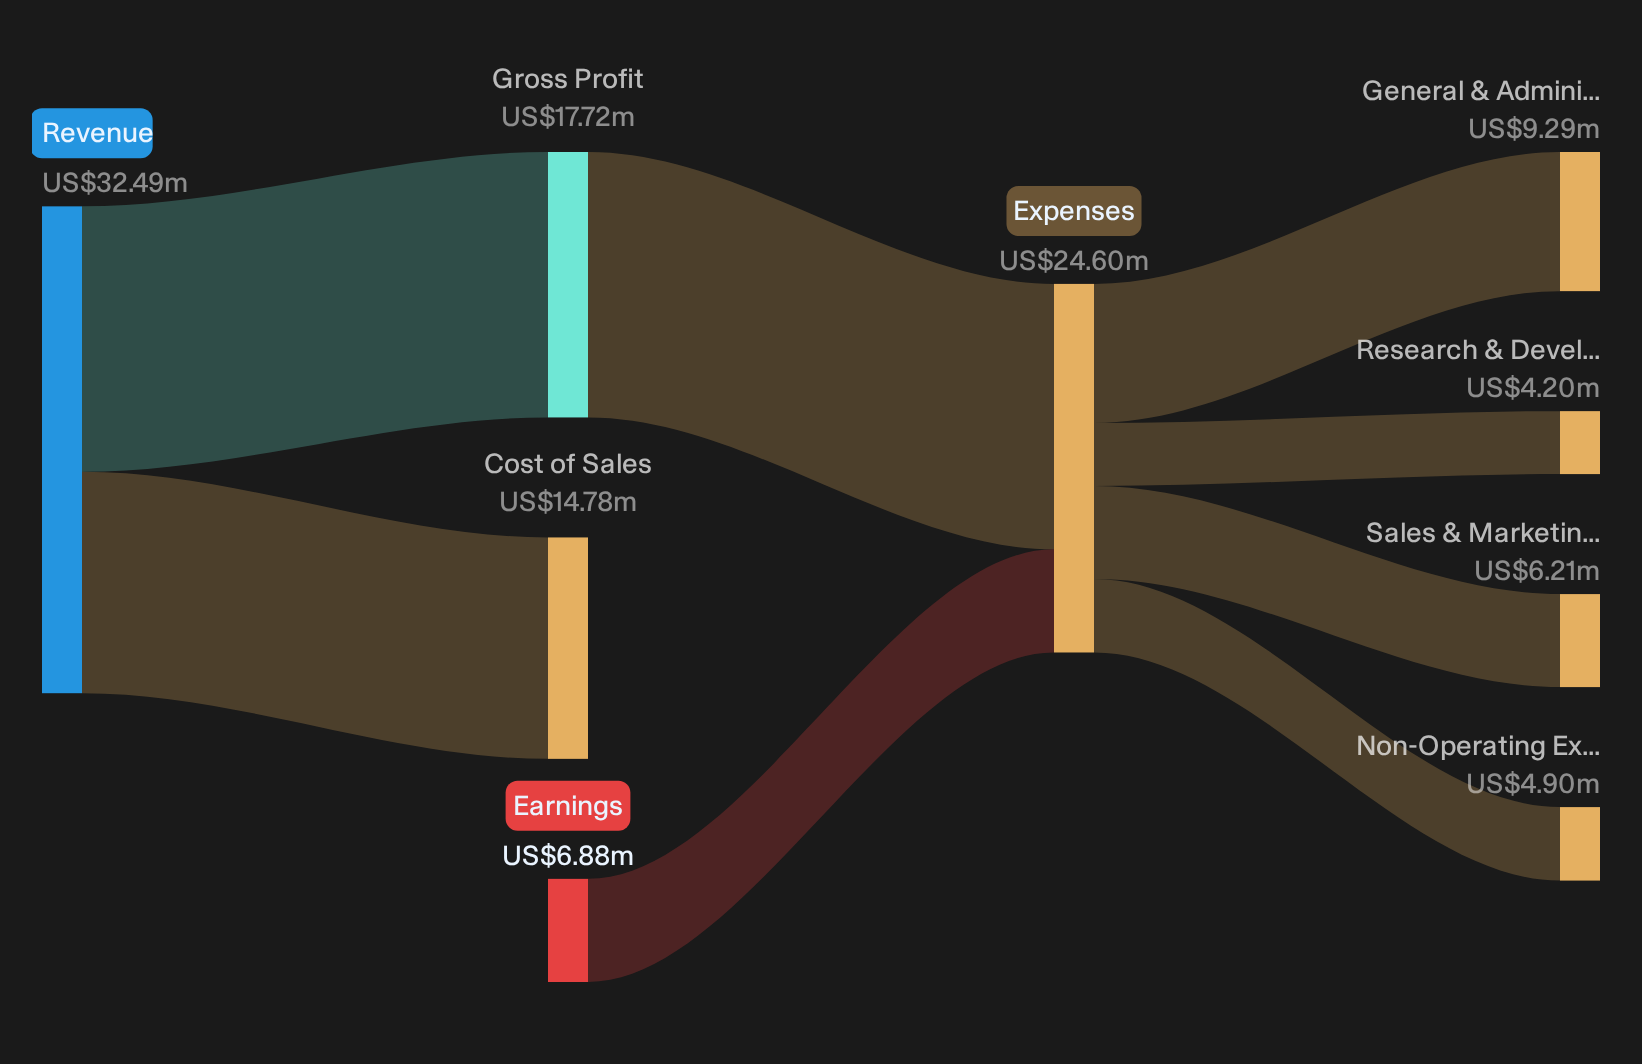
What moved first was emotion, not spreadsheets. Traders reacted to yet another quarterly loss, while the core story was a different kind of pivot. Revenue from continuing operations reached about US$12.6m and the loss per share narrowed to roughly US$0.02, a major shift from the much heavier hit reported in Q2. The price action reflects frustration. The income statement points to a margin squeeze that is starting to ease, not deepen.
Love the sharp improvement in One Stop Systems’ loss per share but concerned the stock is still getting punished for ongoing losses and margin pressure? Compare that setup with companies in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$12.58m vs. US$18.76m (revenue declined year on year)
- Net Income (Q3 2026 vs. Q3 2025): loss of US$0.59m vs. profit of US$0.26m (moved from profit to loss)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.02 per share vs. earnings of US$0.01 per share (shifted from earnings to loss)
- Gross Margin (Q3 2026 vs. Q3 2025): 42.6% vs. 45.6% (margin compressed year on year)
Management flagged several potential $100M-plus programs not in guidance. Ask Charlie what makes One Stop Systems’ $100M programs realistic.
OSS Bull Case: Programs Are Starting To Do The Heavy Lifting
The upbeat story on One Stop Systems centers on long-lived programs and sole-source status turning into steadier, higher quality revenue.
"Multi-year defense and commercial platform wins and sole-source supplier agreements provide strong revenue visibility and support higher margins, as OSS becomes the incumbent compute and storage supplier for next-generation AI-driven and autonomous edge platforms."
Q3 data lines up with that vision. Revenue from continuing operations reached about US$12.6m with year to date bookings of more than US$43.6m and a book to bill of 1.46. Management now tracks 14 multiyear programs versus 1 three years ago. Gross margin of 42.6% sits inside the 40% to 42% full year target range, which supports the idea that program scale is offsetting near term mix pressure.
OSS Bear Case: Contract Volatility Still Bites Into Predictability
Bears focus on whether reliance on chunky contracts and complex hardware keeps earnings choppy even as bookings look strong.
"Heavy reliance on large, lumpy government and defense contracts means OSS is exposed to delays and unpredictability from budget cycles, continuing resolutions, and shifting government funding timelines; such volatility could negatively impact revenue stability and growth visibility."
Q3 results give that concern some backing. Revenue of US$12.58m fell year on year and OSS swung from a Q3 2025 profit to a loss of US$0.59m, despite higher full year revenue guidance of about US$45m. The bad debt provision tied to a bankrupt customer and a US$6.25m legal settlement have already hit cash. Inventory has climbed by US$7.8m to stay ahead of long lead times in GPUs and memory, which helps delivery but ties up capital if orders slide.
The price and this Narrative do not agree. → Uncover what this Narrative says One Stop Systems is actually worth.
Hunt Mispriced Earnings Setups
One Stop Systems highlights how fast sentiment can change after earnings. The real opportunity is hunting stocks that could be undervalued before sentiment adjusts.
- Company 1 - 23% below our estimate - turns broad workplace software and cloud services into an integrated AI layer across workflows.
- Company 2 - 28% below our estimate - wins complex manufacturing programs in regulated sectors as customers consolidate more design and production with one partner.
- Company 3 - 27% below our estimate - builds large AI compute clusters that major model developers use to add capacity beside existing cloud providers.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com