
Hinge Health (HNGE) Stock Looks Above Fair Value After Its 150% Run
Hinge Health has delivered a sharp rerating this year, which puts fresh attention on whether the current share price lines up with what the business is earning. After such a strong run, the real issue for you is how much of the optimism is already captured in the earnings multiple.
- With the stock up 150.0% year to date, any further move now leans heavily on whether its earnings can justify the valuation that price implies.
- The company’s model of treating musculoskeletal conditions through digital programs can influence long term profitability, because the economics depend on how efficiently it converts patient engagement into recurring earnings.
- The analysts covering Hinge Health have run their own numbers. See what analysts think Hinge Health's shares could be worth.
The stock’s next move may depend on whether Hinge Health’s current price is supported by the earnings power investors can reasonably tie to the business today.
If you want a broader starting point to compare Hinge Health with other opportunities tied to clear screening rules, apply the same analysis across 29 high quality undervalued stocks.
Is Hinge Health Getting Expensive on Earnings?
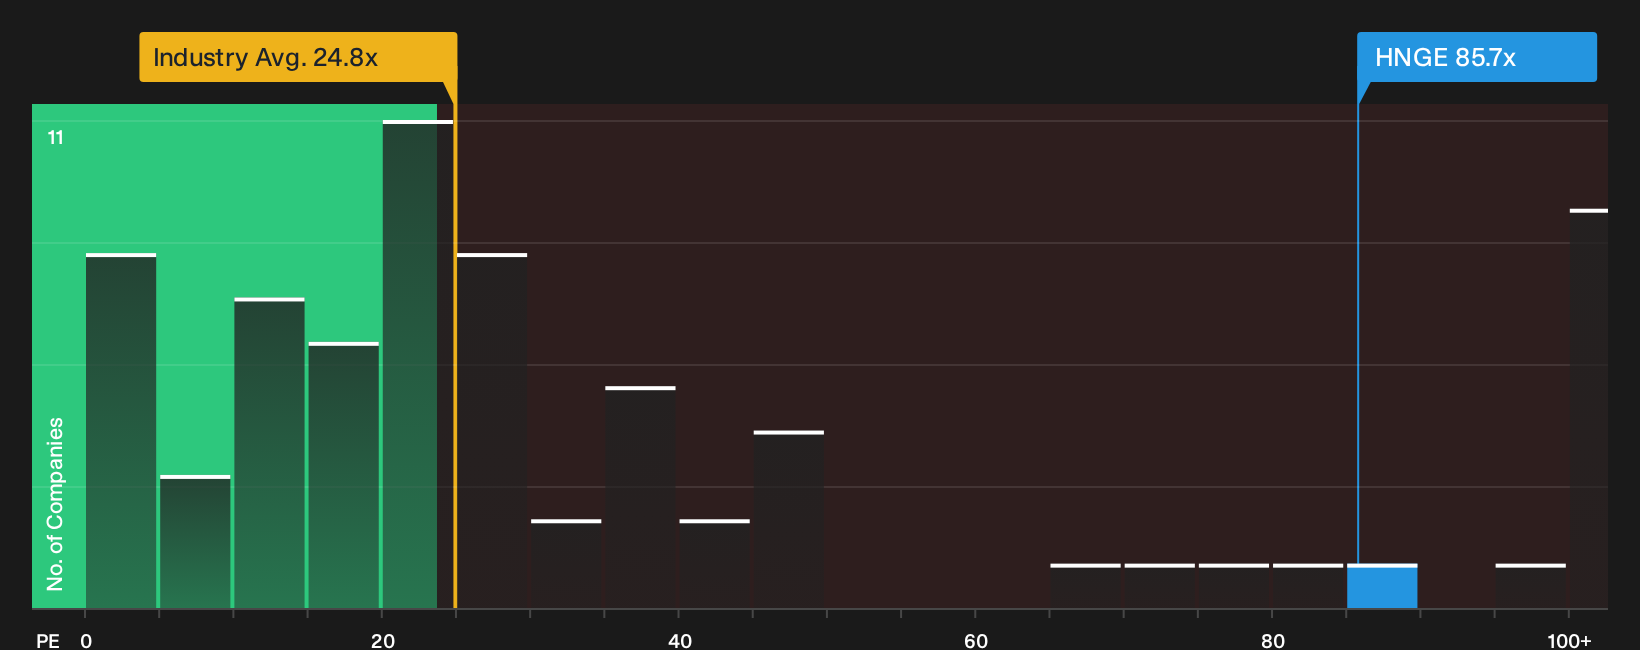
The P/E ratio fits Hinge Health because investors often anchor digital health valuations to the earnings they can see per share today. On that yardstick, the stock trades on a P/E of 85.7x, compared with about 24.8x for the wider Healthcare sector, which points to a steep premium over the broader group of listed peers.
A more tailored yardstick that blends factors like Hinge Health’s growth profile, profitability, scale and risk points to a lower multiple as a rough anchor. The current 85.7x sits above that range as well as above the peer average of 62.3x. For you as a shareholder or potential buyer, the key question is whether the earnings path you consider realistic is strong enough to support paying materially more per dollar of profit than both the sector and closer comparables. Explore the numbers behind Hinge Health's P/E valuation.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hinge Health pick up where the P/E puzzle leaves off by spelling out which paths for Hinge Health's growth, profitability and earnings would need to play out for the current share price to look meaningfully higher or lower in hindsight, and by turning a single valuation output into a set of concrete future conditions you can watch on the Community page over time.
Community views on Hinge Health are now split between a strong upside case and a more cautious read on how much is already priced in.
Bull case: 21% undervalued
"Hinge Health has quickly distinguished itself as one of the most successful IPOs of 2025, combining rapid revenue growth, widening margins, and a scalable AI driven care model…"
Discover why this Narrative puts Hinge Health at 21% undervalued.
Bear case: 27% overvalued
"Although the company is expanding its reach to roughly 25 million contracted lives and 783,000 members, future revenue growth still depends on converting a large pool of eligible lives in a market where employer benefit budgets and plan designs can limit further adoption…"
Explore why this Narrative puts Hinge Health at 27% overvalued.
One more Hinge Health factor to check before you act
There is still a crucial piece of the Hinge Health puzzle that sits outside the earnings multiple: who is steering the company and how their incentives line up with your outcomes as a shareholder. See who runs Hinge Health and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com