
HA Sustainable Infrastructure Capital (HASI) Could Be 21% Below Fair Value After $34 Million Terradot Loan
HA Sustainable Infrastructure Capital (HASI) drew fresh attention after arranging a $34 million senior secured term loan for Terradot’s enhanced rock weathering projects in the US and Brazil, backed by fixed-price, multi-year offtake agreements.
That Terradot financing dropped into a backdrop where HA Sustainable Infrastructure Capital’s share price has already gained 16.8% year to date to US$37.17, with short-term momentum picking up, including a 2.82% 1-day share price return and 4.21% 7-day share price return.
Over a longer stretch, investors have seen a 34.45% 1-year total shareholder return and a very large 3-year total shareholder return of about 2.5x, even though the 5-year total shareholder return is down 21.8%. This hints that sentiment has improved more recently than it did earlier in that period.
Scan other climate-focused financiers showing similar momentum by running a curated screen of 16 nuclear energy infrastructure stocks alongside HA Sustainable Infrastructure Capital’s latest Terradot-backed move.
HA Sustainable Infrastructure Capital now trades at a discount to both analyst targets and intrinsic estimates, even after the Terradot loan headlines. Is that a margin of safety, or a warning that the market’s caution is justified?
Price-to-Earnings of 56.7x: Is it justified?
On simple valuation math, HA Sustainable Infrastructure Capital trades on a rich P/E of 56.7x, alongside a $37.17 share price that screens as expensive relative to both its own fair P/E estimate and peer benchmarks.
The P/E ratio compares what investors pay today for each dollar of current earnings. A higher figure often reflects strong confidence in future profit growth or a willingness to accept thinner returns on today’s earnings. For a specialist financier focused on energy efficiency, solar, wind and other sustainable projects, this indicates that the market is paying a premium for exposure to its climate solution portfolio rather than treating it like a typical diversified financial stock.
That premium shows up clearly in the numbers. The current 56.7x P/E is described as expensive compared with the US Diversified Financial industry average of 17.2x. It also appears stretched against a fair P/E estimate of 14.8x that the data suggests the market could move toward instead. Those gaps indicate investors are paying several times more per dollar of earnings than both peers and the fair ratio framework imply.
Explore the SWS fair ratio for HA Sustainable Infrastructure Capital.
Result: Price-to-Earnings of 56.7x (OVERVALUED)
Still, HA Sustainable Infrastructure Capital’s high 56.7x P/E and concentration in US sustainable assets provide limited cushion if sentiment on climate financing or policy support cools.
Find out about the key risks to this HA Sustainable Infrastructure Capital narrative.
Another View: What The SWS DCF Model Says About HA Sustainable Infrastructure Capital
Where the rich 56.7x P/E for HA Sustainable Infrastructure Capital points to an expensive stock, the SWS DCF model suggests the opposite. On that cash flow lens, HASI trades at about a 21.4% discount to an estimated fair value of roughly $47.30 per share.
That gap means the same cash flows that look pricey through earnings multiples appear cheaper when spread out over time using discounted cash flow maths. The question for investors is which lens better fits a specialist lender with long dated sustainable infrastructure assets.
Look into how the SWS DCF model arrives at its fair value.
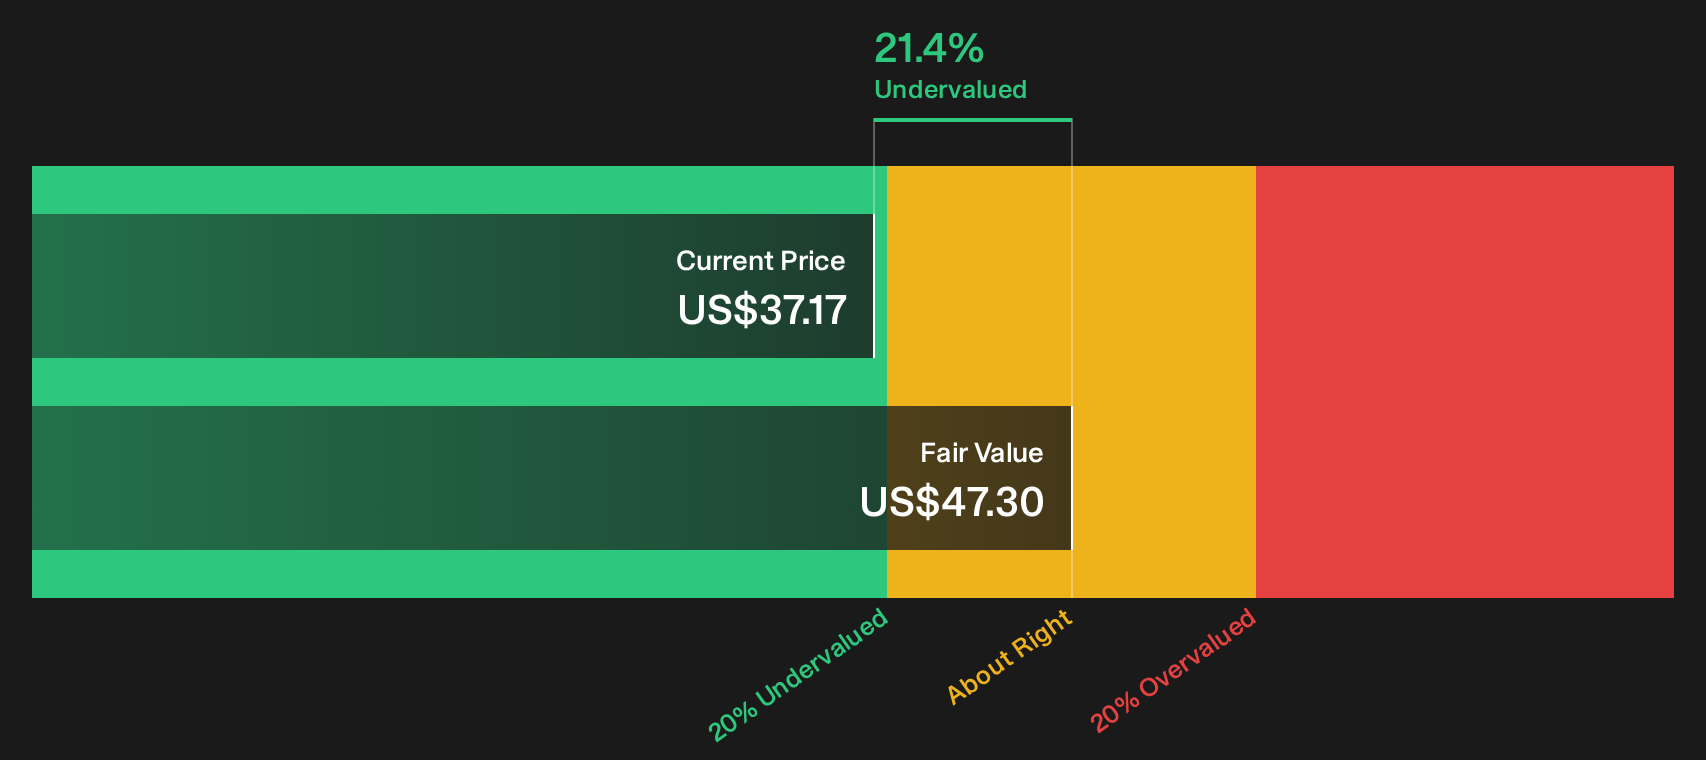
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out HA Sustainable Infrastructure Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on HA Sustainable Infrastructure Capital so far. If you want to move faster than the crowd, weigh the upside and downside for yourself with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond HA Sustainable Infrastructure Capital?
If you like what you see with HA Sustainable Infrastructure Capital but do not want to stop at one ticker, consider broadening your watchlist with a few focused stock shortlists that highlight different strengths across the market.
- Target potential mispricing and look for quality opportunities that may trade below their estimated worth by scanning the 29 high quality undervalued stocks.
- Explore ways to build a steadier income stream and compare companies that offer higher yields with staying power by reviewing the 5 dividend fortresses.
- Aim to reduce blowup risk and emphasise durability in your portfolio by filtering for companies in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com