
Penguin Solutions (PENG) Stock Trades Below Fair Value After A 331% Run
Penguin Solutions has ridden a powerful AI infrastructure story into the spotlight, and the question now is whether a share price of US$58.99 is adequately backed by its earnings. With the stock already pricing in a lot of optimism, the key issue for you is how much of the AI buildout is already reflected in the earnings multiple.
- Over the past 3 years, Penguin Solutions has delivered a 330.6% share price return, which puts real pressure on the earnings base to justify how far the valuation has moved.
- Fresh AI infrastructure contracts and a record period for sales suggest expectations for future profit streams may be pulling forward a lot of value into today's price, which directly affects how the current earnings multiple is interpreted.
- The analysts covering Penguin Solutions have run their own numbers. See what analysts think Penguin Solutions's shares could be worth.
The issue now is whether Penguin Solutions' current market value is appropriately supported by the earnings it generates today.
If you want more ideas tied to this AI infrastructure theme, a focused stock screen is a clear next step. You can start with 55 AI infrastructure stocks.
Does Penguin Solutions Look Undervalued on Earnings?
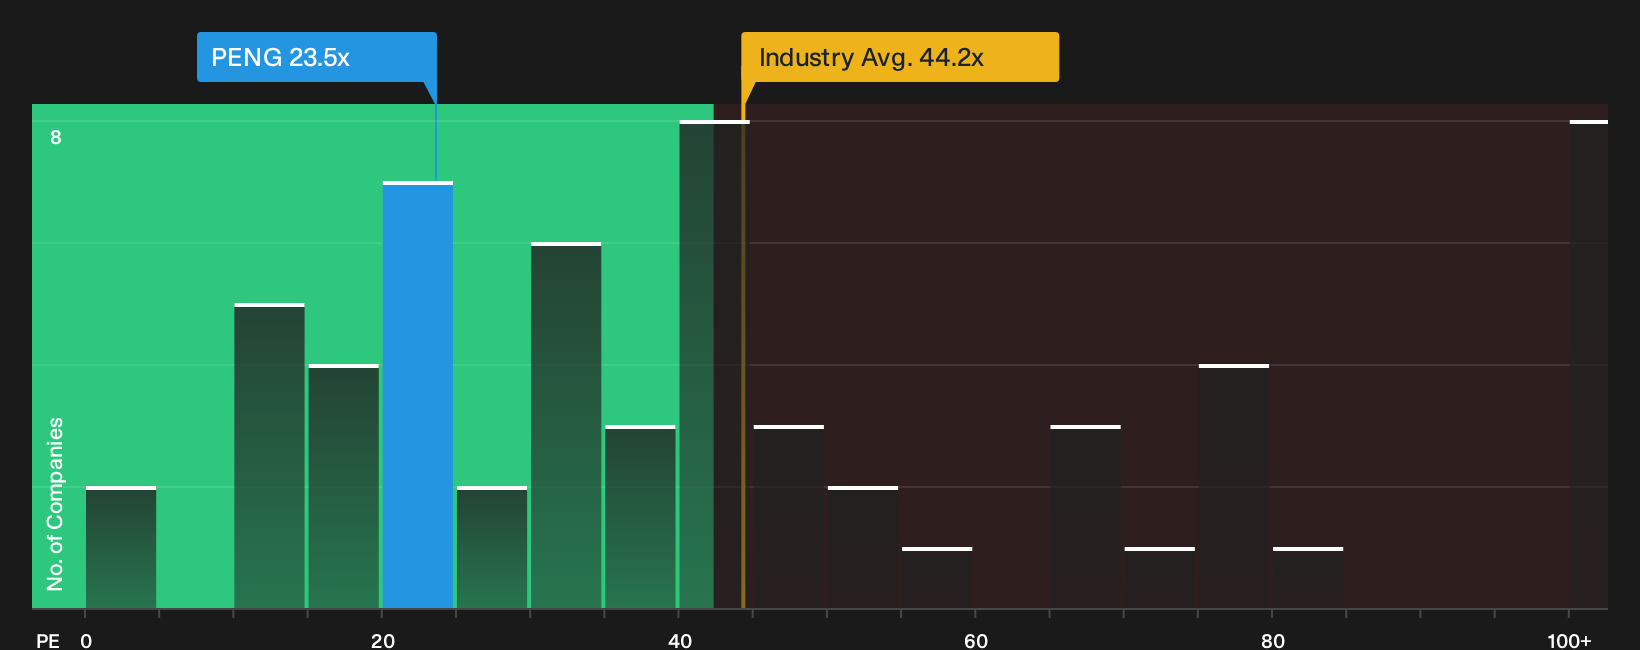
P/E works well for Penguin Solutions because earnings are already positive and investors can see how much they are paying for each dollar of profit. At a P/E of 23.5x, the stock trades at roughly half the Semiconductor industry average of 44.2x and also at a discount to peers around 48.0x, which points to a lower earnings multiple than many AI infrastructure related chip businesses.
Record Q4 2026 sales and the multi year Axe Compute partnership have pulled Penguin Solutions more firmly into the AI infrastructure conversation. However, the current P/E still sits below the level a tailored fair multiple model would imply for a business with its profile. Because the present ratio is beneath that custom benchmark, the valuation signal on P/E screens as undervalued relative to what that framework suggests you might normally pay for this kind of earnings stream. Explore the numbers behind Penguin Solutions's P/E valuation.
The Penguin Solutions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Penguin Solutions pick up exactly where the valuation puzzle leaves off by spelling out which assumptions on future growth, profitability and earnings must hold for the shares to be worth materially more or less than today’s price, and they sit on the stock’s Community page. Each narrative treats Penguin Solutions' fair value as a thesis about how the business might evolve that you can track over time rather than a one off snapshot.
One of the top community narratives on Penguin Solutions: 29% undervalued
"Strong growth is supported by increasing AI-driven demand, expanding services, and key partnerships that enhance product innovation and earnings stability..."
Discover why this Narrative puts Penguin Solutions at 29% undervalued.
One more angle on Penguin Solutions that could change how you see the whole story
Price and current earnings tell only part of the story for Penguin Solutions, because professional forecasts sketch out where some expect this business to be a few years from now. Explore where analysts expect Penguin Solutions to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com