
Can Walmart (WMT) Keep Justifying Its Earnings Premium?
Walmart has ridden a powerful multi year share price run, and with the stock recently closing at US$119.32 the live question for investors is whether that level can be squared with what its earnings support.
- Over the past 5 years, Walmart has delivered a share price return of 154.5%, which puts extra weight on whether current profits justify the move.
- Recent expansion into areas such as AI driven e commerce tools, healthcare services and membership bundles may support expectations for higher margin earnings and more recurring cash generation over time.
- Your read on Walmart is one view; the desks covering it have another. See what analysts think Walmart's shares could be worth.
The stock's next move may depend on whether Walmart's current earnings profile is strong enough to make today's valuation look sensible.
If you want a broader watchlist of companies where earnings are a key part of the story, a focused stock screen like 29 high quality undervalued stocks can be a useful next stop in your research.
Is Walmart Getting Expensive on Earnings?
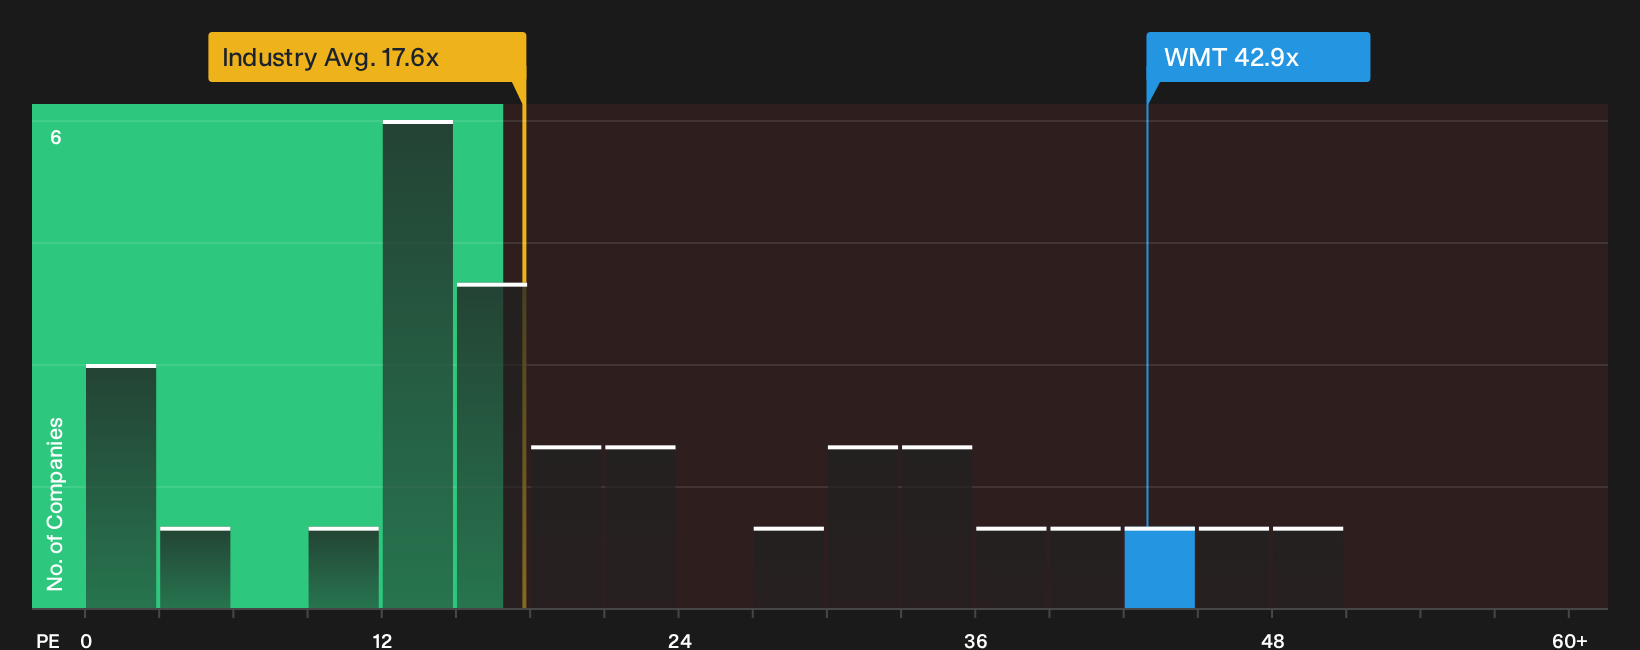
The P/E ratio fits Walmart well because investors usually judge mature retailers most cleanly on what they earn per share. At roughly 42.9x earnings, the stock trades at a sizeable premium to both the Consumer Retailing industry average near 17.6x and a peer group around 23.4x, so buyers today are clearly paying up for its profit stream.
On Simply Wall St's fair multiple framework, which blends Walmart's growth profile, margins, size and risk into a tailored benchmark, the current P/E sits above where that model would usually place the shares, so the stock screens overvalued on this lens. Despite interest in Walmart's push into AI shopping agents and higher margin services, the present multiple already reflects a rich set of expectations that you would need to weigh carefully against the retailer's earnings record and your own return hurdles before committing fresh capital. Explore the numbers behind Walmart's P/E valuation.
The Walmart Narrative: What Would Justify Today's Price?
Walmart's high P/E raises a simple question for you as an investor: which future path would need to play out on growth, profitability and earnings for this stock to look clearly cheap or clearly expensive relative to today?
Simply Wall St Narratives on the Community page turn that puzzle into a set of concrete storylines about Walmart's business. Each storyline sets out a fair value as a thesis that you can track over time, rather than a one off snapshot.
One of the top community narratives on Walmart: 6% undervalued
"The main factor that has to go right is the continued growth and profitability of higher margin alternative profit pools such as advertising…"
Discover why this Narrative puts Walmart at 6% undervalued.
One more piece of the Walmart puzzle still sits off to the side
Valuation only captures what the market is willing to pay today, while analyst models sketch out where they think Walmart could be a few years from now and give you another benchmark to compare with the current multiple. Explore where analysts expect Walmart to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com