
The Bet BT Group Holders Made
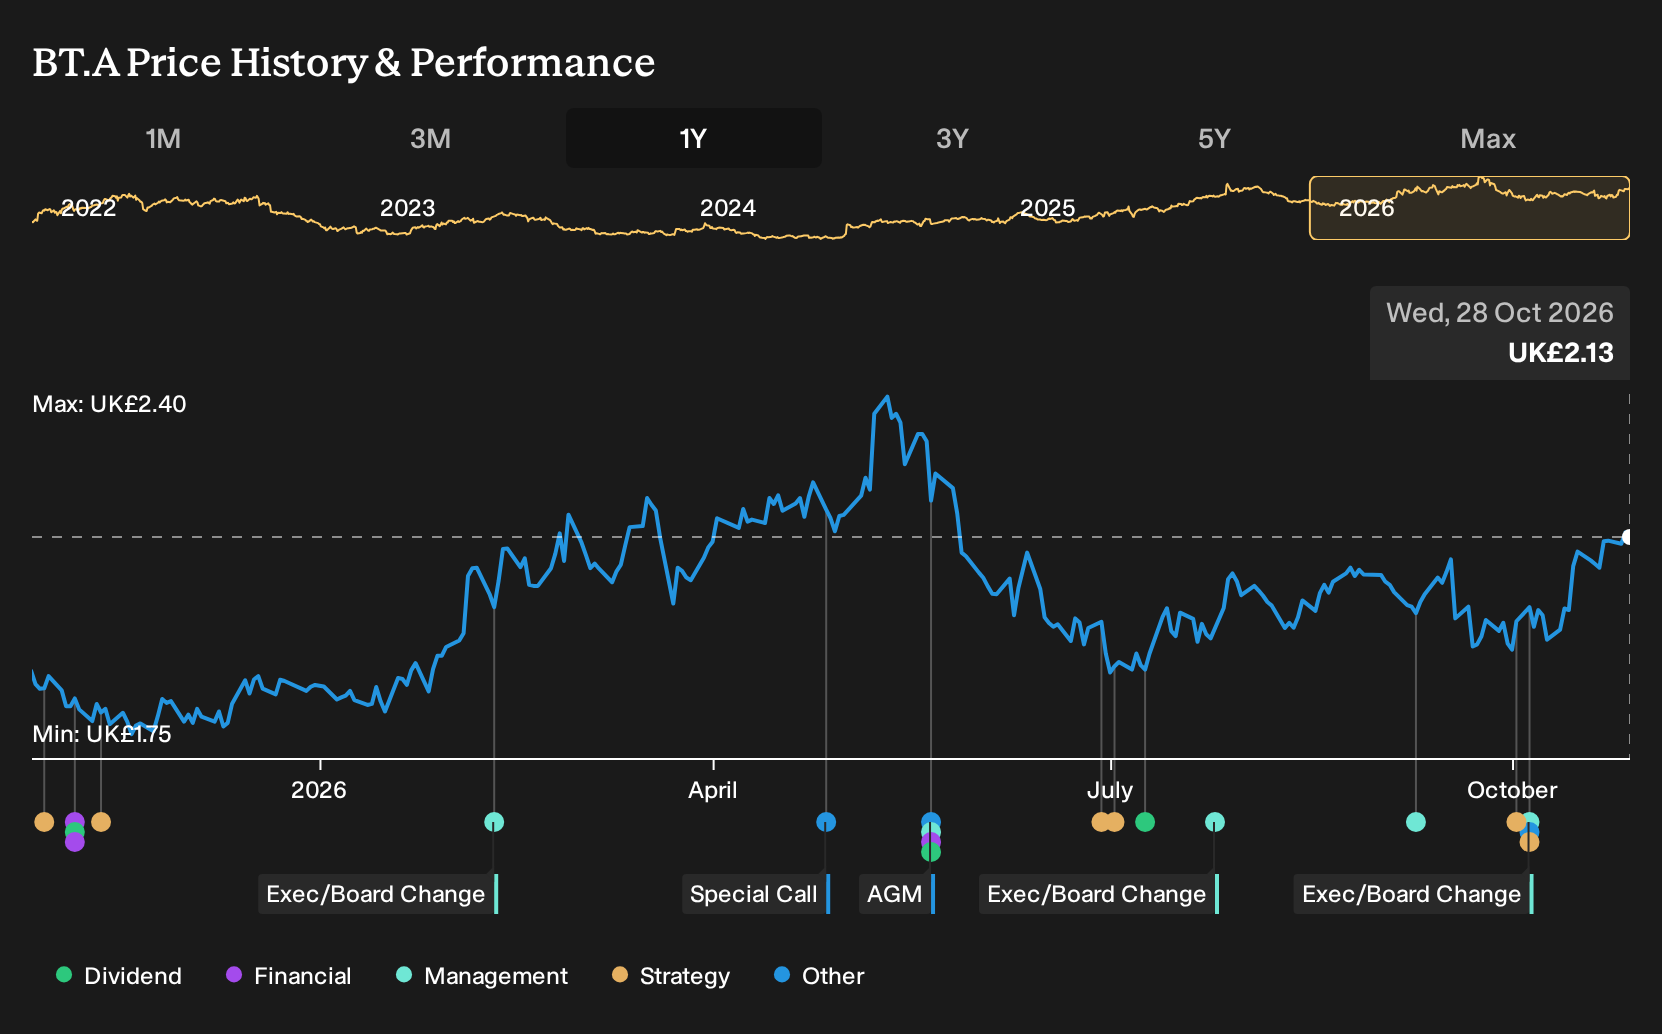
At first glance BT Group looked like a plodder, caught between bullish hopes for fibre and 5G, and a bearish case built on fixed line decline and heavy obligations. Holding BT Group over the past year would have returned 21.0%, including dividends. If you had committed fresh capital back on 28 October 2025, what exactly in the record then could have justified taking that risk?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
BT Group is not the only name tied to this theme. Zero in on 55 AI infrastructure stocks and compare how each one is priced.
The Two Stories BT Group Investors Had To Weigh
The shares cost £1.84 at the start of the period, and BT Group sat between two clear stories about what might happen next.
The bullish narrative pinned Fair Value at £2.10, which was 14% above the start price. This view assumed revenue would decline 0.9% a year, but profit margin would reach 8.5%, with a future P/E of 15.5x over three years.
The bearish view put Fair Value at £1.30, which was 29% below the start price, and focused on fixed-line decline and Openreach broadband line losses as key risks to future earnings flexibility.
What The Results Changed For The BT Group Debate
The clearest new fact was the reported H2 2026 result. Revenue moved from £10,241m in H2 2025 to £9,844m in H2 2026, yet net income rose from £299m to £426m and net margin improved from 2.9% to 4.3%. That pattern supported the bullish focus on margin progress, while the weaker top line kept the cautious view alive. Overall, the evidence cut both ways.
The key lesson is simple. When a story leans on margin repair, as BT Group did, it is logical to track net margin and absolute profit against that script and to treat any revenue slippage as a separate risk to test at each set of results.
What BT Group’s Price Now Asks You To Believe
Today BT Group trades at £2.12. The selected Narrative’s Fair Value sits below that level, framing the current quote as already baking in a stronger outcome than its own central case.
The Narrative circles one question: Do you think BT Group can turn heavy fibre spend and cost cutting into durable free cash flow, given ongoing fixed line erosion and International weakness?
"The main factor that needs to work in BT Group’s favor is successful delivery of its extended cost transformation and network migration program, so that large planned cost savings and efficiency gains translate into resilient earnings and cash generation."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
BT Group And A Parallel Bet
BT Group draws attention to fibre buildouts, wireless coverage and cost repair. That frame captures only one angle on the same problem.
Telecom customers still want faster broadband, steadier mobile service and simpler plans. That hunger for reliable connectivity does not stop at the UK border.
Another operator leans on a similar mix of fibre, 5G capacity and private networks. Its focus is keeping users loyal while holding acquisition costs down.
Cost programs, network upgrades and AI enabled operations shape how that business turns heavy investment into cash. If those levers deliver, its place in everyday connectivity could shift again.
That argument has a Narrative and a number behind it. → See the company one Narrative values 17% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com