
AI Infrastructure Demand Might Change The Case For Investing In Semtech Stock
- Semtech expanded its AirLink 5G networking lineup for public safety fleets, adding network slicing, FirstNet Trusted certifications, and software based FIPS 140-3 compliance, while extending cloud and on premises management across its router portfolio.
- The ability to meet updated federal encryption standards through an AirLink OS 6.1 software upgrade, without replacing hardware, directly affects lifecycle costs and deployment risk for Semtech’s public safety customers.
- The focus now turns to how Semtech’s AI data center demand and new FIPS 140-3 ready 5G routers may influence its broader investment narrative.
Semtech Investment Narrative Recap
To own Semtech, you need to buy into a very specific story. The key belief is that AI data center demand, high speed connectivity and IoT systems can support strong revenue growth and higher quality earnings, while the firm manages product mix so margins do not get dragged down by lower margin segments. The big near term swing factor remains execution on AI related connectivity; design wins and delivery against backlog carry outsized importance.
The largest risk is still margin pressure and integration headaches around connected services and IoT, especially after the goodwill impairment and the mix driven gross margin comments. The new AirLink 5G public safety update looks helpful for customer retention and lifecycle economics, but on its own it does not materially change the short term earnings catalyst or the main risk profile.
The most relevant announcement here is the AirLink OS 6.1 upgrade that lets existing 5G routers meet FIPS 140-3 standards via software. For public safety fleets, this matters in a very operational way. Agencies can stay aligned with updated federal encryption rules without ripping out installed hardware, which reduces disruption risk and supports stickier deployments.
For Semtech, this kind of upgradeable security posture can support the broader AI and data infrastructure thesis in a quiet but practical way. Better lifecycle economics and compliance management in routers may help defend pricing and reduce churn in IoT and connectivity, which are areas where mix has already pressured margins. The operational test now is simple: convert these security and management features into stable, recurring router and services revenue while keeping R&D spend productive.
Semtech's current analyst storyline points to US$2.9b in revenue and US$870.8m in earnings by 2029. That profile assumes revenue growing at about 34.8% a year and earnings rising by roughly US$716.8m from US$154.0m today.
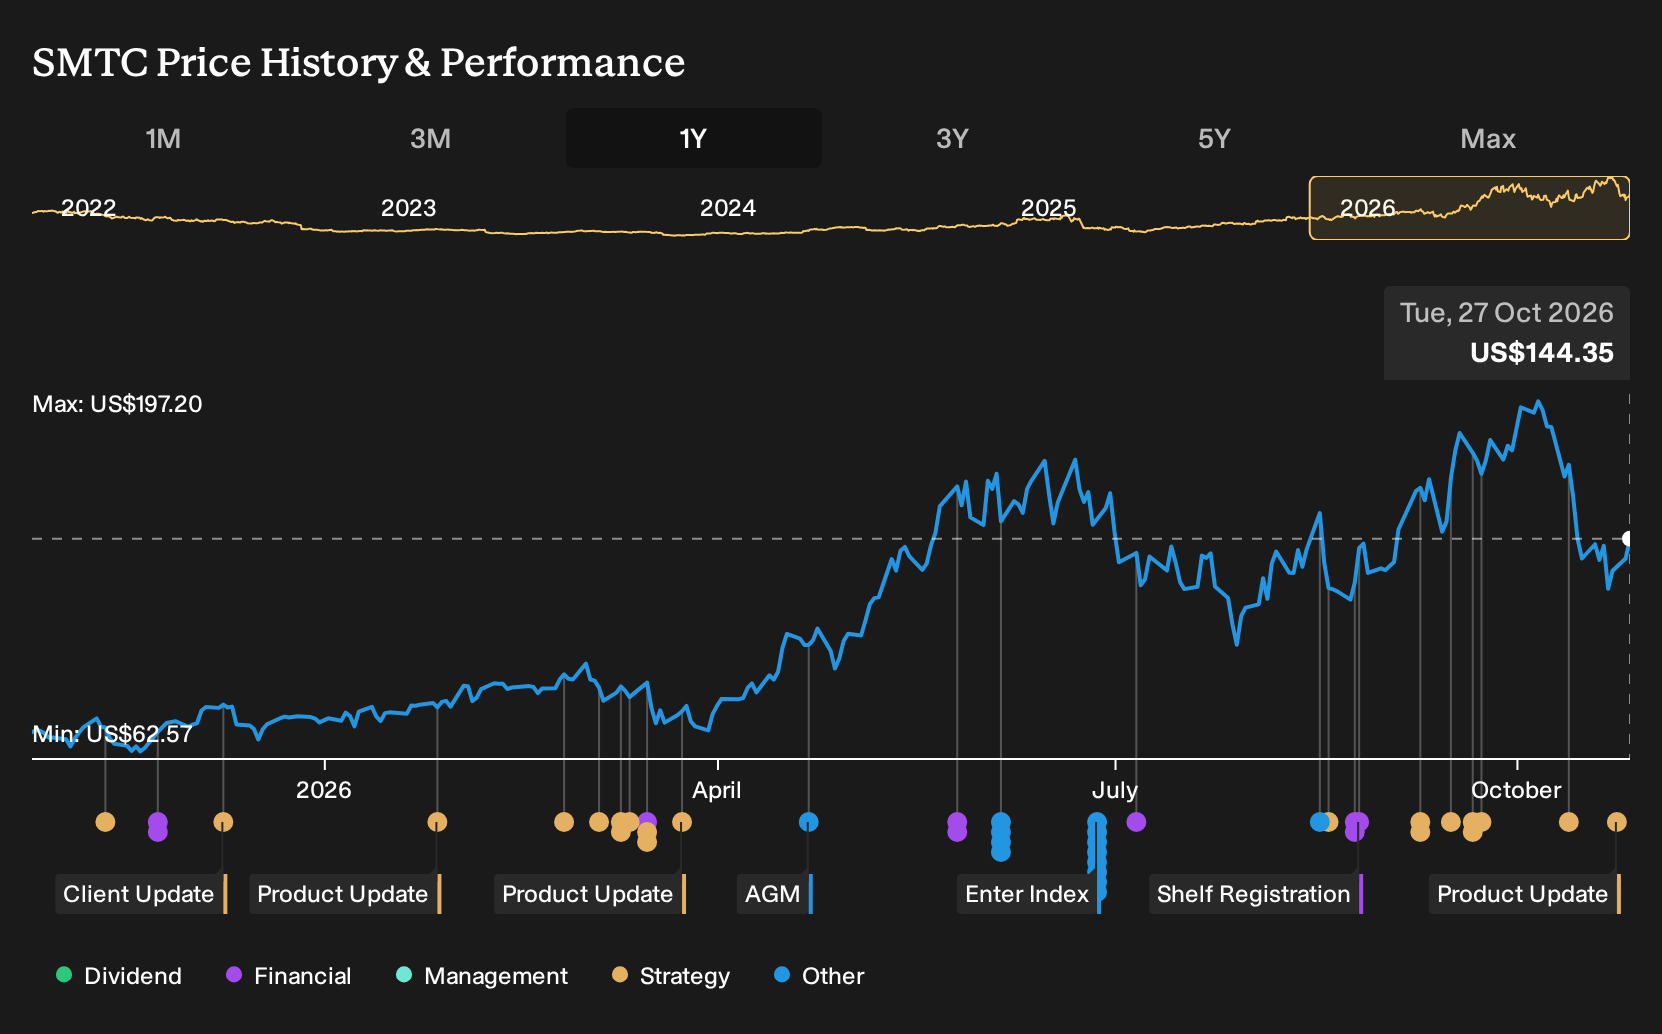
Uncover why Semtech's fair value indicates a 52% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most bullish analysts frame Semtech around data center acceleration rather than router margins. They were sketching out revenue near US$4.3b and earnings around US$1.1b by 2029 before this AirLink 5G update. You might see this security focused launch and wonder if those optimistic AI heavy assumptions now look more realistic or still stretched.
Explore 2 other Semtech fair value estimates, including one that suggests as much as 52% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Semtech research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Semtech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Semtech's overall financial health at a glance.
Looking for more Semtech style investment ideas?
If the Semtech story around 5G, AI and secure connectivity has your attention, it can be useful to compare it with other companies that share some of the same financial or balance sheet traits. The Simply Wall St Screener helps you quickly sort through global stocks using the factors that matter most to you.
- For readers who care most about resilience and capital protection, consider filtering for 30 resilient stocks with low risk scores that may align better with a cautious approach.
- If reliable balance sheets are a priority, use the screener to narrow the market down to a list of solid balance sheet and fundamentals (24 results) that you can review alongside Semtech.
- When you want to widen your watchlist beyond well covered stories, scan a 21 high quality undiscovered gems that could merit a closer look next to your Semtech work.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com