
Daifuku (TSE:6383) Could Be 11% Undervalued As IFRS Shift Draws Focus
Daifuku (TSE:6383) drew fresh attention on 28 October 2026 after its board met to discuss voluntarily adopting International Financial Reporting Standards for consolidated accounts, replacing the current Japanese GAAP approach.
Investors have already been active around Daifuku this year, with the share price up 8.58% year to date to ¥5,441 after a 1-day share price return of 4.31% on the IFRS news. The 1-year total shareholder return of 13.74% sits alongside a much stronger 3-year total shareholder return of 128.46%, suggesting long term momentum has been solid even as shorter term moves have cooled recently.
Scan how Daifuku compares with other automation and capital goods players by reviewing a curated set of 94 robotics and automation stocks that could be moving on similar accounting or reporting shifts.
The IFRS news has already nudged Daifuku higher, so you now face a simple fork in the road: pay up after the move, or wait and hope the valuation offers you a cleaner entry.
Preferred P/E of 24.1x: Is it justified?
Valuation for Daifuku now hinges on a P/E of 24.1x, which lines up with a share price of ¥5,441 that screens richer than many machinery peers.
The P/E ratio compares what investors pay today for each unit of current earnings. For a material handling and automation specialist like Daifuku, this measure often reflects expectations for future profit growth, earnings quality, and how dependable those cash flows appear.
Here, the story is mixed. High quality earnings and a long run of profit expansion sit beside forecasts that point to earnings growth of 9.73% per year, which is quicker than the wider JP market but not extremely fast. A richer P/E can indicate the market is already baking in steady progress, so anyone paying today needs to be comfortable that this level of growth and return on equity near the current 16.7% remains supported.
The comparison with peers is stark. Daifuku trades on a P/E of 24.1x, while the JP Machinery industry average sits at 12.5x and the peer group average is 16.9x. The fair P/E estimate of 20.5x is also lower than where the shares trade now, which clearly signals a premium that the market could demand the business grow into over time.
Explore the SWS fair ratio for Daifuku.
Result: Price-to-earnings of 24.1x (OVERVALUED)
Still, any wobble in IFRS adoption progress or a slower order cycle for Daifuku’s automation projects could quickly challenge today’s premium valuation story.
Find out about the key risks to this Daifuku narrative.
Another View: SWS DCF Says Daifuku Is Cheap
The market asks you to pay 24.1x earnings for Daifuku, yet the SWS DCF model points in the opposite direction. On that cash flow view, the shares at ¥5,414 sit around 10.8% below an estimated value of ¥6,066.67, which makes today’s premium P/E less clear cut.
For a closer look at how that cash flow view is built and what would need to change for the valuation to move, Look into how the SWS DCF model arrives at its fair value.
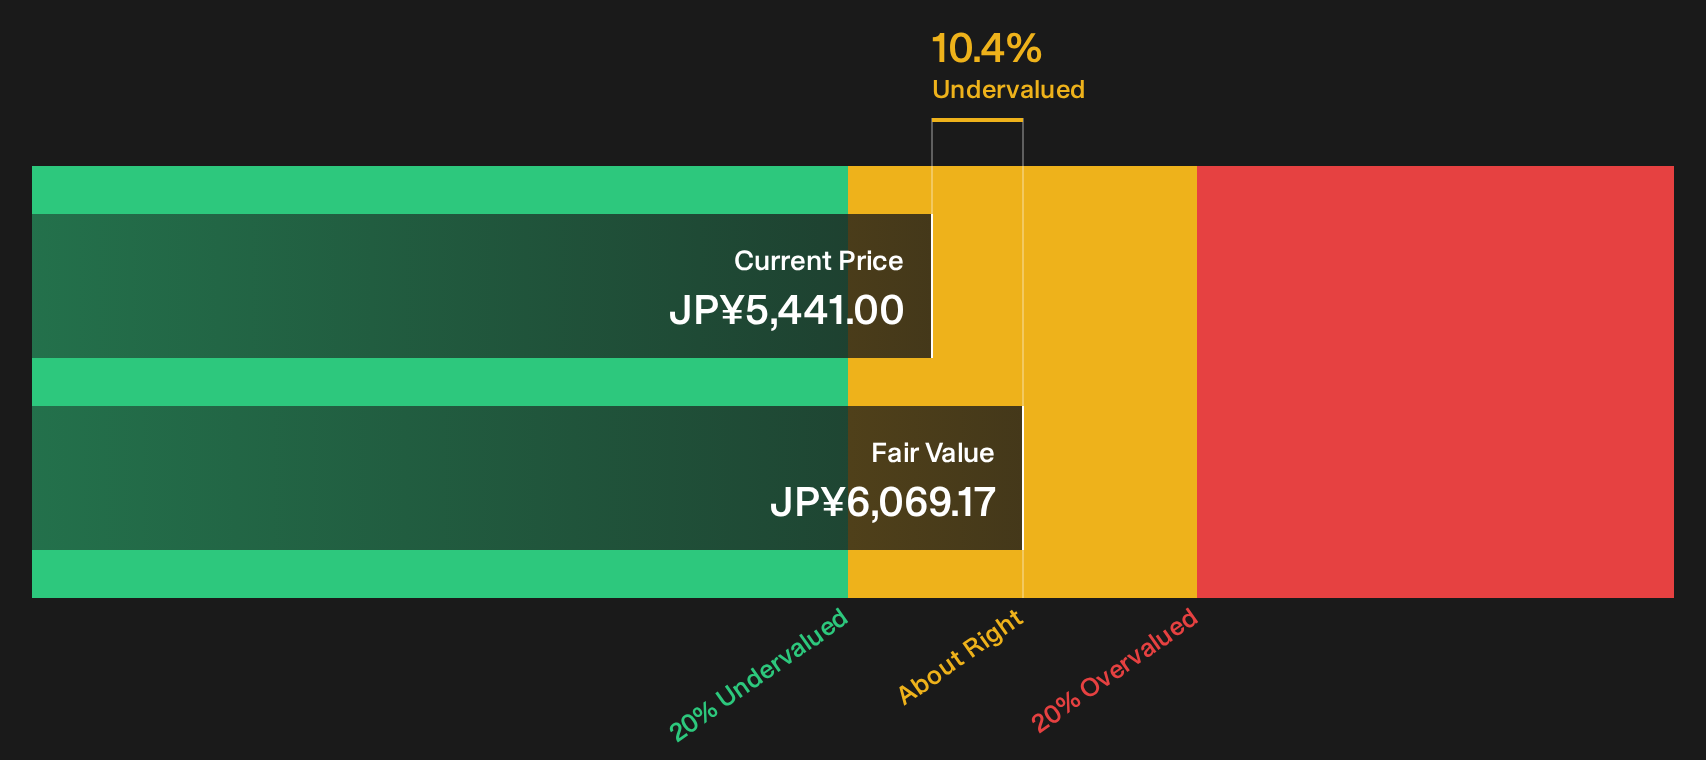
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Daifuku for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of IFRS change and valuation tension around Daifuku leaves you on the fence, move quickly to test the numbers yourself and stress test your assumptions against the 4 key rewards
Ready for more ideas beyond Daifuku?
If Daifuku has sharpened your focus on valuation and accounting shifts, do not stop here. Broader opportunity often turns up where fewer investors are already looking.
- Target potential value gaps by scanning a curated 16 high quality undervalued stocks that filters for quality first instead of chasing headlines.
- Lock in the potential for steadier portfolio income by reviewing a hand picked group of 29 dividend fortresses that aim to balance yield with resilience.
- Prioritise capital protection by sorting through a focused 22 resilient stocks with low risk scores that screens for businesses with stronger risk profiles before momentum crowds in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com