
Fortrea Holdings (FTRE) Climbed, What Is Behind The Latest Attention?
Fortrea Holdings (FTRE) announced a new collaboration with Australian precision oncology group Omico that focuses on biomarker matched cancer trials, putting its clinical research capabilities in direct contact with a large genomics driven patient pool.
For investors, the Omico announcement comes on top of a strong run in Fortrea Holdings' shares, with a 30 day share price return of 21.78% and a year to date share price gain of 45.33%. The 1 year total shareholder return of 134% contrasts with a 3 year total shareholder return that is down 13.55%, signaling that momentum has picked up recently after a tougher longer term stretch.
Spot fresh momentum stories around Fortrea Holdings by scanning our hand picked 21 high quality undiscovered gems in contract research, healthcare services, and adjacent niches.Bulls see Fortrea Holdings harnessing Omico, rising oncology exposure and recent share price momentum, while bears point to analyst caution and recent value destruction. Which story does the current valuation lean toward?
Most Popular Narrative: 19% Overvalued
Fortrea Holdings closed at $24.43, compared with a narrative fair value estimate of about $20.55, so the most followed thesis sees the share price ahead of that central valuation, even after the Omico oncology tie up and recent rally.
Fortrea's ongoing investments in AI-driven software (e.g., the Accelerate platform's Risk Radar module) and digital capabilities are enabling operational efficiencies and differentiated offerings in a market moving toward more technology-enabled, decentralized clinical trials. This is expected to positively impact EBITDA margins and margin expansion. Post-spin, the company has executed significant cost optimization initiatives (achieving over $50 million in net savings year-to-date and targeting $90 to $100 million for the year), with further SG&A savings and margin improvements anticipated in 2026 as more of these initiatives annualize, supporting both EBITDA and net income growth.
See why 8 investors see Fortrea Holdings as 19% overvalued.
Result: Fair Value of $20.55 (OVERVALUED)
Still, customer concentration and a very high implied future P/E multiple leave Fortrea Holdings exposed if large clients pull back or analyst earnings assumptions prove too optimistic.
Find out about the key risks to this Fortrea Holdings narrative.
Another View: What Multiples Say About Fortrea Holdings
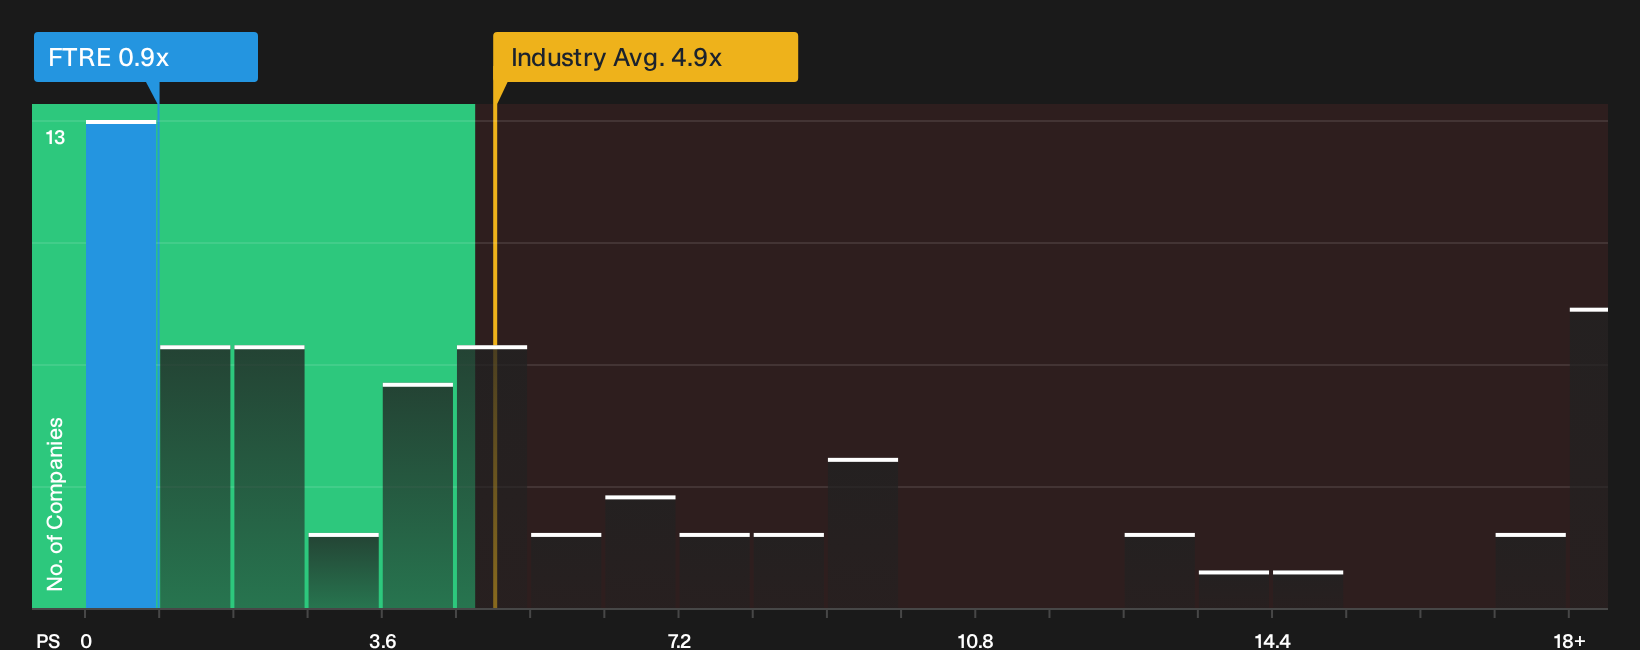
While the narrative fair value points to Fortrea Holdings trading about 19% above a $20.55 estimate, the market’s own yardsticks tell a different story. On a P/S of 0.9x, the stock sits far below both peers at 28x and a fair ratio of 2.4x.
That gap suggests investors are pricing in a lot of execution risk even with the Omico oncology push and recent share price strength. This raises a simple question for you: Is this discount a warning sign or a window to recheck the underlying assumptions.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seeing mixed signals around Fortrea Holdings and not sure which side you land on yet? Act while the data is fresh and weigh both angles by reviewing the 2 key rewards and 2 important warning signs.
Looking for more Fortrea Holdings sized ideas?
If Fortrea Holdings has your attention, do not stop here. Broaden your watchlist with fresh setups that line up with your risk, income, and quality preferences.
- Target potential mispricing by scanning companies with strong fundamentals that trade below their implied value using the 29 high quality undervalued stocks.
- Lock in potential income ideas by reviewing resilient payers with higher yields through the 5 dividend fortresses.
- Dial down risk while staying invested by filtering for sturdier balance sheets and cleaner fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com