
What TGS (OB:TGS)'s Earnings And Dividend Update Means For Shareholders
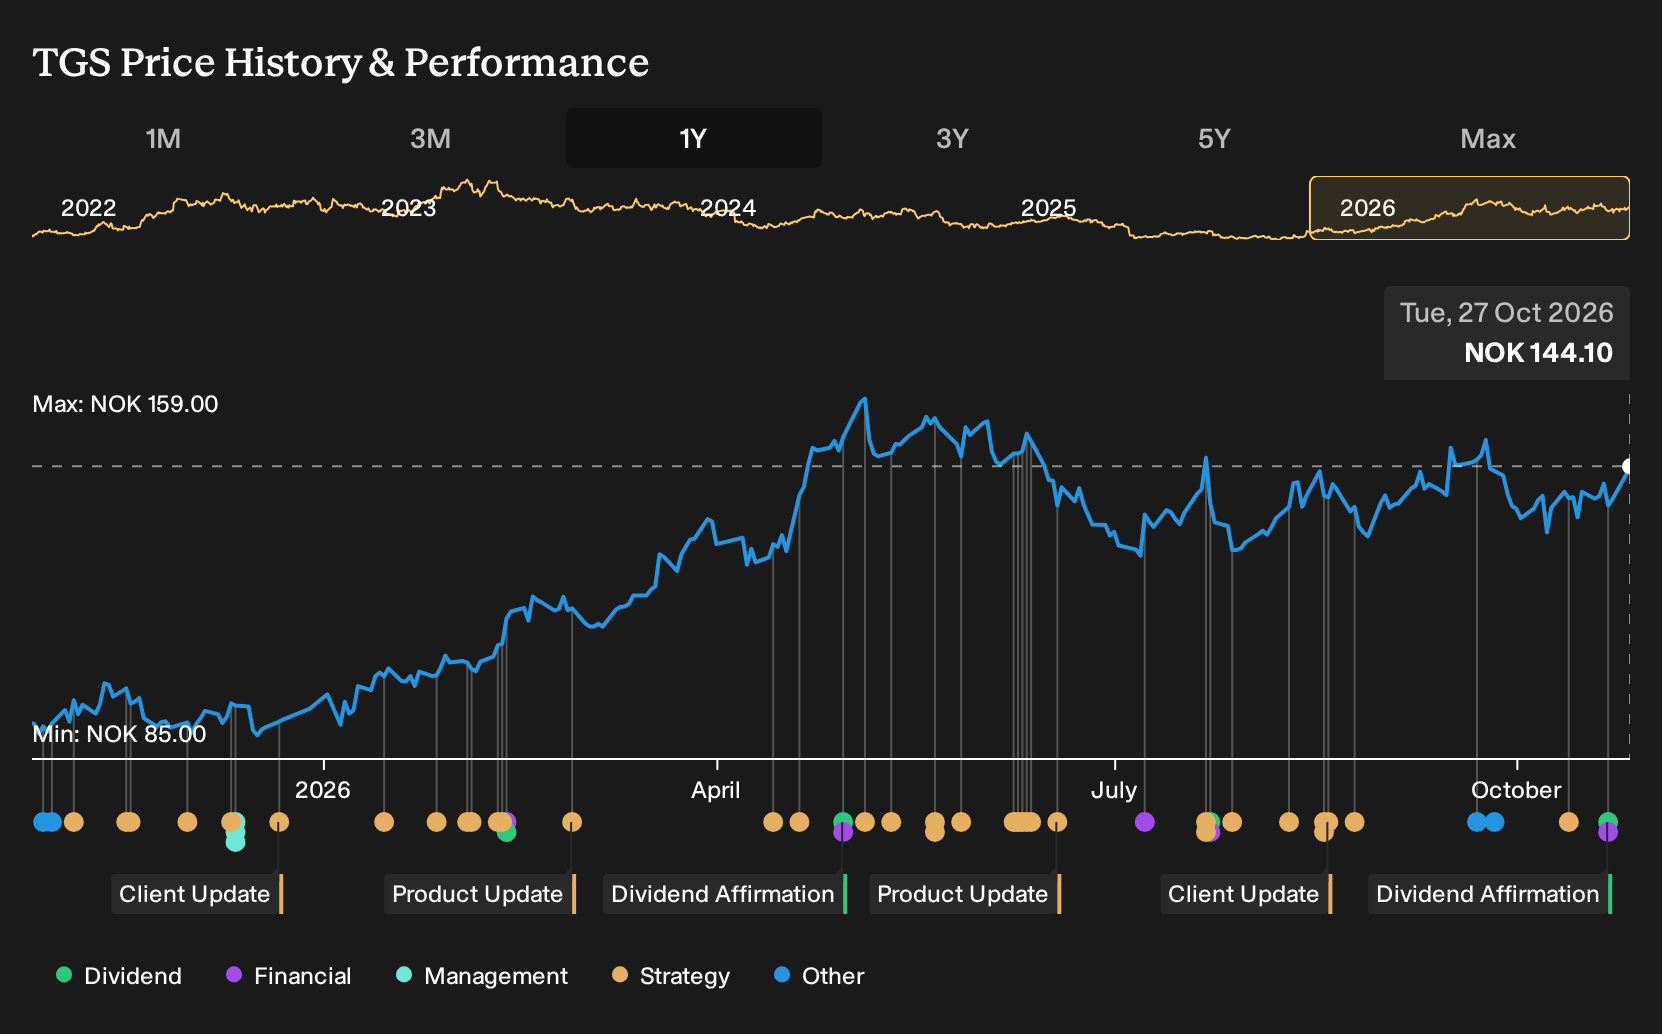
- TGS ASA reported third quarter 2026 sales of US$428.3 million with net income of US$52.3 million, and the Board approved a quarterly dividend of US$0.155 per share, equivalent to NOK 1.45, for payment in November 2026.
- Year to date, TGS has generated US$1,088.2 million in sales and US$65.9 million in net income. This result differs meaningfully from the same period a year earlier, even though third quarter revenue and profit remained close to last year’s levels.
- We will now look at how TGS's reaffirmed dividend and solid nine month profitability could influence the existing investment narrative.
Scan how TGS's reaffirmed payout compares with other income ideas by reviewing our hand picked 224 dividend fortresses alongside this quarter's numbers.
TGS Investment Narrative Recap
TGS appeals to shareholders who think the current exploration spending cycle can keep multi client sales and vessel utilization reasonably healthy, while new data and imaging solutions support earnings quality. The latest quarter showed steady revenue and modest profit from continuing operations, which suggests the basic operating setup is intact rather than transformed.
In the short term, the key swing factor remains how exploration budgets behave versus TGS's cost base. Management is already dealing with higher operating expenses, and any renewed pressure on client spending or pricing could squeeze margins. The fresh quarterly figures and dividend affirmation do not materially change that near term risk reward balance.
The reaffirmed quarterly dividend of US$0.155 per share, payable on 12 November 2026, links directly to how TGS is converting its seismic backlog and technology offering into cash. With a dividend yield flagged as not fully covered by current earnings, the payout depends heavily on future profitability and cost control holding up.
For catalysts, the more interesting signal is still operational. TGS is relying on high vessel utilization, multi client investments and products such as Apparition encoding and Gemini X to support margins and data value. The new earnings release provides an updated profit baseline for judging whether that plan is generating enough cash to keep funding both the library and ongoing dividends.
TGS' narrative projects US$1.8b revenue and US$421.9 million earnings by 2029. This would require 9.7% yearly revenue growth and an increase in earnings of about US$349.1 million from US$72.8 million today.
Uncover how TGS' fair value indicates a 4% potential upside to its current price before the gap can close.
Exploring Other Perspectives
For a sharply different angle, some bullish analysts lean hard into TGS turning cost cuts and AI driven imaging into much higher earnings. Before this dividend and earnings update, the most optimistic projections were for revenue of about US$1.9b and earnings of roughly US$456.3 million by 2029. That is far above the consensus path. You do not need to agree with that story, but it helps to compare several viewpoints and decide which set of assumptions feels closer to your own.
Explore 2 other TGS fair value estimates, including one that suggests as much as 114% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TGS research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TGS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TGS' overall financial health at a glance.
Looking For More Ideas Beyond TGS?
If you want to stress test your view on TGS against other opportunities, it helps to line it up against a broader watchlist of stocks with clear, data backed traits.
The Simply Wall St Screener lets you filter the market quickly so you can focus on a handful of businesses that actually fit your income, quality or risk profile.
- For investors hunting for strong cash generation and financial resilience, compare TGS with a list of solid balance sheet and fundamentals (207 results) that can help anchor a long term portfolio.
- If potential mispricing is what catches your eye, weigh TGS alongside a 195 high quality undervalued stocks that our filters flag as combining quality fundamentals with attractive pricing.
- If you prefer steadier ride candidates, even if the upside story takes time to play out, then set TGS next to a 223 resilient stocks with low risk scores based on our risk scoring framework.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com