
Did Cable Factory Expansion Just Shift NKT (CPSE:NKT) Investment Narrative?
- NKT has completed a €50 million expansion of its Esposende, Portugal factory, adding new medium and high voltage power cable lines, upgraded testing facilities and raising headcount to 580 employees.
- The Esposende upgrade turns the former SolidAl site into a larger, integrated cable hub that can support NKT’s energy transition focused project pipeline with added medium and high voltage capacity.
- We will now look at how NKT's expanded Esposende high voltage cable capacity could influence the broader investment narrative.
Scan beyond NKT and size up other grid-focused players by reviewing the 42 power grid technology and infrastructure stocks, which screens for companies tied to power cable and infrastructure demand.
NKT Investment Narrative Recap
NKT is essentially a grid build out story. To stay comfortable as a shareholder, you need to believe the €2b capex program, including Esposende, turns high voltage and medium voltage capacity into profitable project delivery rather than just more fixed cost. The Esposende ramp up lands right as 2026 transmission revenue is expected to decline organically, so utilization and order intake over the next year matter a lot.
The main short term catalyst is how cleanly NKT brings new plants and assets from ramp phase into steady production, without eroding operational EBITDA margins that are already guided to be diluted in 2026. The biggest risk remains that high capex and ramp related costs extend the period of weaker free cash flow or pressure pricing if demand timing slips.
The Esposende expansion is directly tied into the wider €2b capex plan that includes new high voltage facilities, medium voltage upgrades and installation assets such as the Eleonora vessel. That broader build out is intended to align NKT capacity with long dated backlog and grid investment, and the Portuguese site now forms another leg in that industrial footprint.
For you as an investor, the operational test now is execution sequence. Esposende enters ramp up at the same time management expects group EBITDA margins to be diluted by new investments and free cash flow to be negative in 2026. Progress on order conversion, backlog delivery and any signs of stabilising cash outflow around these assets are likely to shape how the NKT story is viewed over the next couple of years.
What The Esposende Ramp Means Against NKT’s Consensus Numbers
NKT's narrative projects €5.3b revenue and €471.0m earnings by 2029. This assumes 14.0% yearly revenue growth and an earnings increase of about €203m from €268.0m today.
Those consensus figures sit in the background of everything now happening at Esposende. Extra high voltage capacity only really helps you as a shareholder if it feeds into that €5.3b top line and supports the move from about €268.0m in earnings today toward the €471.0m that analysts model for 2029, without breaking the cost base.
Think about the Portuguese factory as one of the early proof points. If the expanded site can run at healthy utilization, keep quality issues contained and avoid lengthy teething problems, it makes the assumed step up in margin from 7.5% to 8.8% easier to defend. If it struggles, a lot more pressure shifts to the other high voltage expansions and vessels to carry the earnings load.
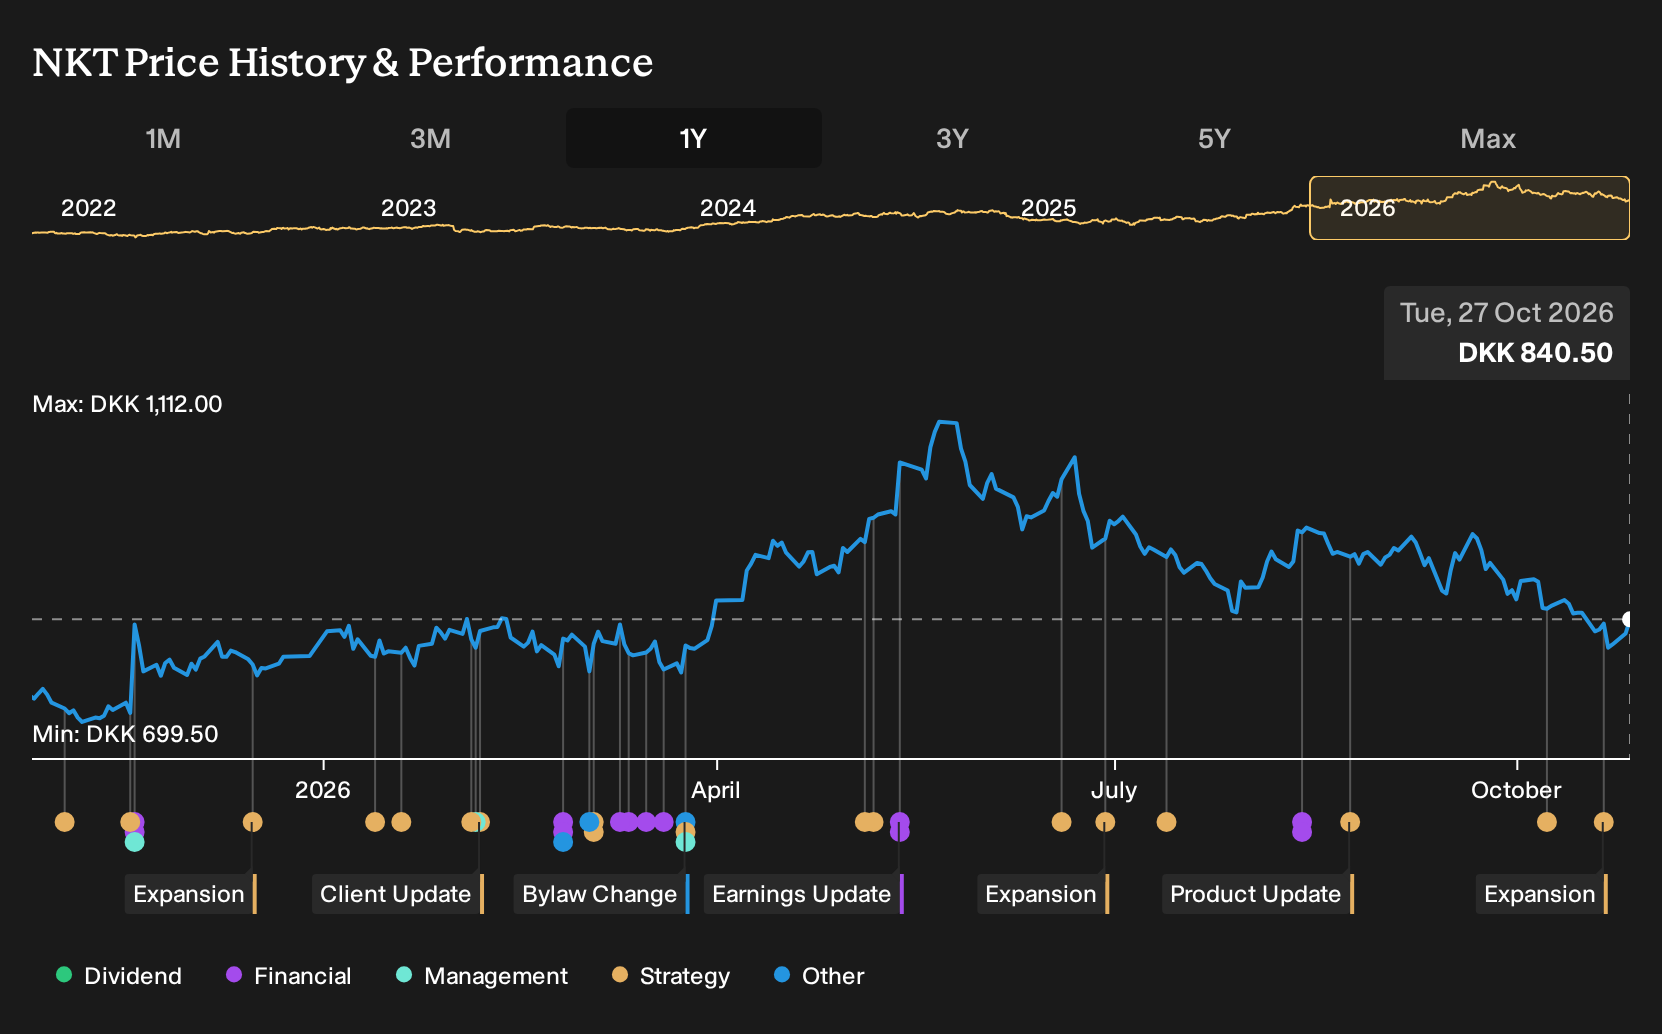
Analysts are effectively saying that at the current share price, the market is pricing NKT on a higher P/E today than the 18.7x multiple implied on those 2029 earnings. Execution around assets like Esposende is a significant factor in whether investors remain comfortable underwriting that type of earnings bridge and multiple compression over the next few years.
Uncover why NKT's fair value indicates an 18% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternative view on NKT leans hard into margin pressure as the key risk. The most cautious analysts were only pencilling in about €5.1b of revenue and €459.8m of earnings by 2029 before this Esposende expansion news. That is a far more pessimistic story. It shows how widely opinions can differ, so it is worth exploring several viewpoints and asking how this fresh factory ramp might shift those older forecasts.
Explore 3 other NKT fair value estimates, including an estimate that suggests it could be worth just DKK988.50.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NKT research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NKT. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NKT's overall financial health at a glance.
Looking for more investment ideas beyond NKT?
Once you have formed a view on NKT, it can help to compare it with other opportunities that fit different risk, income and quality profiles using the Simply Wall St Screener.
- If you want resilient balance sheets to anchor your portfolio, start with our list of solid balance sheet and fundamentals (207 results) and see which businesses match that profile.
- For investors who care most about quality at a sensible entry price, scan through our 195 high quality undervalued stocks and spot which companies line up with your return and risk preferences.
- Income focused readers who prize reliability can review our 224 dividend fortresses and see which stocks line up with their yield and stability goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com