
How Investors Are Reacting To Coeur Mining (CDE) Ahead Of Earnings Report
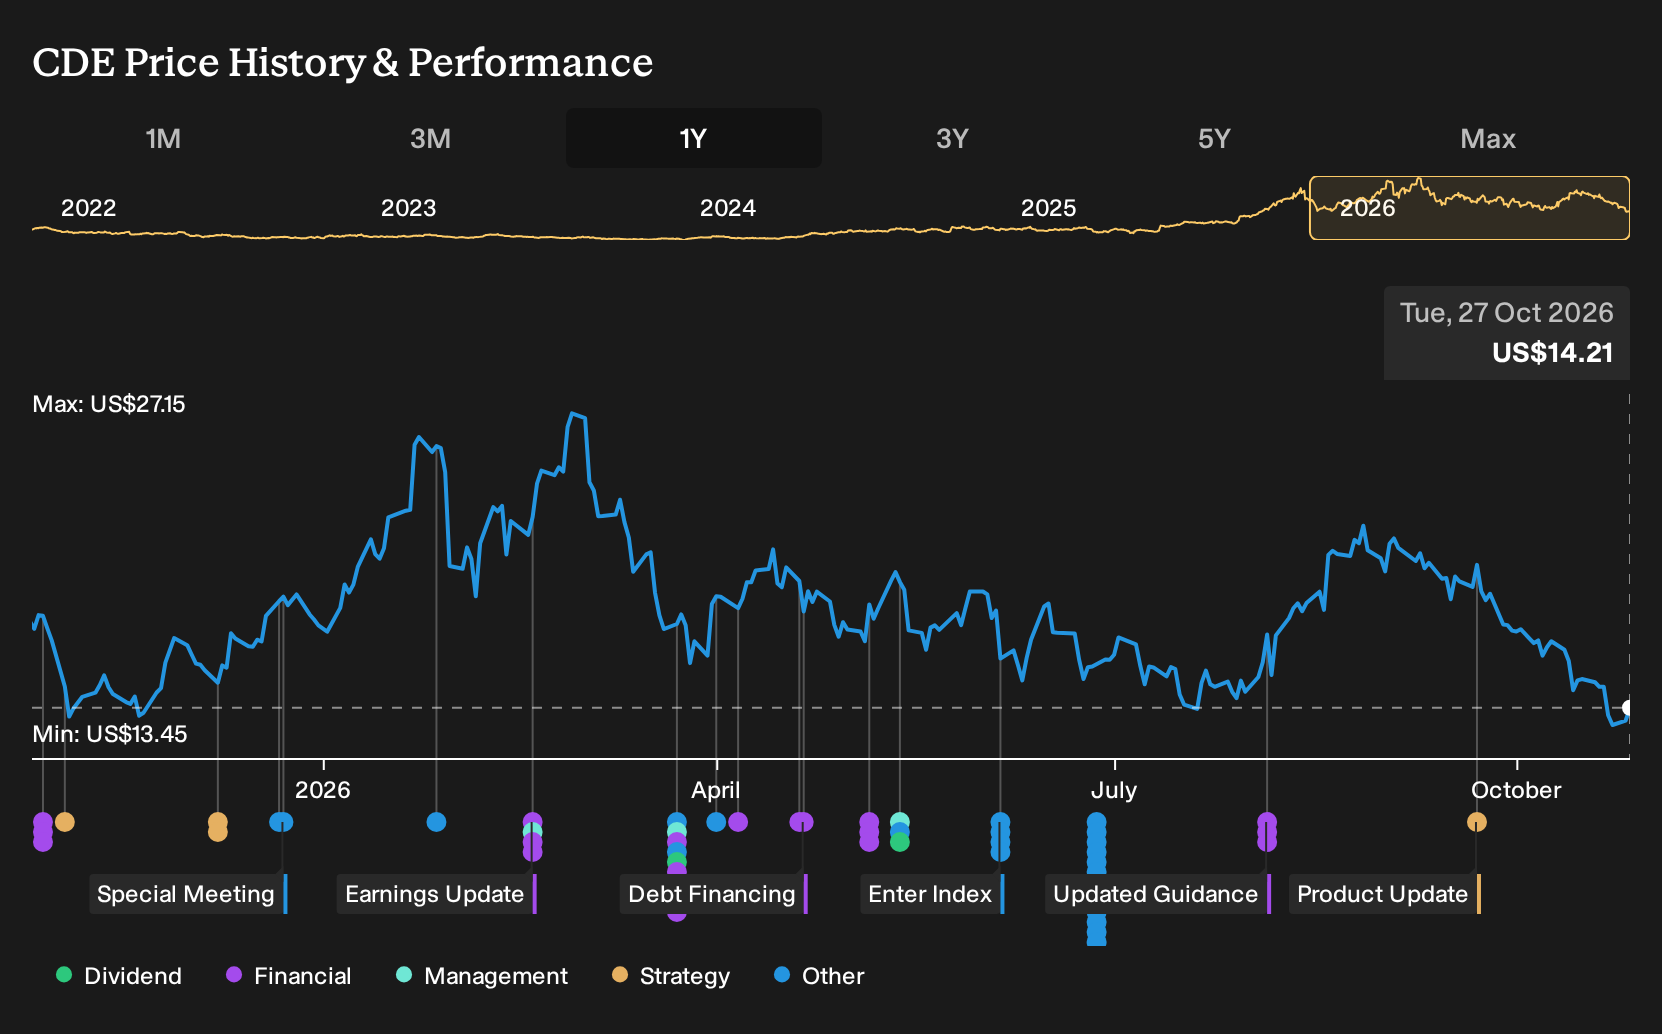
- Coeur Mining previously announced it would release third quarter 2026 operational and financial results after the close on Wednesday, 4 November, with the period drawing attention due to expected earnings per share of $0.15 and forecast revenue of $1.25b.
- The combination of a projected year over year decline in EPS alongside significantly higher expected revenue highlights pressure on profitability even as Coeur Mining scales its top line.
- This analysis will now examine how Coeur Mining's investment narrative could shift in light of lower EPS expectations despite much higher projected revenue.
Scan how Coeur Mining's setup compares with other precious metals producers under pressure on earnings but scaling revenue through our curated 35 elite gold producer stocks.
Coeur Mining Investment Narrative Recap
To own Coeur Mining, you need to be comfortable with a miner that is leaning into growth projects and higher expected revenue while accepting pressure on earnings in the near term. The sharp share price pullback over the past month and the upcoming third quarter release keep the focus on how efficiently Rochester, Las Chispas and other assets are run.
The key short term catalyst is the 4 November report. It should give you a clearer read on whether cost pressures, currency moves and capital spending are containing margins. The biggest current risk is that heavier investment and prior dilution do not translate into sustained production and cash generation at the mine level.
The earnings update flagged for 4 November is the announcement that matters most right now. Coeur Mining is expected to post quarterly EPS of US$0.15 with revenue of US$1.25b, alongside a year on year decline in EPS. The stock also fell roughly 30% over the past month, which makes the print a key sentiment check.
What you want to see in that release is simple: clear progress on operating efficiency at key sites, disciplined handling of high capital intensity and some comfort that regulatory and permitting timelines are not stretching out further. Any gap between weaker EPS and much higher sales will likely be read through the lens of execution, not headlines.
What The Current Consensus Implies For Coeur Mining
Coeur Mining's current analyst narrative points to US$5.9b in revenue and US$2.6b in earnings by 2029. That profile reflects assumed annual revenue growth of 23.1%, with earnings expected to rise by roughly US$1.75b from about US$850.4m today.
Discover how Coeur Mining's fair value indicates a 64% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate view fixates on ramp risk at Rochester, New Afton and Rainy River. The most pessimistic analysts were modelling about US$8.0b of 2029 revenue and roughly US$2.8b of earnings, but on a much lower 10.6x P/E. That tells you opinion on Coeur Mining is wide open. Treat the 4 November update as a chance to test both stories.
Explore 5 other Coeur Mining fair value estimates, including one that suggests it could be worth just $18.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Coeur Mining research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Coeur Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coeur Mining's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coeur Mining?
Once you have a view on Coeur Mining, it can help to compare that thesis with other listed businesses that share similar traits or offer very different risk and return profiles. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If you want a starting point for potential mispricing, scan a hand picked 29 high quality undervalued stocks that currently combine quality fundamentals with discounted market expectations.
- For readers who care most about strength in the balance sheet, filter for companies with low leverage and solid liquidity through our focused list of solid balance sheet and fundamentals (24 results).
- If you prefer to hunt for opportunities the market may be overlooking, work through a curated 21 high quality undiscovered gems that screens for strong fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com