
International Paper (NYSE:IP) misses Q3 2026 revenue estimates
Packaging and materials company International Paper (NYSE:IP) missed Wall Street’s revenue expectations in Q3 2026, with revenue flat year on year at $6.20 billion. Its non-GAAP profit of $0.37 per share was 29.5% above analysts’ consensus estimates.
For more on International Paper, read our free full research report.
International Paper (IP) Q3 2026 highlights:
- Revenue $6.20 billion vs S&P analysts’ consensus estimates of $6.29 billion (flat year on year, 1.4% miss)
- Adjusted EPS $0.37 vs S&P analysts’ consensus estimates of $0.29 (29.5% beat)
- Operating margin -17.7% (inclusive of a $1.4B goodwill impairment), down from -3.6% in the same quarter last year
- Free cash flow -$267 million, down from $150 million in the same quarter last year
- Market capitalization $17.68 billion
"Our third-quarter results reflect meaningful progress on our strategy despite persistent macro headwinds," said International Paper Chairman and CEO Andy Silvernail. "In North America, we are improving our operational performance, building a structurally lower-cost business and realizing the benefits of prior pricing actions, while continuing to create value for our customers. In EMEA, we executed well on our ongoing restructuring and cost-out initiatives, while the macro environment continued to weigh on results and pace of margin recovery."
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a bad business can perform well for one or two quarters, but a high-quality one grows for years. International Paper’s revenue grew at a sluggish 2% compounded annual growth rate over the last five years, falling short of our benchmarks.
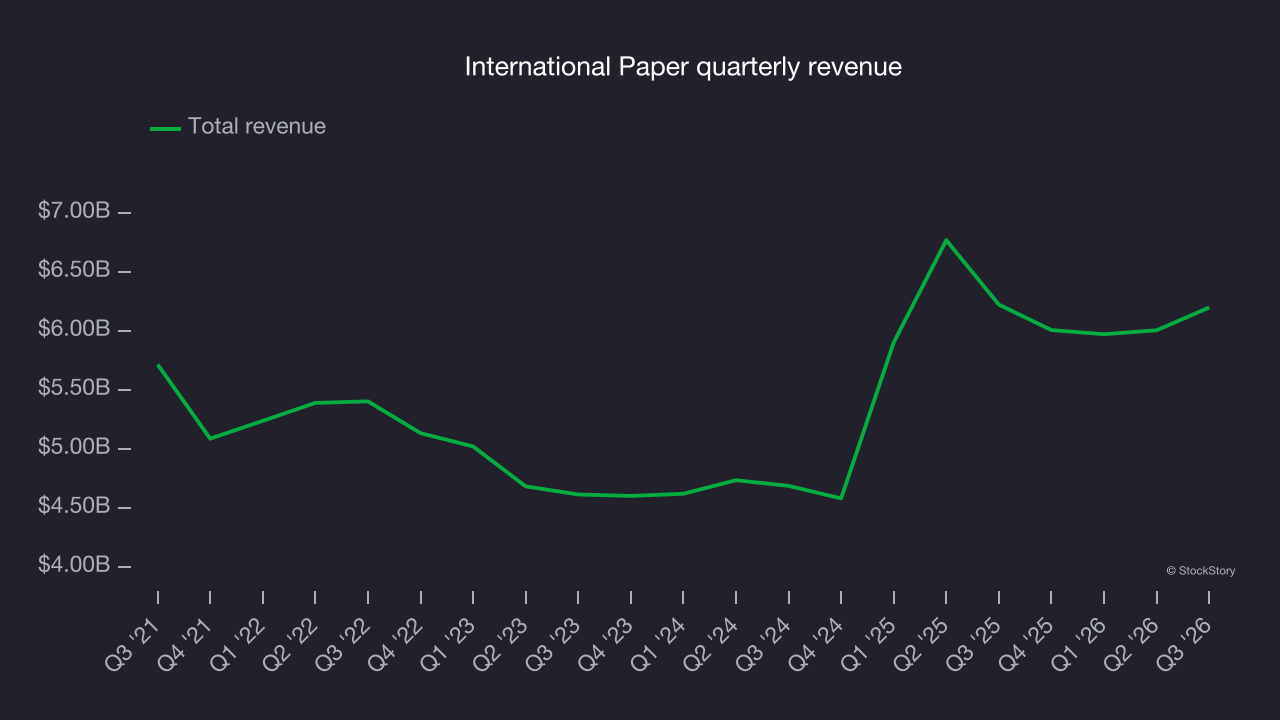
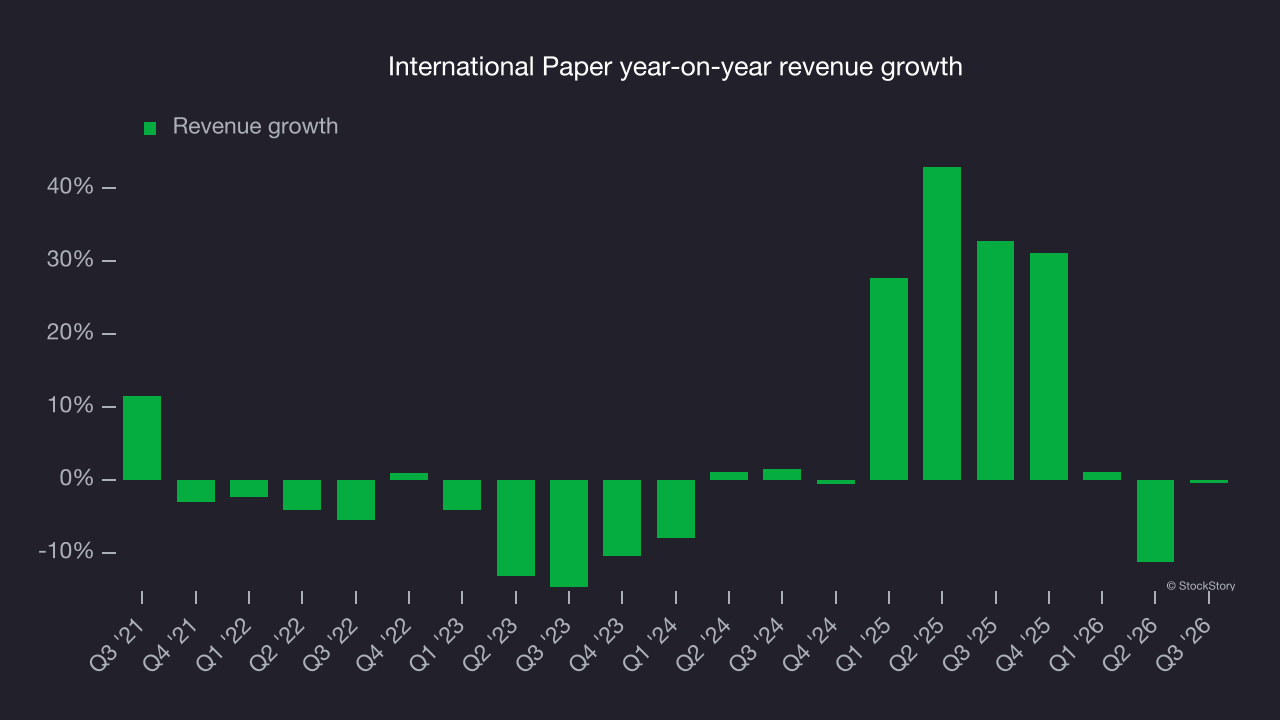
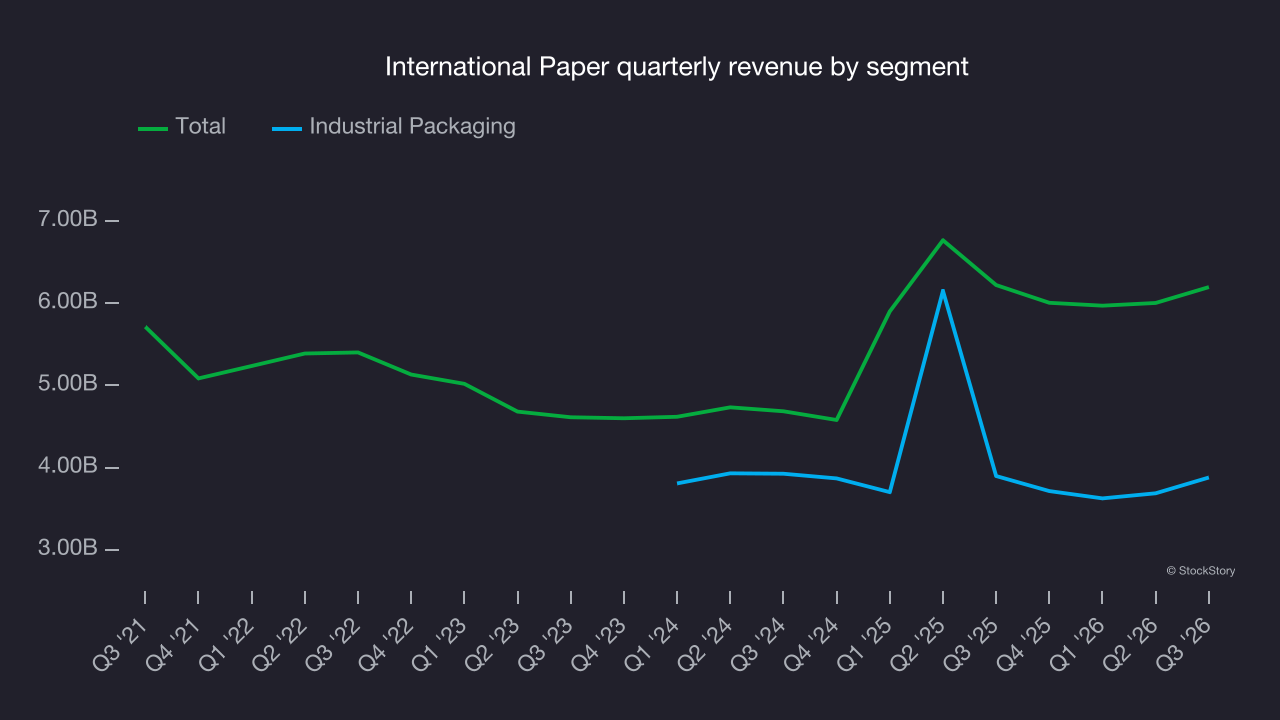
This quarter, International Paper’s $6.20 billion of revenue was flat year on year, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 7.2% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will face some demand challenges.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
International Paper was profitable over the last five years but held back by its large cost base. Its average operating margin of 2.3% was weak for an industrials business.
Looking at the trend in its profitability, International Paper’s operating margin decreased by 11.5 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. International Paper’s poor performance shows that costs were rising and it couldn’t pass them on to its customers.
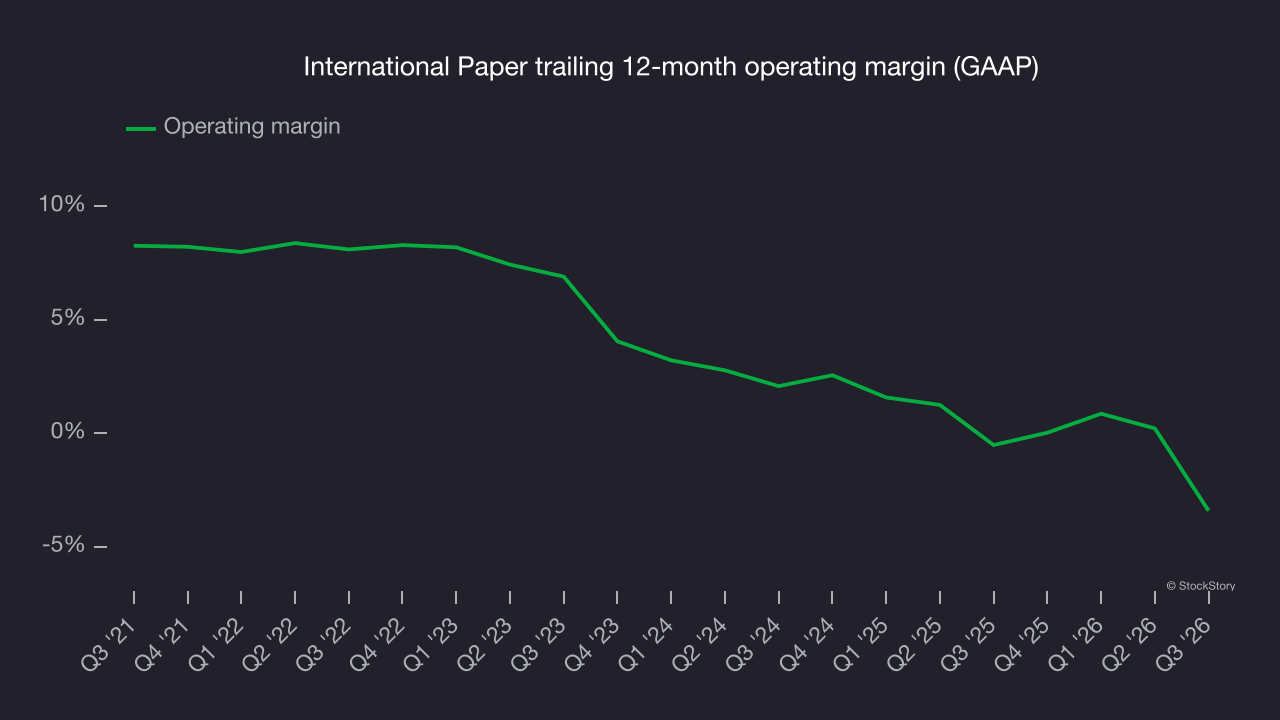
This quarter, International Paper reported an operating margin of negative 17.7%, down 14.2 percentage points year on year. The larger decline in operating margin than in gross margin suggests it was less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
International Paper’s EPS declined by 34.3% annually over the last five years while its revenue grew by 2%. This shows the company became less profitable on a per-share basis as it expanded.
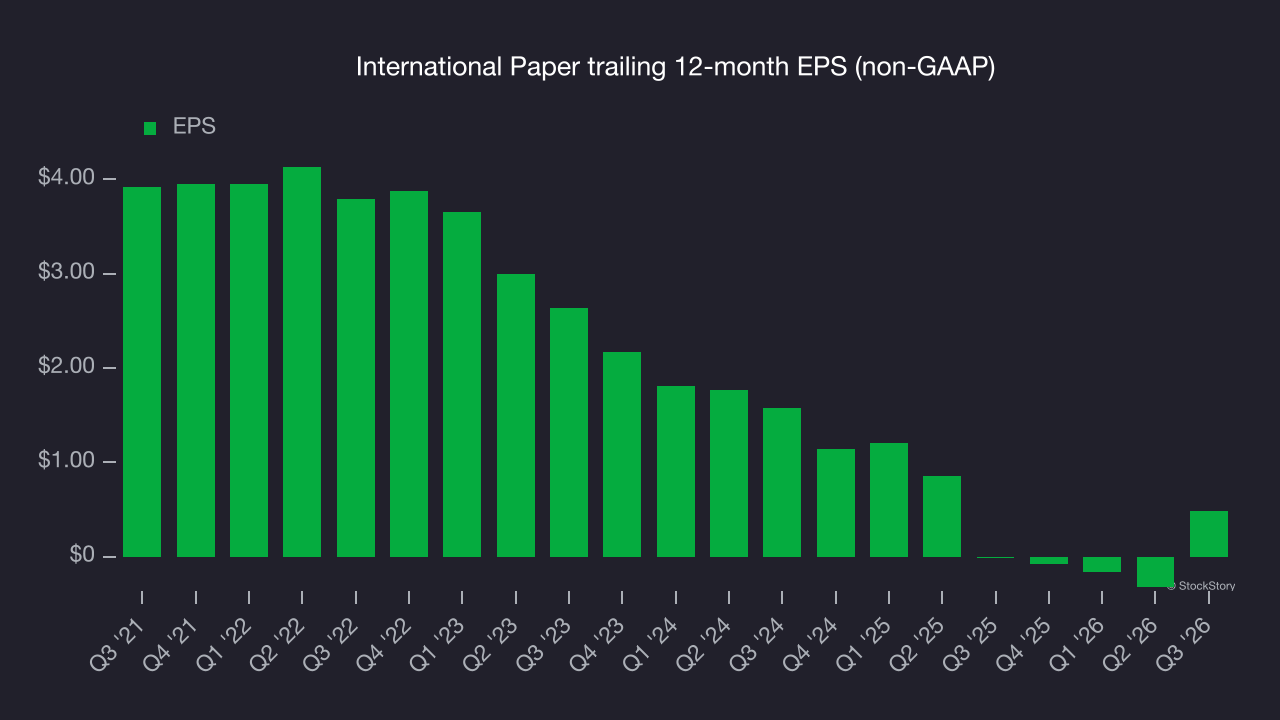
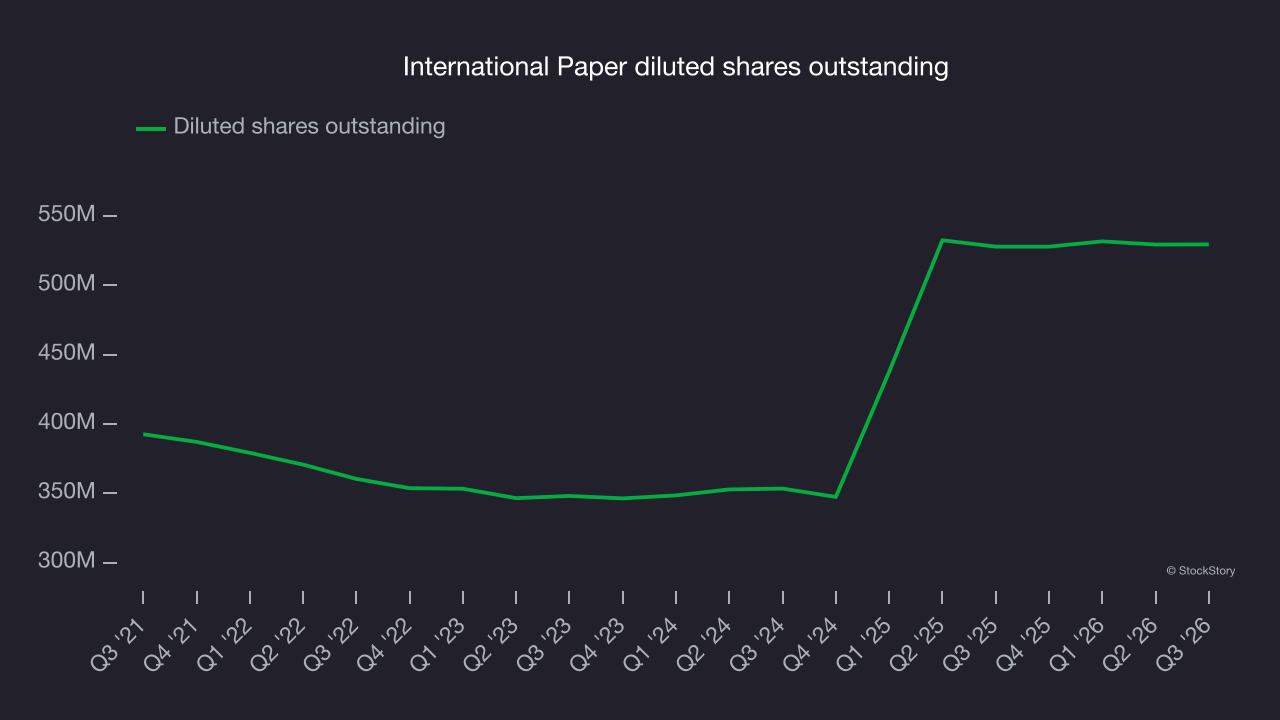
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For International Paper, its two-year annual EPS declines of 44.7% show it has continued to underperform. Results were poor across both periods.
In Q3, International Paper reported adjusted EPS of $0.37, up from negative $0.43 in the same quarter last year. This result easily cleared analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects International Paper’s full-year EPS to grow 464% from $0.48 to $2.71, according to S&P.
Key takeaways from International Paper’s Q3 results
International Paper’s quarter had some key positives, including EPS above analysts’ consensus estimates, but revenue fell slightly short. The market appeared to be hoping for more: Shares fell 3.6% to $32.16 immediately after the report.
Is International Paper an attractive investment at its current price? The latest quarter is only one part of assessing longer-term business quality. Quality, combined with valuation, can help determine if the stock is a buy. For more, read the full research report here (it’s free).