
Visa Rules Could Reshape ManpowerGroup Stock And Global Hiring Shares
Immigration is suddenly a front line business issue, with Anthropic warning that tighter U.S. visa rules could affect its ability to hire elite AI talent just as it prepares for a large IPO that has been reported at around $2 trillion. That kind of pressure on global hiring and rising immigration costs could reshape where work gets done and who benefits. This article explains how that story connects to three stocks exposed to the same forces, and why those dynamics might matter for your portfolio in the coming years.
The three stocks that follow are just a sample set. The full screen on Simply Wall St surfaced 16 more global talent and immigration-dependent professional services companies with equally compelling narratives that are not covered here. If you want to identify which of these businesses best fits your own view on visa risk, offshoring and professional services, head straight into the Global Talent and Immigration-Dependent Professional Services screener to filter, analyze, and focus on your highest-conviction ideas.
ManpowerGroup (MAN)
ManpowerGroup is a direct play on the global talent shuffle, matching employers with skilled workers across borders through staffing, outsourcing and workforce solutions that are heavily exposed to visa programs and offshoring trends.
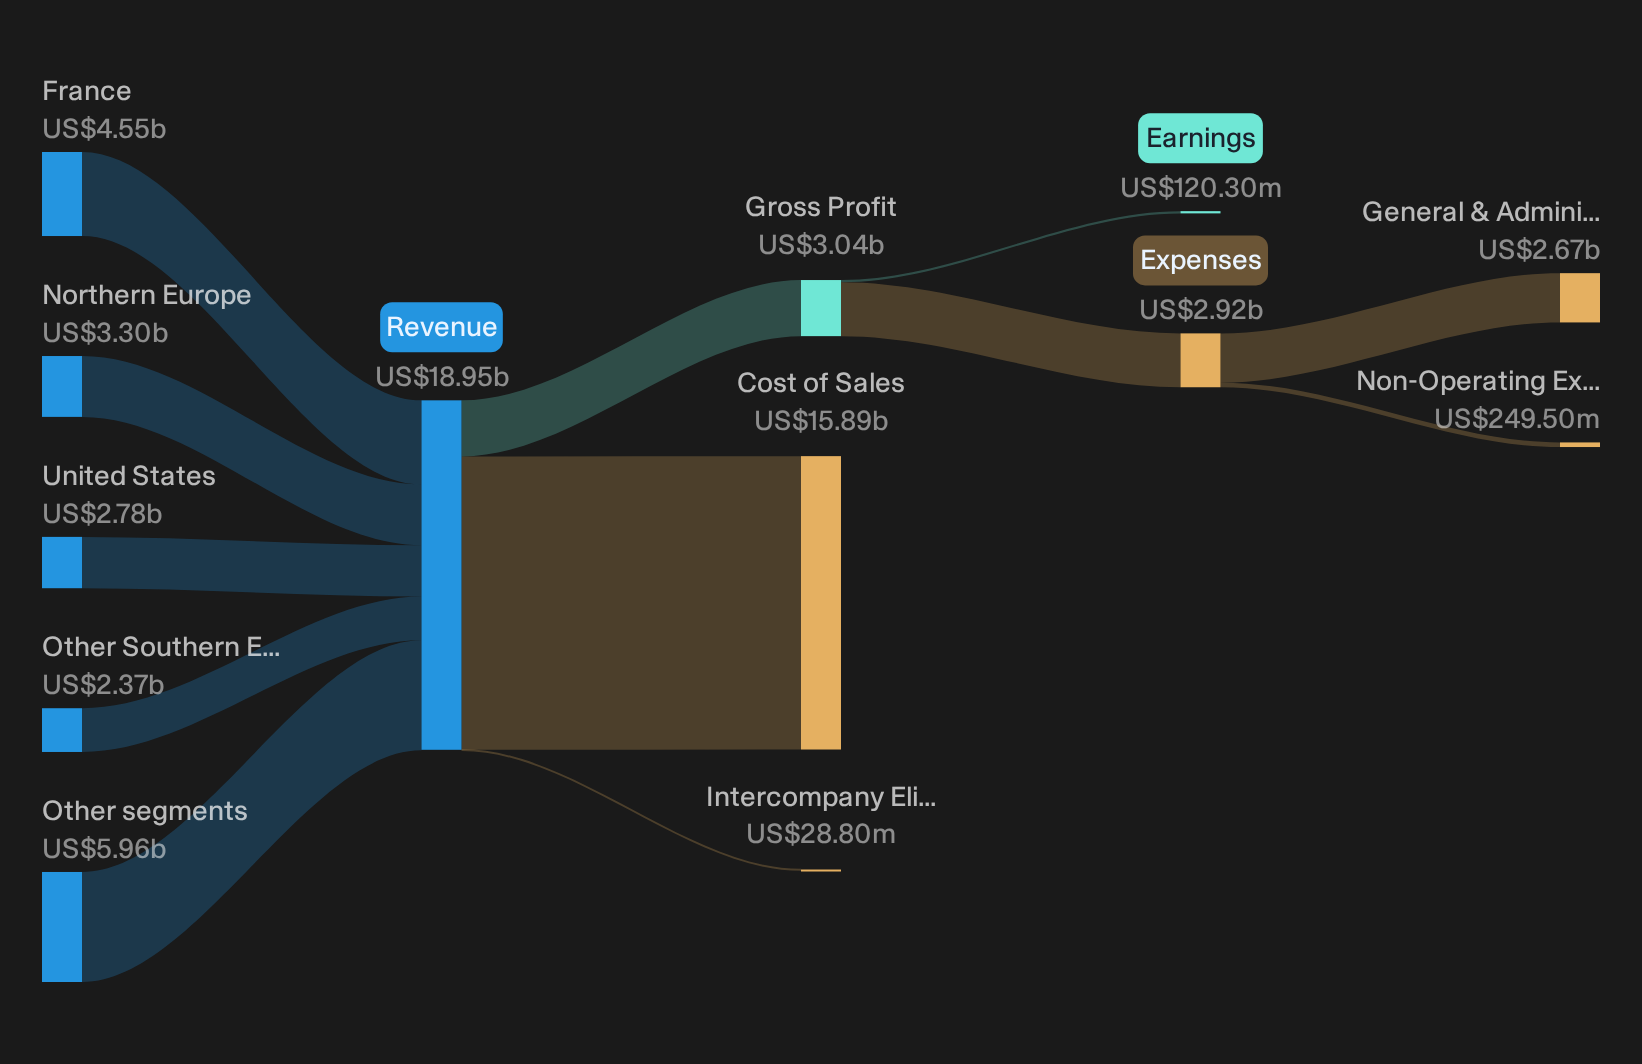
ManpowerGroup runs large scale recruitment, staffing, training, outsourcing and HR services across brands like Experis and Talent Solutions, with sizeable revenue in France (US$4.55b), Northern Europe (US$3.30b), the United States (US$2.78b) and other European and global markets, and a market value of about US$2.1b.
"ManpowerGroup's ongoing investment in AI-driven digital platforms like PowerSuite and Sophie AI is accelerating operational efficiency, enabling more precise sales targeting and automation of recruiting workflows. The latest evidence of an AI-powered sales engine generating about US$200 million of incremental revenue, while AI-led interviews cut screening time and fill times, points to further potential for revenue and EBITA margins as these tools are rolled out toward roughly 70% of global revenues."
What happens to those margin ambitions if a single cost pressure inside cross border staffing moves in the wrong direction?
If that immigration squeeze is the swing factor you care about most, the full narrative for ManpowerGroup shows how ManpowerGroup’s AI push and visa exposure could be decoupling.
Globant (GLOB)
Globant taps into the same cross border talent theme as Anthropic, using distributed engineers to deliver AI heavy software projects for global clients that want offshore capacity rather than adding more onshore headcount.
Globant generates all its US$2.45b in revenue from software and programming services, including AI infused platforms and subscription models, and has a market value of about US$1.94b.
"The rapid adoption of AI and generative AI across industries is increasing the complexity of enterprise technology environments, driving greater demand for specialist partners to design, implement, and maintain tailored AI solutions."
For investors, the real swing factor is how one subtle shift in where that work is delivered may affect Globant's future margins.
That delivery mix is the real pivot, and the full narrative for Globant shows how Globant’s margin story, client concentration and AI pricing power might be shifting under the surface.

Hays (LSE:HAS)
Hays leans directly into the screener theme, using its global recruitment network to match qualified professionals with employers that need cross border talent and more flexible hiring models.
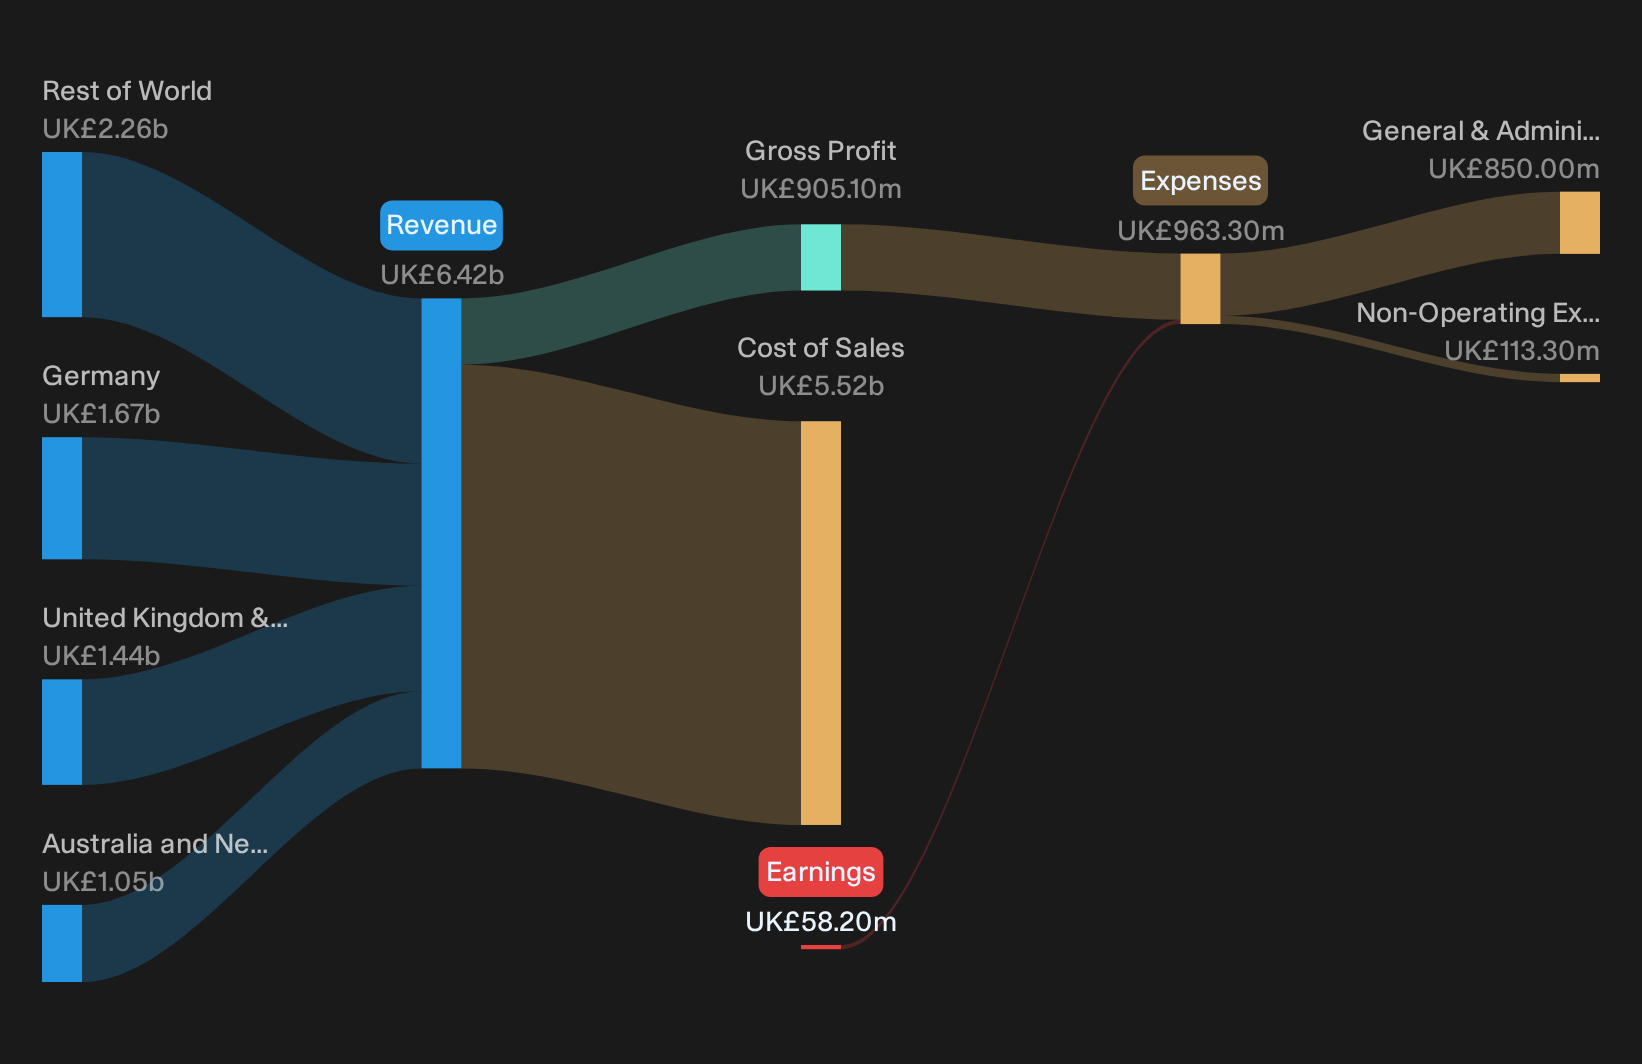
Hays focuses on qualified, professional and skilled recruitment, generating about £6.42b from this activity through temporary, contracting and permanent placements, and has a market value around £956 million.
"Although Hays is reshaping its portfolio toward 16 core markets and exiting smaller operations, sustained losses and a 16 to 17% decline in net fees in France show that underperforming countries can continue to dilute group net margins and delay any improvement in overall earnings quality."
What happens to Hays's earnings rebuild if one core region or specialist area shifts from dragging on profitability to pulling its weight?
If that pivot is what you are watching, the full narrative for Hays shows how Hays's reshaped mix could turn today's drag into accelerating earnings power.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes, new momentum, and under the radar stories can get away fast while it still matters. Do not get caught dropping the ball, act now.
- Spot cash generative compounders early by scanning the list of solid balance sheet and fundamentals (24 results) that filters for resilient businesses before everyone starts talking about them.
- Ride structural themes with pricing power by tracking the 21 high quality undiscovered gems that surfaces under followed opportunities while they are still flying below the radar.
- Target future cash machines by reviewing the 39 profitable AI stocks that aren't just burning cash where real earnings, not hype, drive which AI opportunities make the cut.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com