
Earnings Forecast Lift Might Change The Case For Investing In ATI Stock (ATI)
- ATI is expected to report quarterly earnings that analysts forecast will be significantly higher year over year, with sales contributions from both High Performance Materials & Components and Advanced Alloys & Solutions.
- The prospect of stronger results from each core segment indicates that ATI's product mix and demand profile may be shifting toward higher value applications.
- We will now look at how ATI's forecasted segment wide earnings strength could influence the broader investment narrative around the business.
Scan for other metals and materials stocks with segment momentum similar to ATI by running the curated 29 high quality undervalued stocks alongside this earnings story.
ATI Investment Narrative Recap
To own ATI, you need to believe the business can keep tilting toward higher value aerospace, defense and specialty energy work while running its factories efficiently enough to support that mix. The latest earnings forecast, with strength expected in both High Performance Materials & Components and Advanced Alloys & Solutions, points to that shift remaining in play.
The key short term swing factor is execution on capacity and long term contracts without margin slippage from cost inflation or mix. The biggest risk is that high expectations and leverage collide with softer industrial or medical demand, which could leave earnings more cyclical and the current valuation harder to support.
The naval nuclear contract through 2030 sits closest to this story. Management has a roughly US$1b multi year agreement that more than doubles annual revenue versus the prior deal, helped by price and mix. For ATI, that kind of visibility matters when the market is focused on how durable current margins really are.
This defense work links directly to the catalyst investors are watching. It ties ATI to global defense spending, helps support higher margin work in High Performance Materials & Components, and gives some counterweight if industrial and medical volumes stay uneven. Execution risk does not disappear, but the contract structure and term give the company a clearer runway to plan capacity, capital spending and pricing.
ATI Forecasts and What Needs To Go Right
ATI's current analyst story revolves around a business that could be materially larger and more profitable by the end of the decade, but only if several moving parts line up. Forecasts point to revenues of US$6.3b and earnings of US$1.0b by 2029, paired with an assumed revenue growth rate of 10.1% a year and margin expansion from 10.1% to 16.4% over the next three years.
That earnings path implies a little more than a doubling in profit from about US$475.8m today, which is a sizeable jump for any industrial materials group. Higher contribution from aerospace, defense and specialty energy work would need to do most of the heavy lifting, while industrial and medical customers would at least have to avoid turning into a drag that pulls group returns back toward more cyclical levels.
Analysts are also baking in a richer profitability profile through the cycle, with the business penciled in at a P/E of 41.8x on those 2029 earnings, compared with about 54.3x on current numbers and above the 34.3x multiple cited for the broader US aerospace and defense peer set. The gap suggests the market today is already paying up for ATI's mix, but still expects some compression in the valuation multiple as earnings scale.
Share count assumptions are fairly modest. Forecasts call for the number of shares to rise about 0.23% annually over the next three years, which is small enough that most of the heavy lifting in any per share outcome would still come from how the underlying operations perform rather than dilution.
ATI's narrative projects revenues of US$6.3b and earnings of US$1.0b by 2029, which rests on analysts assuming 10.1% yearly revenue growth and an earnings increase of about US$524m from current earnings of roughly US$475.8m.
Uncover why ATI's fair value indicates a 50% potential upside to its current price, which could narrow quickly.
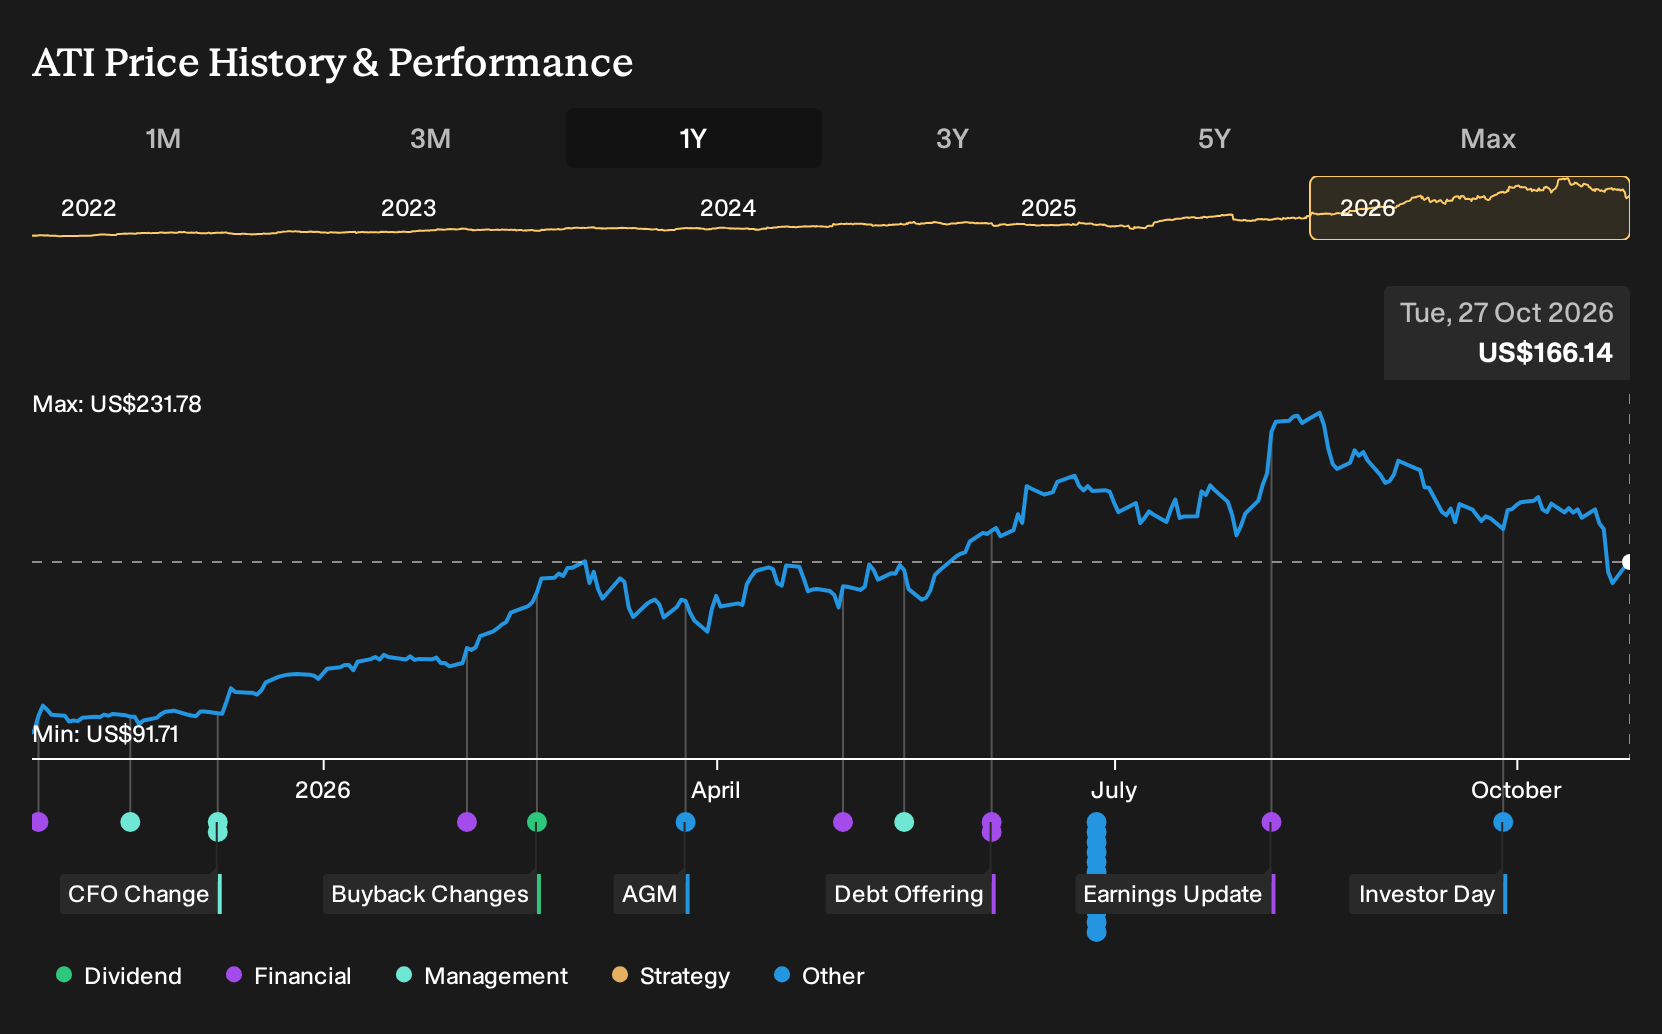
Exploring Other Perspectives
Some of the most optimistic ATI analysts focus on execution risk at the new Mexico facility instead. They were already assuming about US$6.7b of revenue and US$1.3b of earnings by 2029, compared with US$6.3b and US$1.0b for the baseline view. Both sets of forecasts came before this earnings news, so opinions may shift. Be sure to explore several angles yourself.
Explore 4 other ATI fair value estimates, including one that suggests a potential upside of as much as 63% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ATI research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ATI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATI's overall financial health at a glance.
Looking for more ATI investment ideas?
If ATI is already on your radar and you want to round out your watchlist, use the Simply Wall St Screener to surface other businesses with fundamentals that line up with your own risk and return preferences.
- For investors who want potential upside paired with financial quality, scan through our 29 high quality undervalued stocks that already clear a high bar on cash flows and balance sheets.
- If capital preservation sits near the top of your checklist, you can filter for companies with steadier profiles by reviewing the 30 resilient stocks with low risk scores built around lower risk scores.
- When the focus is on strength in the accounts and resilience through the cycle, you can build out a shortlist from the list of solid balance sheet and fundamentals (24 results) to see which businesses match your criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com