
BRP (TSX:DOO) Could Be 18% Undervalued As Growth Plans Face Valuation Doubts
Ski-Doo’s Avalanche Awareness Seminars under BRP (TSX:DOO)'s Responsible Rider program highlight how safety education sits alongside product sales, giving investors another lens on brand strength and risk perception in powersports.
Recent trading paints a mixed picture for BRP. The 1-day share price return of 2.68% and 7-day gain of 6.91% sit against a year-to-date share price decline of 14.54% and a 5-year total shareholder return that is down 21.70%. This suggests that near term momentum has picked up while longer term performance remains weak.
Scan beyond BRP and compare it with a curated list of solid balance sheet and fundamentals (7 results) that could handle industry swings and reputational shocks more resiliently than the average powersports stock.
After a sharp recent bounce yet a year-to-date decline that still weighs on BRP, the real choice is blunt. Do you pay up for the early reversal, or wait for a cheaper shot if the optimism cools?
Most Popular Narrative: 18% Undervalued
BRP last closed at CA$84.19 while the most followed narrative points to a fair value near CA$102.19, so the gap rests on whether its long product cycle and financing push translate into sturdier earnings than the recent share price history suggests.
The rapid expansion of BRP's electric vehicle lineup, including products such as the Outlander electric ATV and electric motorcycle, frames an opportunity for incremental revenue and margin improvement as this portfolio is built out. This may support topline performance and earnings over time. The ongoing international growth focus, with management aiming for roughly US$2.5b of international revenue and continuing to add dealers outside North America, maintains a path for BRP to increase geographic diversification and potentially support revenue levels and earnings resilience.
See why 23 investors see BRP as 18% undervalued.
Result: Fair Value of CA$102.19 (UNDERVALUED)
Still, the narrative around BRP runs into trouble if tariff costs stay heavy, or if weak personal watercraft demand drags harder on volumes and profitability.
Find out about the key risks to this BRP narrative.
Another View on BRP’s Valuation
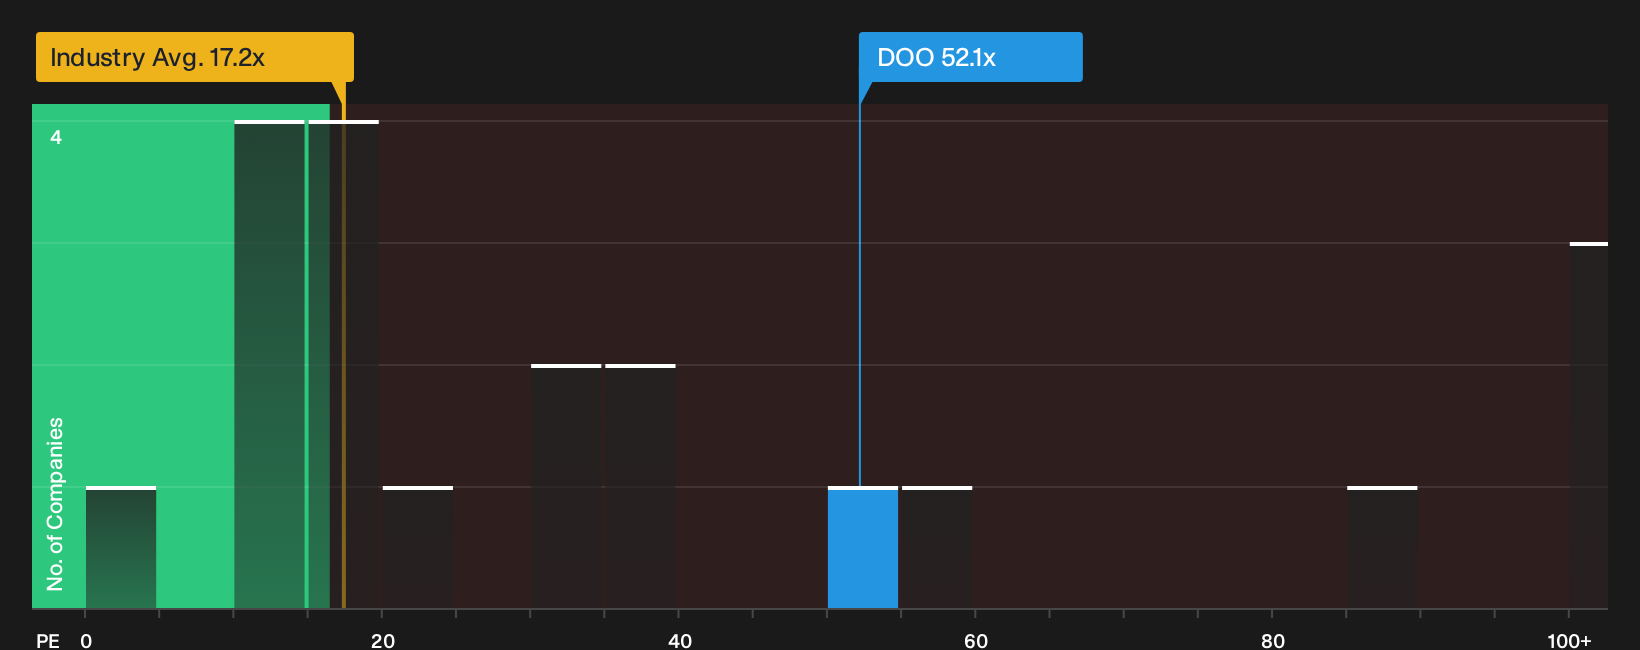
The earlier fair value of CA$102.19 comes from a DCF style narrative around future cash flows and earnings. On a simple earnings multiple, BRP looks very different. The shares trade on a P/E of 52.1x, compared with 35.4x for peers and 17.1x for the wider Global Leisure group, while the fair ratio is 42.9x. That gap points to meaningful valuation risk if sentiment cools or earnings forecasts are revised.
For a closer look at how that P/E gap could matter if markets start favouring cheaper tickers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on BRP’s value and risk profile can pull investors in opposite directions, so move quickly, review the data, and weigh both sides for yourself by checking the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond BRP?
BRP gives you one angle on powersports and valuation tension. Do not stop there when a broader watchlist could sharpen your next move.
- Target strong fundamentals first and hunt for resilient balance sheets through the list of solid balance sheet and fundamentals (7 results).
- Spot potential mispricings quickly by scanning a focused pool of 3 high quality undervalued stocks.
- Prioritise quality that flies under the radar and search for future contenders across 9 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com