
Will Quarterly Earnings Beat Change Konecranes (HLSE:KCR) Narrative
- Konecranes reported third quarter 2026 sales of €1,101.5 million and net income of €119 million, and reiterated 2026 guidance that net sales should stay around or above 2025 levels.
- The earnings report showed higher quarterly sales and net income along with stable earnings per share for the first nine months. This highlights both current demand and cost discipline at Konecranes.
- We will now look at how Konecranes' reiterated 2026 net sales guidance fits into the broader investment narrative around the business.
Compare Konecranes' guidance with peers that also aim for resilient fundamentals and cash generation by scanning our hand picked list of solid balance sheet and fundamentals (207 results).
Konecranes Investment Narrative Recap
For a shareholder in Konecranes, the core belief is that demand for automation, electrified cranes and lifecycle services will keep supporting a solid order book and service revenues, even when industrial and port cycles soften. The reiterated 2026 net sales guidance points to management seeing a broadly steady operating backdrop rather than a sharp inflection, so the near term story is more about execution than big surprises.
The key short term catalyst remains how efficiently Konecranes converts its large backlog and service agreements into reported sales and cash, while keeping working capital in check after recent inventory and net debt pressure. Cyclical exposure to industrial and port customers, plus geopolitical delivery delays, still looks like the dominant risk. The latest guidance does not materially change that balance.
The most relevant disclosure right now is the third quarter 2026 earnings release. Sales of €1,101.5 million and net income of €119 million for the period, together with broadly flat earnings over the first nine months, give you a live read on how Konecranes is handling softer volumes in some areas while still running the business for profitability.
For catalysts, that print helps you judge whether themes like automation demand, a growing service base and eco focused equipment are turning into consistent earnings, or simply offsetting cyclical headwinds and delivery issues. It also lets you track whether earlier concerns around margins, working capital and free cash flow are easing or persisting as you weigh the risk and reward trade off in Konecranes.
Konecranes' current consensus narrative points to revenues of €5.0b and earnings of €553.5 million by 2029, based on analysts assuming 7.0% yearly revenue growth and an earnings increase of about €169.8 million from €383.7 million today.
Uncover why Konecranes' fair value indicates a 32% potential upside to its current price that could narrow quickly.
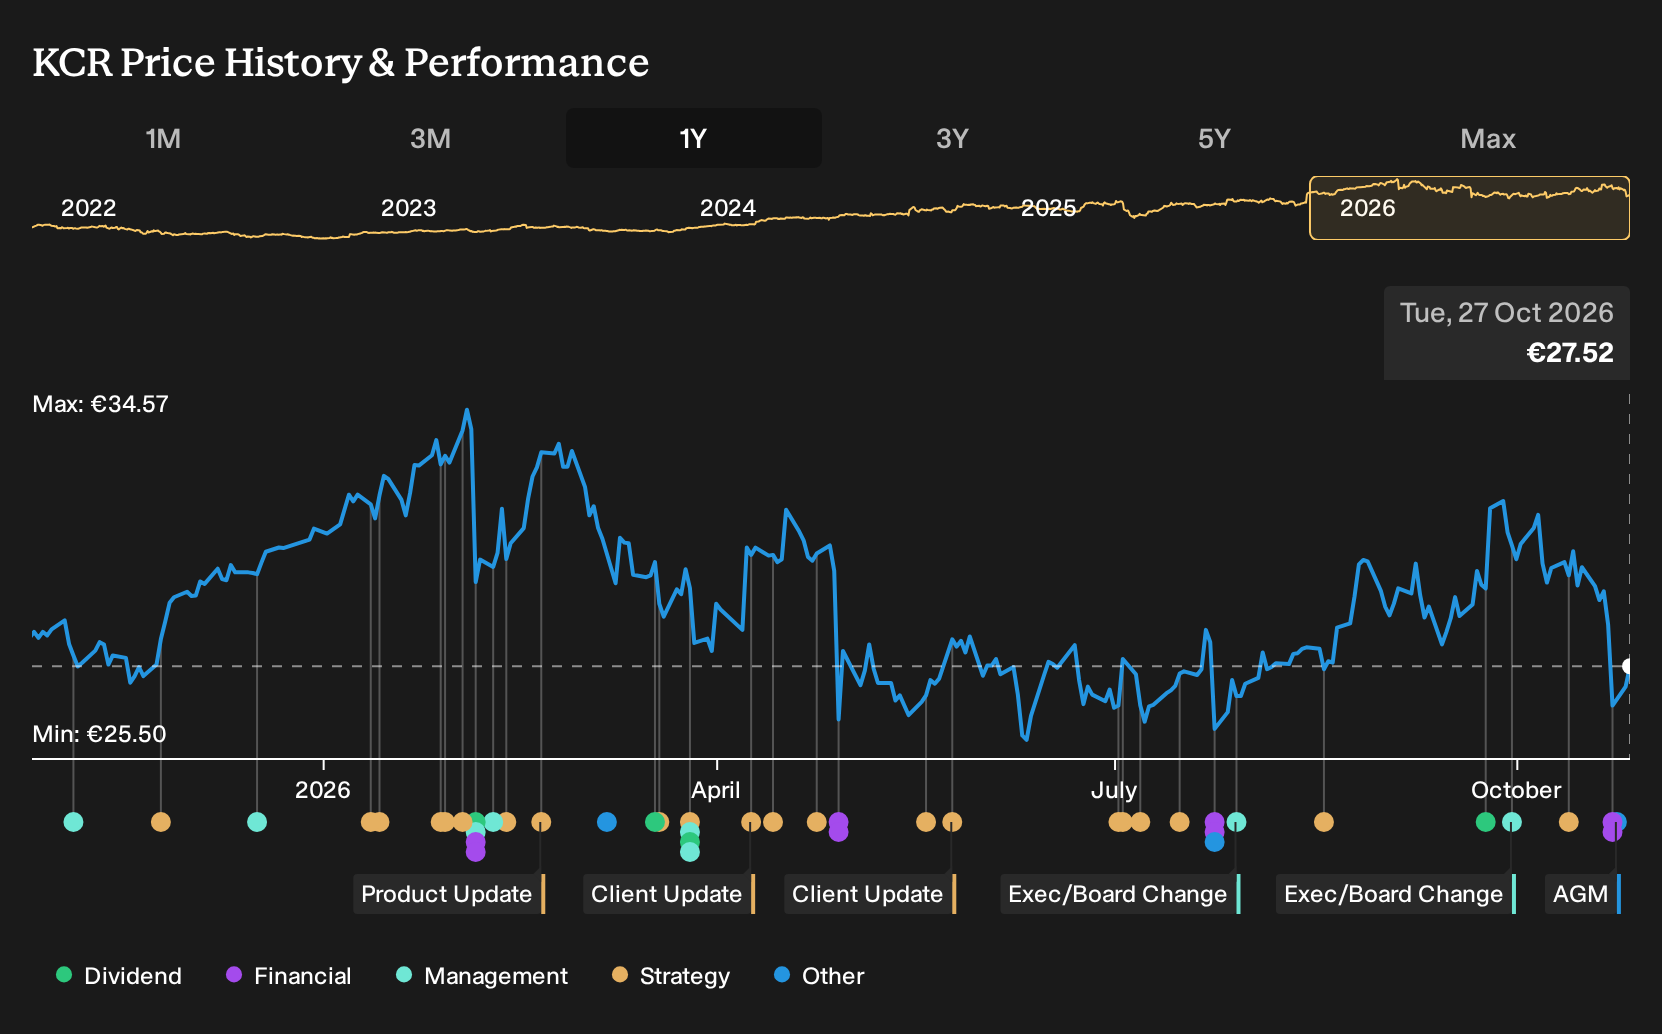
Exploring Other Perspectives
Some of the lowest ranked analysts focus on a different catalyst. They worry that softer service volumes could matter more than Konecranes’ large backlog. Before this guidance update, they were working with roughly €5.1b of 2029 revenue and about €557.6 million of earnings, which is more cautious. These views might shift after the latest numbers, so compare both stories yourself.
Explore 5 other Konecranes fair value estimates, including one that suggests it could be worth just €31.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A useful starting point for your Konecranes research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Konecranes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Konecranes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Konecranes?
If the Konecranes story has sharpened your view on quality, cash generation and risk, it can help to line that up against a wider watchlist built with the Simply Wall St Screener.
- For investors who want potential mispricings with solid fundamentals in focus, scan a curated set of 195 high quality undervalued stocks to see where quality and price may still be out of sync.
- If resilience matters most to you, filter for businesses that score well on debt, liquidity and cash flow using a 223 resilient stocks with low risk scores that keeps drawdown risk in mind.
- Those hunting for under the radar opportunities can sift through a 610 high quality undiscovered gems that highlights companies with strong underlying metrics that are not widely followed yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com