
Dana (DAN) Stock May Sit Below Fair Value On Sales Alone
Dana has delivered a powerful share price run in recent years, which naturally raises a question for anyone looking at the stock today. Is the current market value properly anchored to its sales, or has the price moved ahead of what the top line can justify over time?
- Over the past 3 years the share price has climbed 156.6%, which puts a lot of weight on whether the underlying revenue base can support that kind of rerating.
- The business leans heavily on selling drivetrain and mobility components to original equipment manufacturers. Future valuation will be tied to how consistently those customers translate into sustainable sales and operating scale rather than one off contract wins.
- Your read on Dana is one view; the desks covering it have another. See what analysts think Dana's shares could be worth.
The stock's next move may depend on whether the current price can be reasonably explained by the level and trajectory of Dana's sales.
If you want a wider set of ideas while you weigh Dana's share price against its sales, a focused stock screen is a useful second lens alongside this article. It can be worth checking 29 high quality undervalued stocks.
Is Dana a Bargain on Sales?
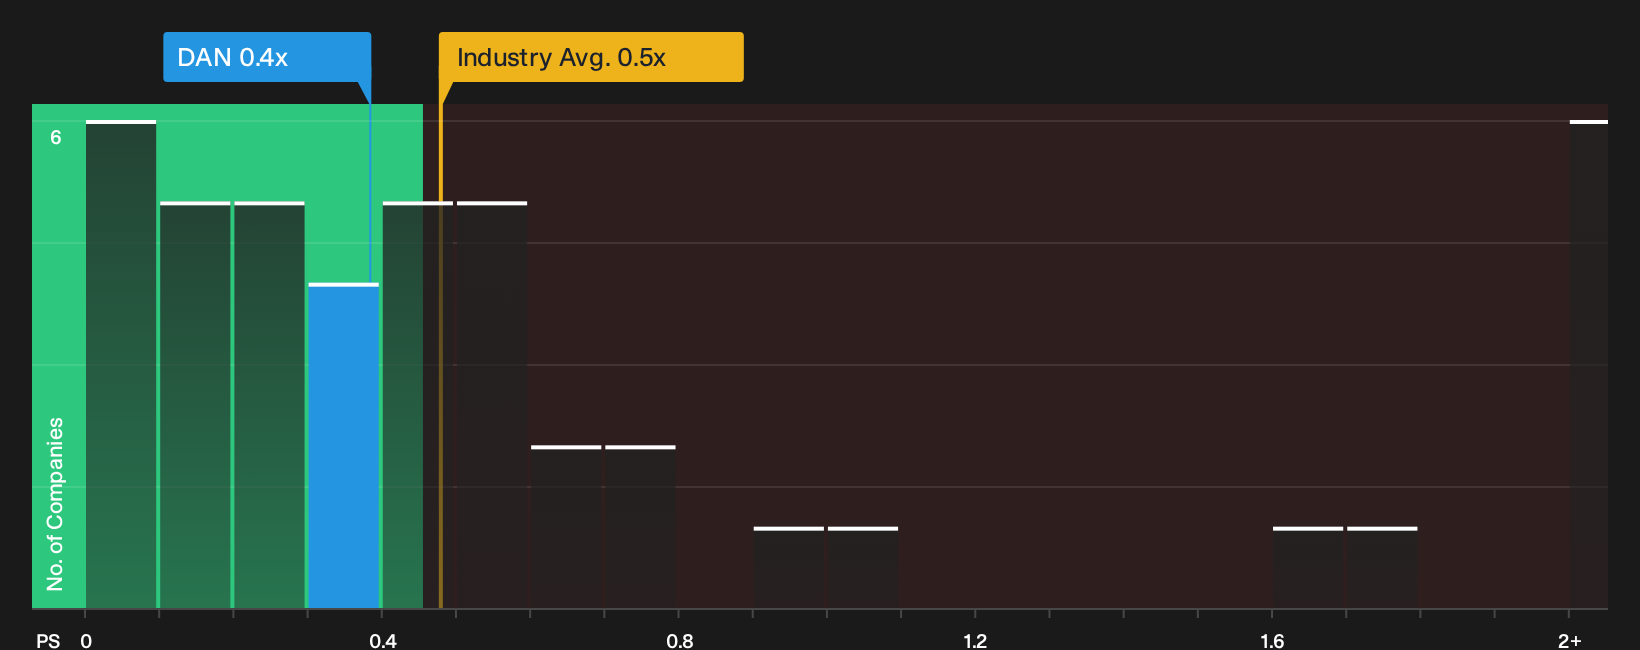
P/S suits Dana because investors are weighing the value of each dollar of sales in a sector where earnings can swing with cycles and contracts. Dana trades on a P/S ratio of 0.4x, using the latest figure provided, which is below both the Auto Components industry average of 0.5x and the peer group at 0.6x. On raw comparisons, the market is assigning a lighter price tag to Dana’s revenue than to many similar businesses.
The fair multiple estimate, which blends factors like growth profile, profitability, market size and risk, also points to a higher P/S than where Dana trades today. That gap suggests the stock is priced at a discount on sales, although the usefulness of that discount depends on how confidently you view the quality and durability of its revenue streams. If you think Dana can keep converting its drivetrain and mobility relationships into steady turnover, the current P/S level may look undemanding enough to warrant a closer look. Explore the numbers behind Dana's P/S valuation.
The Dana Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dana pick up where the valuation puzzle leaves off and explain what kind of future on growth, margins and earnings would need to unfold for the current share price to look either conservative or stretched. Each scenario links a fair value estimate to a specific storyline about Dana's potential catalysts and key risks. This helps you track over time which version of the business is actually taking shape on the Community page.
One of the top community narratives on Dana: 22% undervalued
"Dana is investing around US$325 million of 2026 capital spending to support higher margin backlog and Applied Technologies such as defense and powersports…"
Discover why this Narrative puts Dana at 22% undervalued.
The price of Dana is only one piece of the story
Share charts and P/S ratios describe today, but the next layer is what professional forecasters expect Dana’s revenue and earnings to look like a few years from now. Explore where analysts expect Dana to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com