
3 British Growth Stocks To Watch In October 2026
AI heavyweights like Google, Microsoft and Amazon are now under pressure to justify big AI budgets, and that focus on proven growth is spilling over into UK markets. Investors are paying closer attention to British businesses where insiders already own a meaningful slice and are pushing for expansion. This article walks through three fast growing UK stocks with high insider ownership from our screener so you can see which profiles might fit your watchlist.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where managers have real skin in the game. However, if you want the pick of this theme, these 6 high growth high conviction stocks are the best of the best.
Greencore Group (LSE:GNC)
Overview: Greencore Group manufactures chilled convenience foods such as ready meals, sandwiches, salads and snacks for supermarkets, travel outlets and foodservice customers.
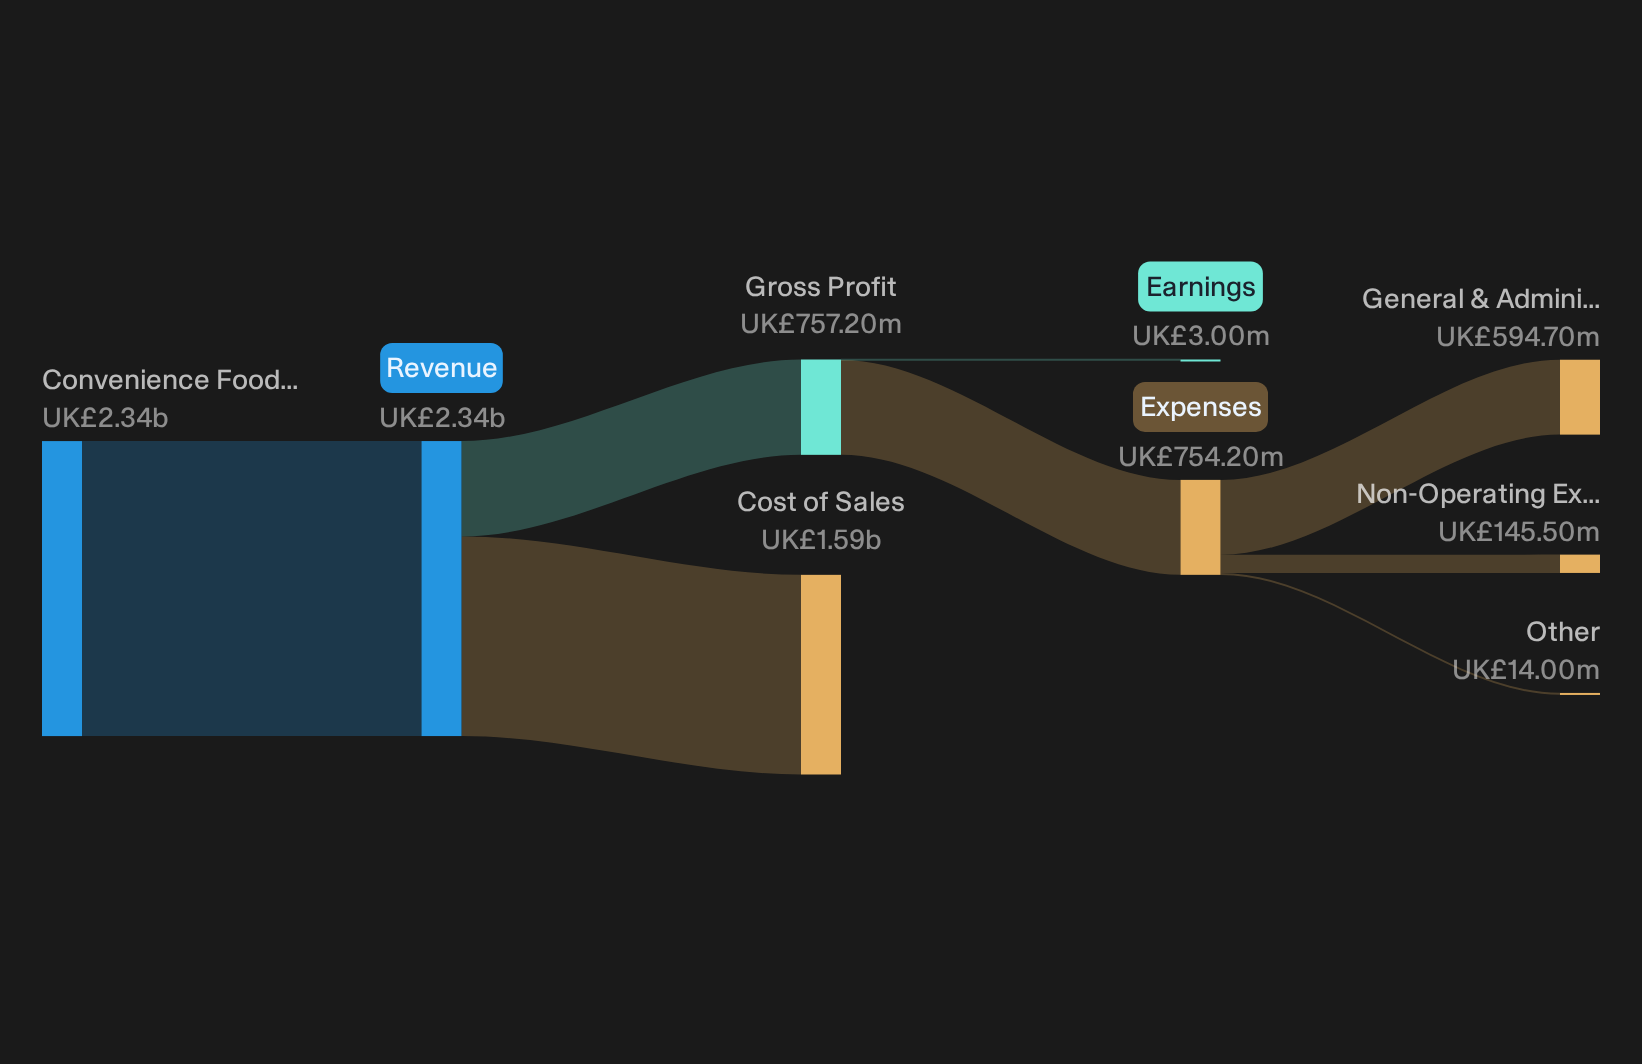
Operations: Greencore generates about £2.3b of revenue from Convenience Foods UK & Ireland, reflecting its focus on chilled and ambient convenience products.
Market Cap: £2.3b
Greencore Group fits this fast growing, high-insider-ownership theme because its chilled convenience ranges tap directly into rising on the go and ready meal consumption, and management is pushing hard to scale that footprint efficiently.
"The targeted £80m of annual cost synergies from the Bakkavor acquisition by January 2029, with specific interim milestones through January 2028, creates further headroom for structural reduction in unit costs that can contribute to higher net margins and operating profit as these benefits phase in."
What really matters now is how one unresolved pressure shapes the balance between volume growth and the profitability investors are counting on.
That trade off between scale and margins is exactly what sits at the heart of the full narrative for Greencore Group, where cost savings, category mix and insider alignment all come into focus.
Softcat (LSE:SCT)
Overview: Softcat helps UK organisations modernise their IT by reselling hardware and software, while also providing higher growth cloud, security and AI focused managed services.
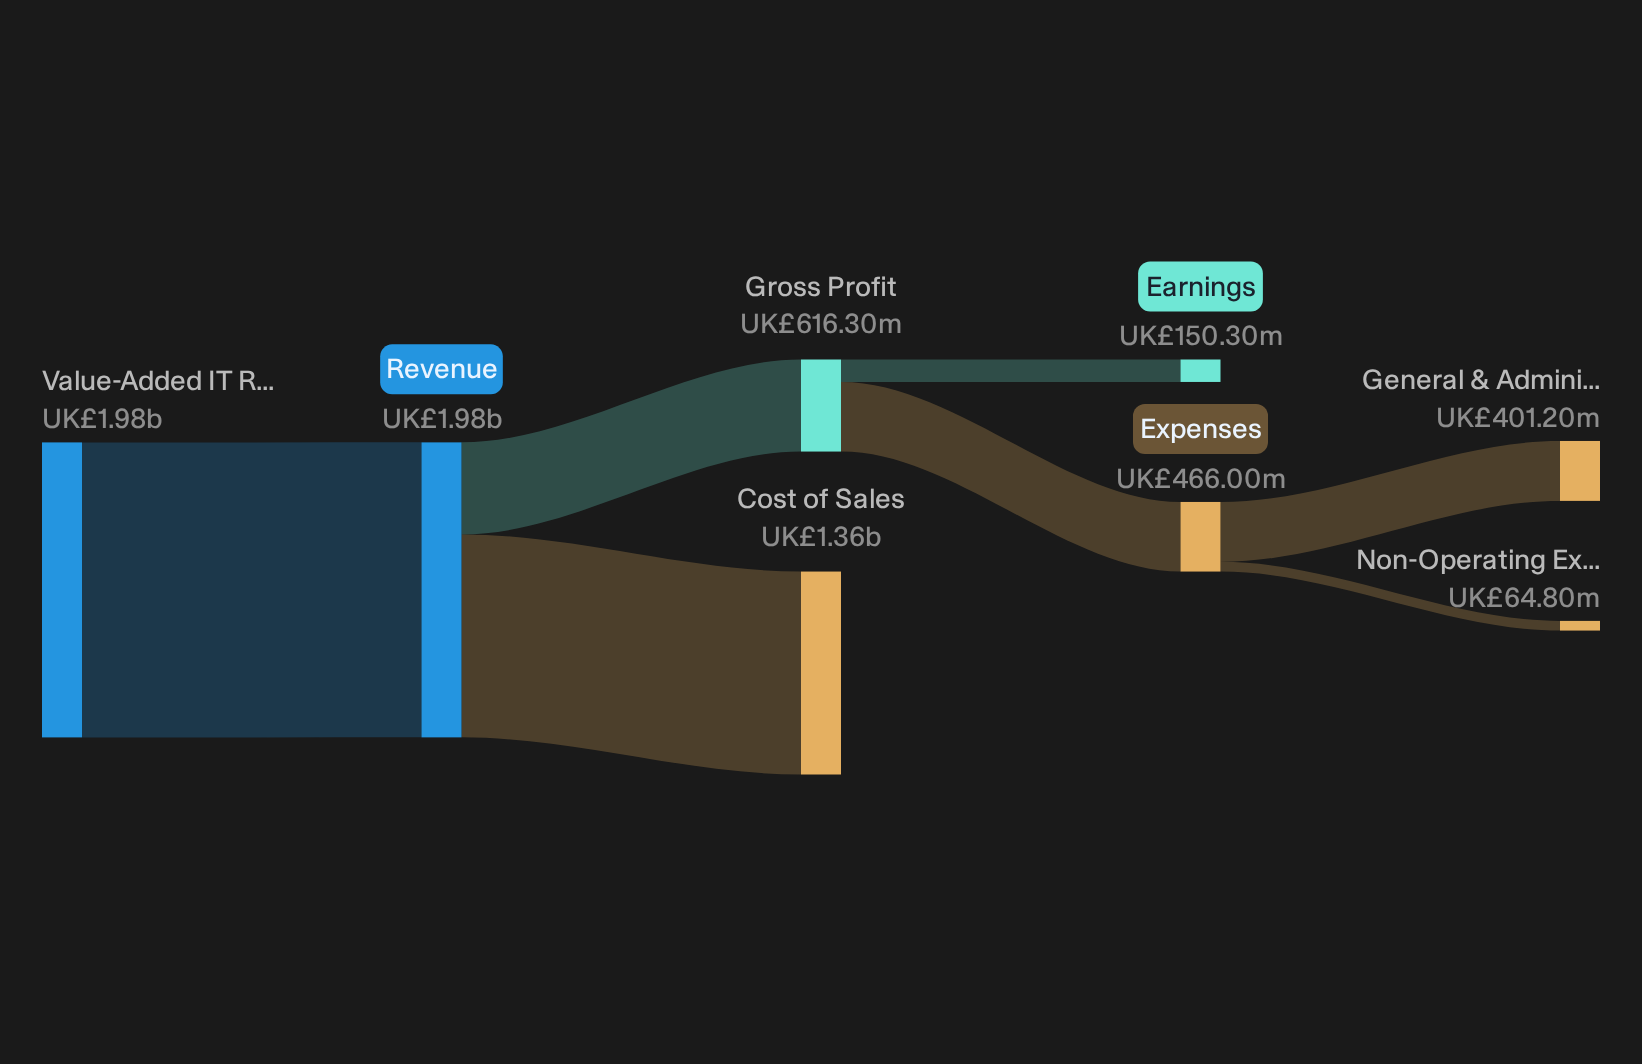
Operations: Softcat generates £2.0b of revenue from value added IT resale and infrastructure solutions, almost entirely from customers in the United Kingdom.
Market Cap: £3.7b
Softcat matters for this fast growing, high-insider-ownership theme because its managed cloud and AI ready infrastructure work is directly tied to customers’ largest technology upgrade budgets.
"Expansion into the US through the planned GDT acquisition, with GDT forecast to contribute about US$240m gross profit and US$80m adjusted EBITDA in calendar 2026, could broaden Softcat’s revenue base and support earnings growth as the combined group gains more exposure to multinational customers."
What investors really need to watch is how any shift in the mix between services and lower margin resale shapes future profitability.
That shifting mix is exactly what the full narrative for Softcat unpacks, showing where Softcat’s growth engine could accelerate and where margins might quietly decouple from topline progress.
TBC Bank Group (LSE:TBCG)
Overview: TBC Bank Group runs a broad banking and financial services platform across Georgia, Uzbekistan and Azerbaijan, with a fast scaling digital retail ecosystem driving much of its growth profile.
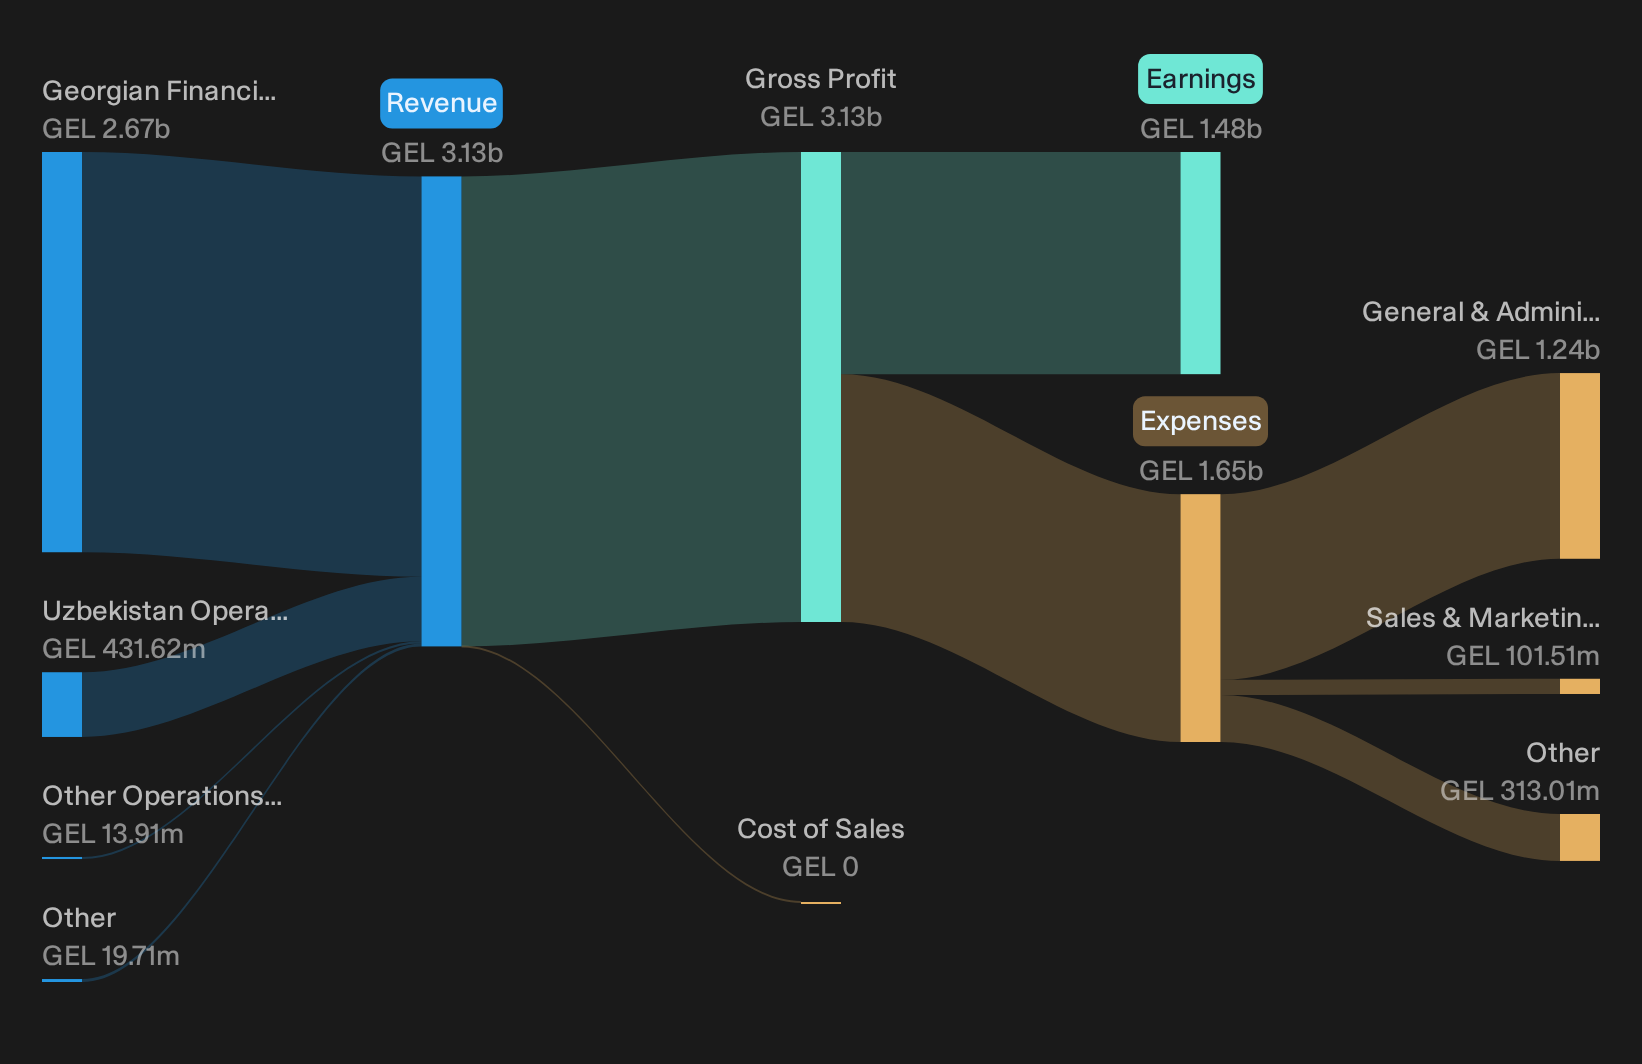
Operations: TBC Bank Group generates about GEL 2.7b from Georgian Financial Services and GEL 432m from Uzbekistan Operations, with minimal contributions elsewhere.
Market Cap: £2.7b
TBC Bank Group plugs into this fast growing, high insider ownership theme through its digital retail banking platform, where mobile led loans, deposits and payments are pulling in users at scale rather than relying only on traditional corporate banking relationships.
"The ongoing shift in Uzbekistan from a loan book dominated by unsecured cash loans toward business loans, credit cards, auto loans and secured SME lending is expected to diversify revenue streams and support a more balanced net interest margin over time."
What really moves the needle for TBC Bank Group now is how one unseen pressure shapes the balance between rapid digital expansion and long term asset quality.
That unseen pressure is exactly what the full narrative for TBC Bank Group unpacks, showing where rapid digital growth could be accelerating returns or quietly masking brewing asset quality risk.
Seeking Fresh Alternatives Before They Fly
New breakout stories rarely stay quiet for long. Momentum builds, prices move, and the best entry points get caught and disappear. Scan these fresh ideas before the crowd and consider them early.
- Spot resilient compounding stories before they get crowded by screening for 4 resilient stocks with low risk scores that aim to keep downside in check while upside momentum is still building.
- Hunt for under the radar potential in metals by reviewing 16 top copper producer stocks that could benefit if demand pressure returns while valuations are still grounded.
- Track income engines that aim to keep cash flows coming by focusing on 5 dividend fortresses designed to prioritise yield alongside balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com