
Is Ogaki Kyoritsu Bank (TSE:8361) Overvalued After Premium Valuation Scrutiny Intensified?
Fresh scrutiny on Ogaki Kyoritsu Bank (TSE:8361) has been sparked by its premium valuation versus regional peers, putting profit resilience, return on equity, and the relationship between earnings and the current share price under closer examination.
Recent price action around Ogaki Kyoritsu Bank has been choppy, with a 1-day share price return of 2.30% after a 30-day share price decline of 11.99%. However, the year-to-date share price return of 58.61% and 1-year total shareholder return of 117.37% indicate momentum that has built over a longer stretch and now feeds directly into the debate about whether its premium valuation still matches underlying fundamentals.
Compare Ogaki Kyoritsu Bank's premium valuation with a curated 16 high quality undervalued stocks list that features companies pairing solid balance sheets with cash generation that the market may be underpricing.
Ogaki Kyoritsu Bank looks like a robust regional lender, yet the share price has raced far ahead of many peers. Are you now paying too much for that strength, or is the premium still fair value?
Price-to-Earnings of 15.2x: Is it justified?
Ogaki Kyoritsu Bank trades on a P/E of 15.2x, which sits above both its closest peers at 13.6x and the wider JP Banks industry at 14x. With the last close at ¥1,556 and a long run of strong share price returns behind it, that richer earnings tag places the current valuation firmly in premium territory.
The P/E ratio simply tells you how much investors are paying today for each unit of earnings. For a regional lender such as Ogaki Kyoritsu Bank, that multiple often reflects views on the durability of profits, the quality of its loan book, and how dependable the dividend stream feels through a full credit cycle.
Here, earnings have grown 20.7% per year over the past 5 years and 33.6% over the past year, which shows profit momentum. At the same time, Return on Equity sits at 5%, net profit margins have edged down from 13% to 12.9%, bad loans are high at 12%, and the allowance for those bad loans is low at 4%. The mix of brisk profit growth with modest profitability metrics and elevated credit risk suggests the market is paying up for the growth record while overlooking some balance sheet pressure.
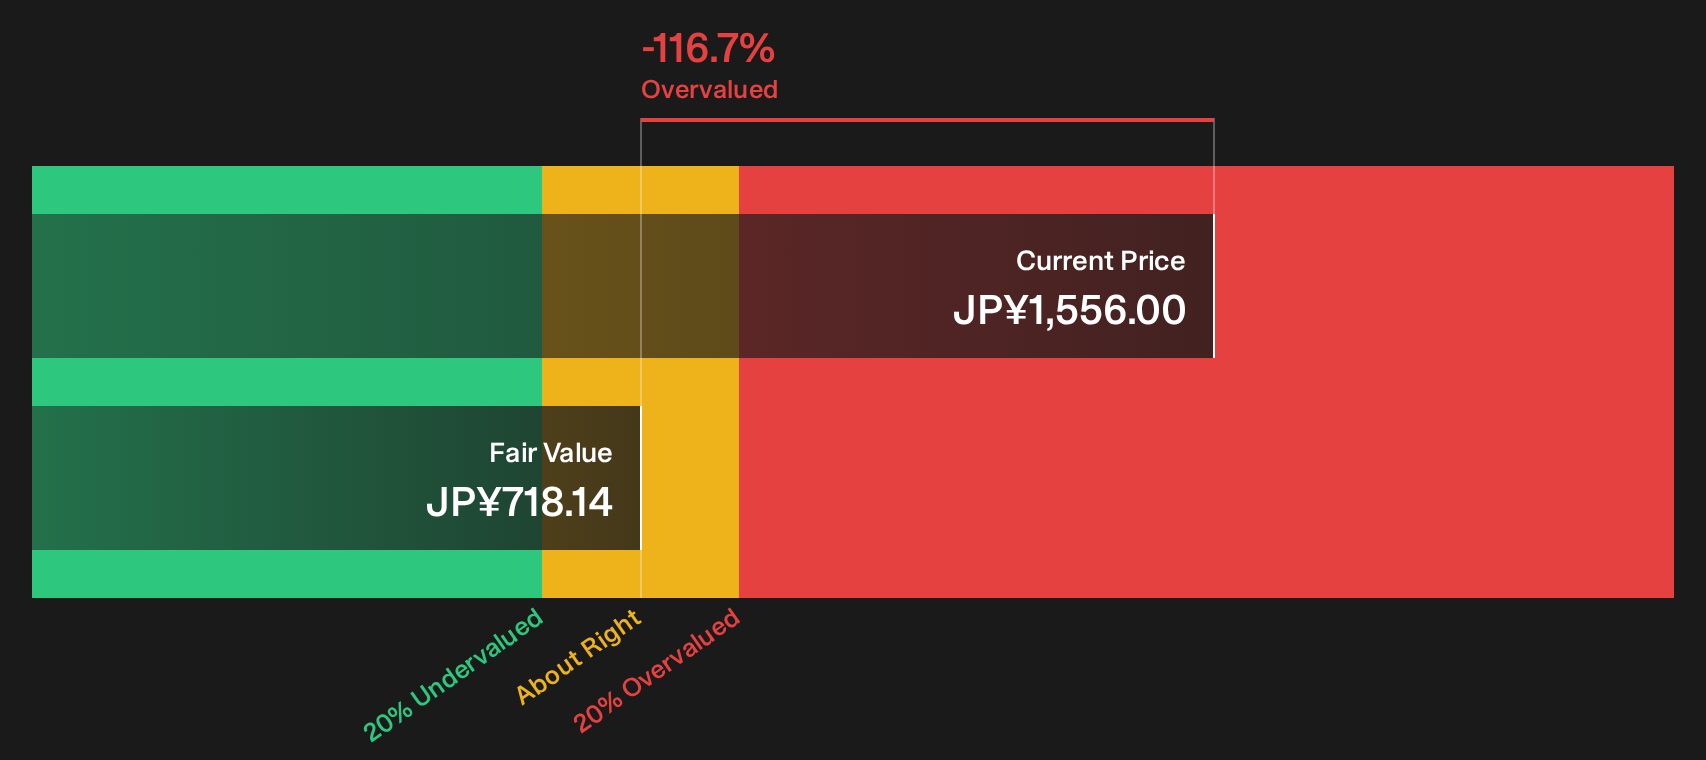
Compared with both the immediate peer group on 13.6x and the JP Banks sector on 14x, Ogaki Kyoritsu Bank carries a clearly more expensive P/E multiple. That stronger pricing implies investors are assigning a premium relative to comparable banks despite the stock already trading above the SWS DCF model estimate of future cash flow value at ¥718.14.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 15.2x (OVERVALUED)
Still, the picture can change quickly if Ogaki Kyoritsu Bank faces rising credit losses on its 12% bad loans or pressure on its already modest 5% Return on Equity.
Find out about the key risks to this Ogaki Kyoritsu Bank narrative.
Another View: What the SWS DCF Model Says About Ogaki Kyoritsu Bank
While the P/E points to Ogaki Kyoritsu Bank trading rich against peers, the SWS DCF model is even more blunt. With the share price at ¥1,556 versus an estimated future cash flow value of ¥718.14, the framework flags the stock as overvalued on a cash generation basis.
That gap raises a practical question for you as an investor. Is the market already pricing in years of strong execution that the DCF model does not capture, or is this a signal to treat the current share price as fragile rather than comfortable value territory?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ogaki Kyoritsu Bank for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment this mixed around Ogaki Kyoritsu Bank, do not wait for consensus to form. Weigh the valuation, stress test the balance sheet, and then benchmark your view against the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ogaki Kyoritsu Bank?
If Ogaki Kyoritsu Bank leaves you questioning the next move, use this moment to widen your opportunity set before the market moves on without you.
- Spot potential mispricings early by scanning a curated 16 high quality undervalued stocks that highlights businesses with quality fundamentals priced as if they have been overlooked.
- Strengthen your downside protection by reviewing a list of solid balance sheet and fundamentals (23 results) that focuses on companies with sturdier finances backing their operations.
- Hunt for potential standouts by checking a 72 high quality undiscovered gems that filters for quality enterprises still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com