
Can Kawasaki Kisen Kaisha (TSE:9107) Justify Its Price Following Raised Earnings Guidance?
Raised earnings guidance has put Kawasaki Kisen Kaisha (TSE:9107) back in focus after management updated forecasts for the September 2026 quarter and the March 2027 fiscal year.
The raised guidance lands after a strong run in Kawasaki Kisen Kaisha’s shares, with a 90 day share price return of 19.34% and a year to date share price gain of 56.83%, while the 1 year total shareholder return of 62.28% and 5 year total shareholder return of roughly 7x suggest longer term holders have already seen substantial upside. This indicates momentum has been building rather than fading, even as the stock recently eased 1.44% on the day to ¥3,415.
Scan beyond Kawasaki Kisen Kaisha and spot other transport and infrastructure plays with momentum and balance sheet support using our curated list of solid balance sheet and fundamentals (23 results) as a starting universe.
Kawasaki Kisen Kaisha now pairs upgraded earnings guidance with a share price that has already moved hard. Strong operator, yes. But are you paying up for that quality, or still getting it at a reasonable valuation?
Most Popular Narrative: 16% Overvalued
The most followed valuation narrative pegs Kawasaki Kisen Kaisha’s fair value at ¥2,952, which sits below the last close of ¥3,415 and frames the upgraded guidance against concerns that expectations might already be stretched.
The company faces significant headwinds from the ongoing movement toward regional supply chains and onshoring, with U.S. tariff policies expected to cause at least a 30% decline in car carrier volumes to the U.S. and materially reduce containership demand on U.S. routes, likely resulting in declining revenues and heightened earnings volatility. There is a sector-wide risk of overcapacity due to aggressive delivery of new vessels, particularly in the containership segment, which is already contributing to declining short-term freight rates and is likely to further compress margins and depress earnings.
See why 2 investors see Kawasaki Kisen Kaisha as 16% overvalued.
Result: Fair Value of ¥2,952 (OVERVALUED)
Still, Kawasaki Kisen Kaisha’s high equity ratio and long term energy transport contracts could cushion any earnings wobble and challenge the overvaluation narrative.
Find out about the key risks to this Kawasaki Kisen Kaisha narrative.
Another View: Cash Flows Point To Undervaluation
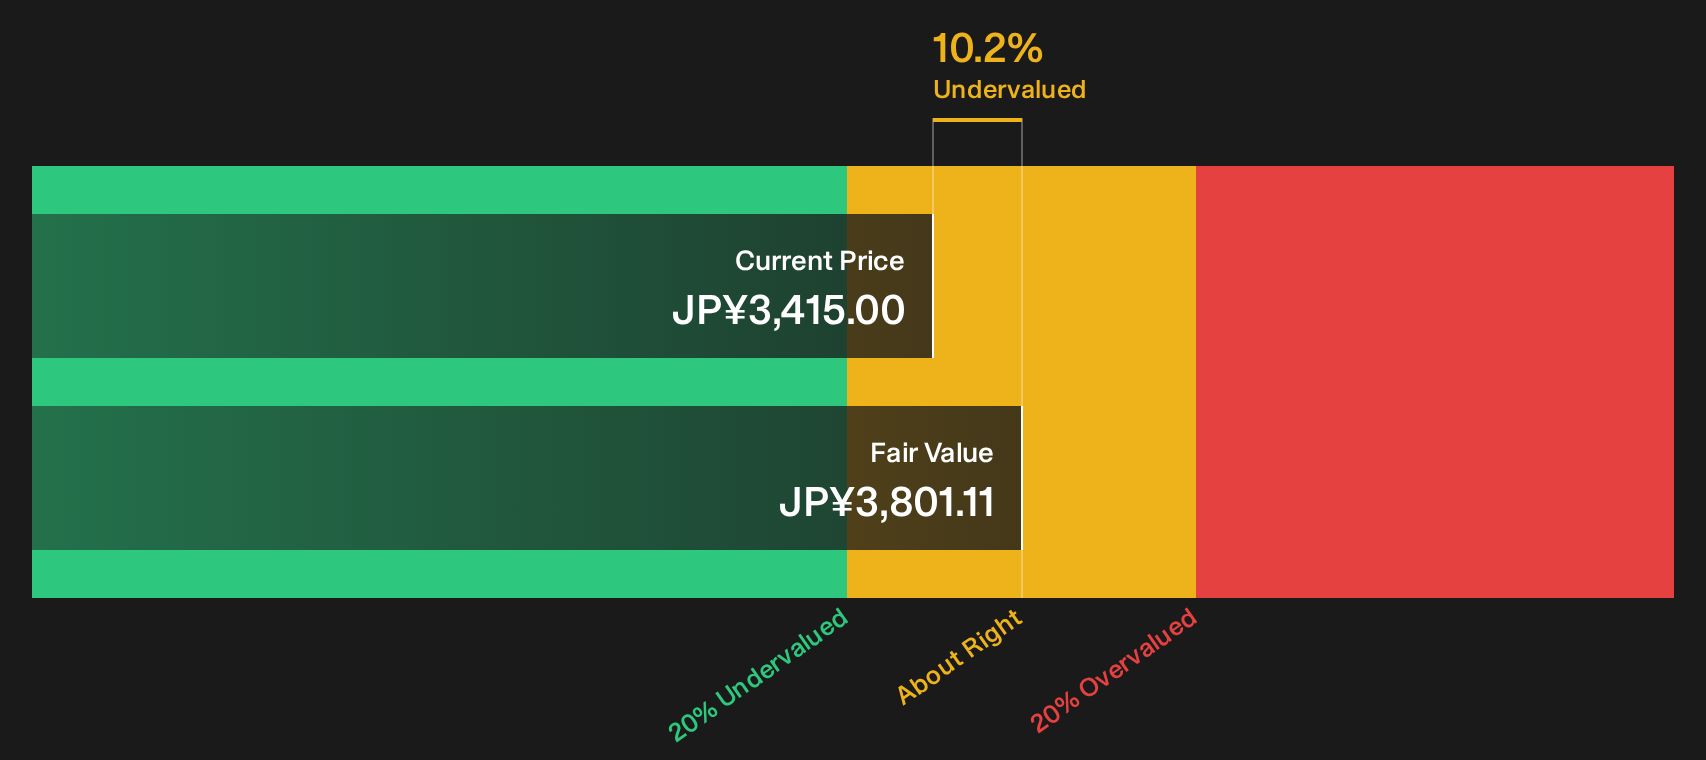
Price based narratives describe Kawasaki Kisen Kaisha as roughly 16% overvalued at ¥2,952, yet the SWS DCF model presents a different perspective. On projected cash flows it lands at ¥3,801, about 10.2% above the current ¥3,415 level. Which lens do you rely on more: sentiment or cash generation potential?
To see how this cash flow view is built step by step, use the Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kawasaki Kisen Kaisha for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Kawasaki Kisen Kaisha story so far. Act while sentiment is shifting and weigh the upside against the red flags yourself with 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Kawasaki Kisen Kaisha?
Do not stop your research with one stock. Broaden your watchlist using focused shortlists that group companies by quality, value, and risk profile.
- Target potential bargains with solid fundamentals by scanning the 16 high quality undervalued stocks before prices move away from you.
- Prioritise resilience in tougher markets by reviewing the 22 resilient stocks with low risk scores so you are not relying on a single high beta bet.
- Spot early opportunities with strong numbers by checking the 72 high quality undiscovered gems before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com