
What StoneCo (STNE)'s Brazil Election Shock Means For Shareholders
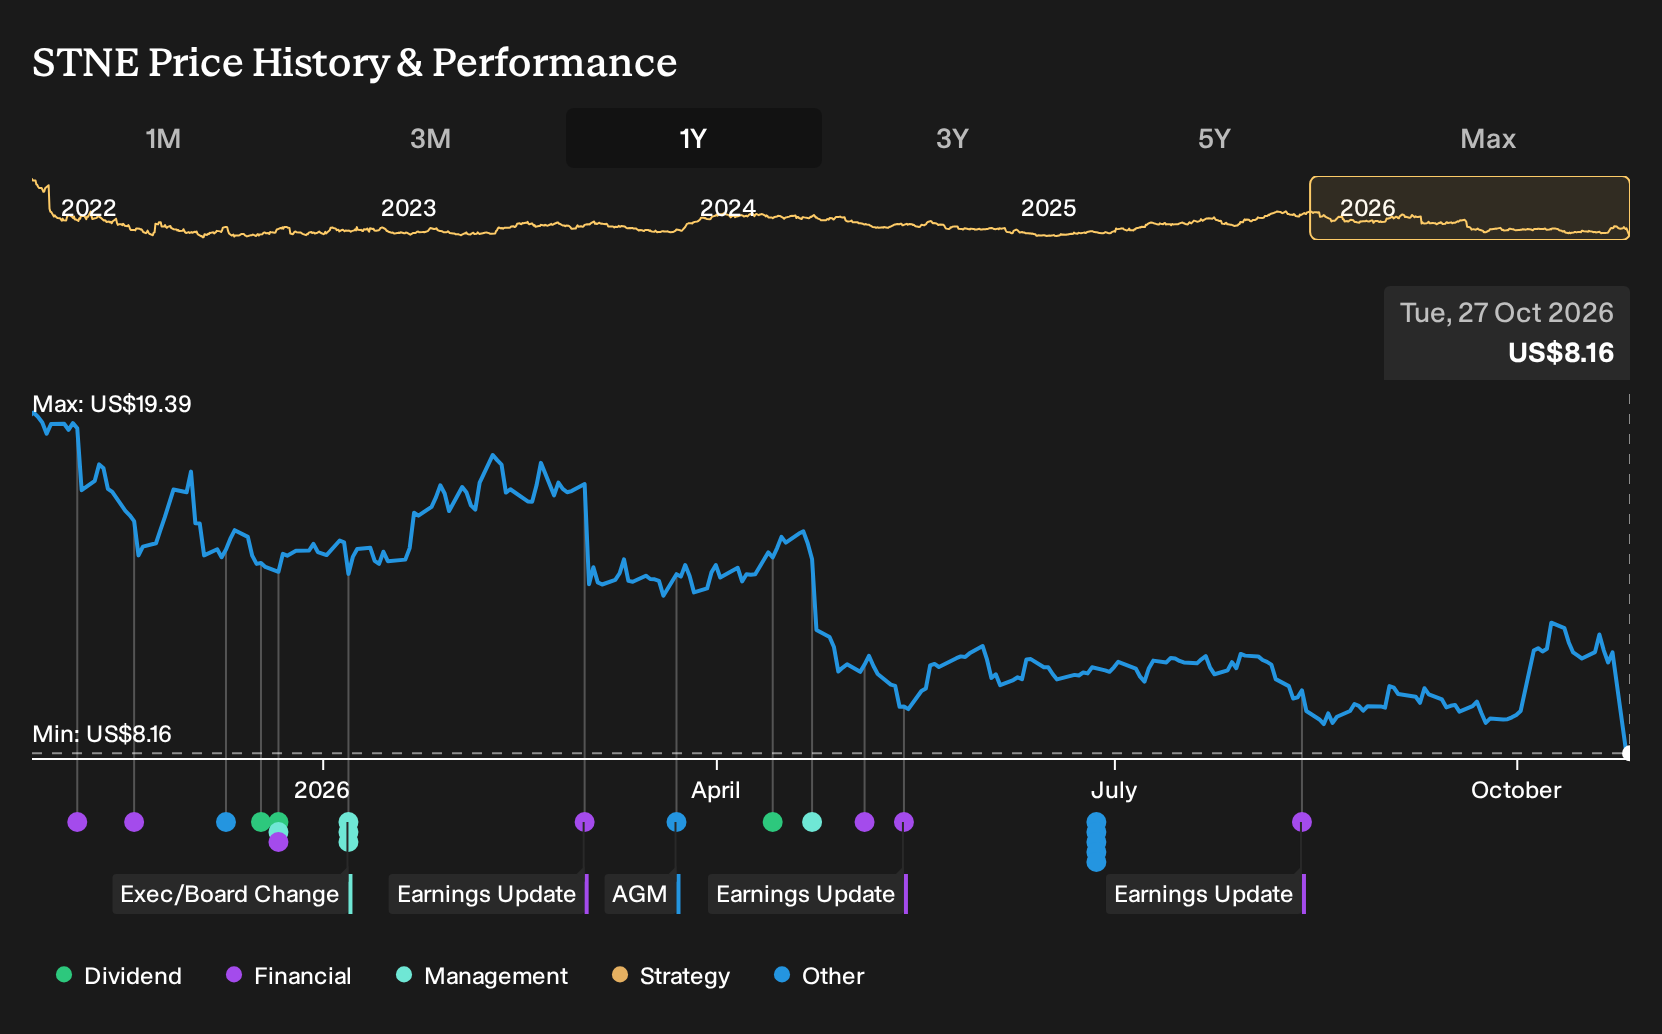
- StoneCo has faced a sharp share price decline over the past week after Brazil’s presidential election outcome prompted a broad selloff in local financial technology and payment companies.
- The political shock has not been matched by new information on StoneCo’s operations. Investor focus remains squarely on how resilient its banking and credit transition proves to be under a less market friendly policy backdrop.
- We will now look at how StoneCo’s investment narrative is tested by Brazil’s election upset and the resulting spike in political uncertainty.
Scan how other Brazilian financials are reacting to the same political shock, and spot which ones still show resilient balance sheets and cash flows using our curated list of solid balance sheet and fundamentals (24 results).
StoneCo Investment Narrative Recap
To own StoneCo, you need to believe its shift toward being a full-service financial partner for Brazilian merchants, with payments, banking and credit in one account, can stay intact even when politics turn noisy. The recent election shock hit the share price hard, but there is no fresh data yet that changes how deposits, loan growth or merchant activity are trending.
The most important short term catalyst is the 12 November 2026 earnings release, because it should show how credit quality, funding costs and Total Payment Volume are holding up. The biggest current risk remains credit losses and funding pressure, especially if small merchant stress and weak brick and mortar activity persist.
With no major company announcements since the election, the upcoming quarterly report is effectively the key event tied to this selloff. StoneCo is expected to report earnings per share of US$0.49 on revenue of US$715.07 million. That is where you will see whether political worries are feeding through into slower client activity, weaker fee income or higher cost of risk.
This update also matters for how investors read the balance between rewards and risks. Earnings grew 54% over the past year and net profit margins are currently 25.7%. However, forecasts point to declining profits and interest costs that are not well covered by earnings. How management talks about deposit growth, credit composition and funding mix on that call will help you judge whether the recent price fall lines up with the operational picture.
StoneCo’s current analyst playbook points to revenues of R$17.2b and earnings of R$2.8b by 2029, based on forecast revenue growth of 8.2% a year and a decline in earnings from R$3.5b today, which amounts to a R$0.7b drop in profit over that period.
Discover how StoneCo's fair value indicates an 82% potential upside to its current price that could close faster than many expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on one thing you might view very differently after the election shock. They lean on StoneCo’s earnings potential, with bullish forecasts around R$20.0b in revenue and R$3.6b in earnings by 2029, while the lowest estimates sit near R$2.0b. These views were all formed before this political jolt, so use them as starting points and explore how you think they might shift now.
Explore 4 other StoneCo fair value estimates, including one that suggests as much as 535% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your StoneCo research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for StoneCo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StoneCo's overall financial health at a glance.
Looking For More Ideas Beyond StoneCo?
If this election driven reset around StoneCo has you rethinking concentration risk, it can help to line it up against a wider field of potential opportunities that share the financial traits you care about most.
- If capital protection sits high on your list, scan a curated set of resilient businesses through the 30 resilient stocks with low risk scores.
- If you prefer income on top of price moves, filter for companies offering robust payouts using the 5 dividend fortresses.
- If you like the thrill of smaller stocks but still want solid fundamentals, focus your search with the 7 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com