
Is Knife River (KNF) Undervalued As Starboard Pushes For Board Seats And Margin Gains?
Starboard Value has escalated its campaign at Knife River (KNF), saying it plans to nominate directors after urging the construction materials group to lift profit margins or consider selling the business.
Knife River’s latest share price of US$54.83 comes after a 3.63% 1 day share price gain and a 7.13% 7 day share price return. Momentum has cooled over the past quarter, with the 90 day share price return down 28.06% and the 1 year total shareholder return down 10.32%. Even so, the 3 year total shareholder return of 8.96% points to a more resilient longer term picture as activists now push harder on margins and capital decisions.
Contrast Knife River’s activist pressure with hand picked infrastructure peers by scanning 42 power grid technology and infrastructure stocks, which could also be in the spotlight as capital and boardroom decisions come under scrutiny.
Knife River has slipped over the past year even as Starboard turns up the heat on margins. At this share price and under activist pressure, does the risk-reward still lean toward buyers or caution?
Most Popular Narrative: 27% Undervalued
Knife River’s most followed narrative pegs fair value at $75.13, well above the latest close at $54.83. This puts the activist push squarely against a valuation backdrop that already assumes improvement in margins and execution.
Companywide self-help programs such as EDGE and PIT Crew, together with dynamic pricing and process changes that have already lowered per-unit production costs and supported mid single digit aggregate pricing, are set up to further lift gross margins and adjusted EBITDA even as diesel and delivery costs remain a headwind.
See why 7 investors see Knife River as 27% undervalued.
Result: Fair Value of $75.13 (UNDERVALUED)
Still, the KNF story can crack if higher diesel costs keep eroding project economics, or if delays in key states like Oregon persist and weigh on margins.
Find out about the key risks to this Knife River narrative.
Another View: Knife River Looks Expensive On Earnings
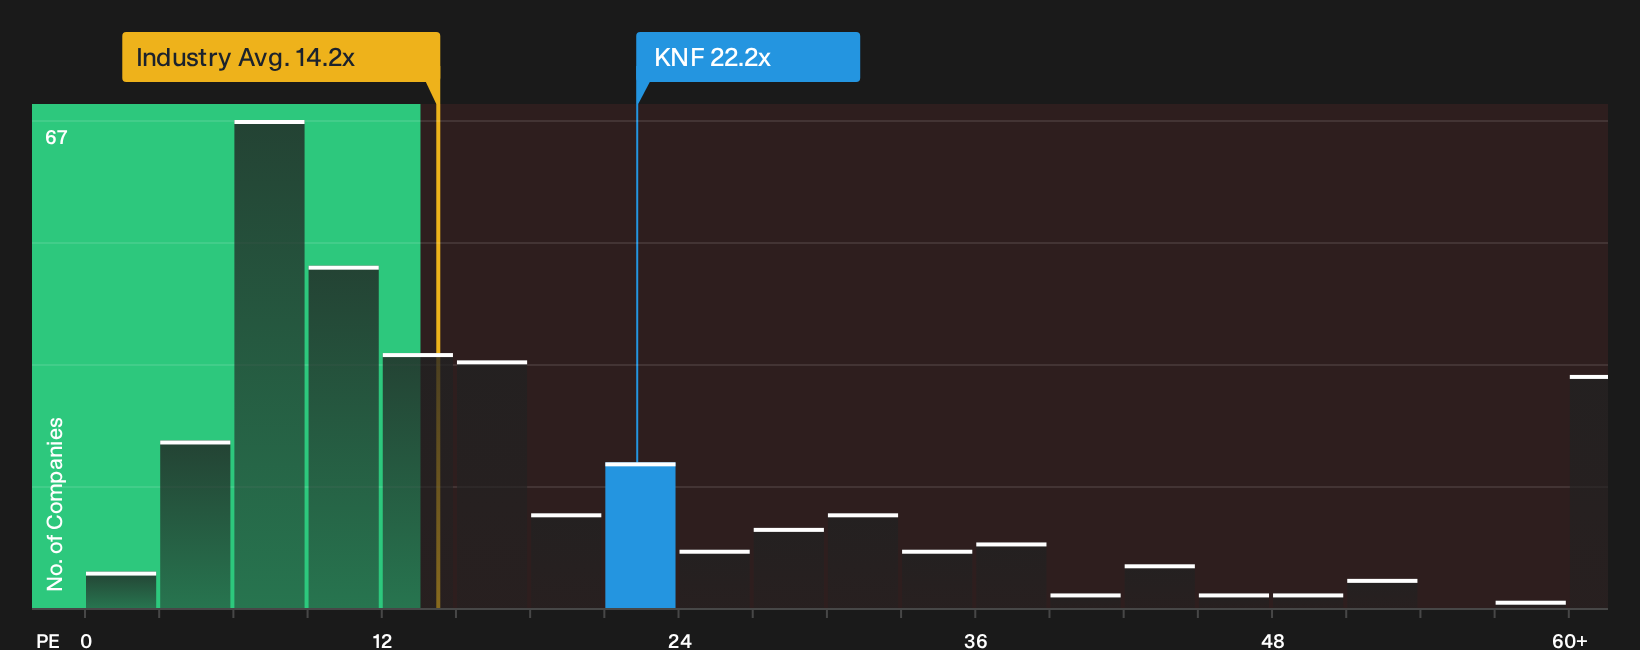
While the prevailing Knife River narrative leans on a fair value of $75.13, the earnings based view points in the opposite direction. At a P/E of 22.2x, KNF trades above both the Global Basic Materials average of 14.3x and an estimated fair ratio of 18x, which raises clear valuation risk questions.
Put simply, the stock already prices in richer expectations than peers and that fair ratio suggests. The gap can close in either direction, so investors need to decide whether the current premium feels earned or exposed to disappointment. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Knife River is clearly split, with activists pushing hard while valuation signals point in different directions. Read the numbers yourself and move quickly to form your own stance using 1 key reward and 1 important warning sign
Looking For More Investment Ideas Beyond Knife River?
Knife River may be front of mind today, but your next strong idea could be sitting just a few clicks away inside a focused screener built around what matters to you.
- Target potential mispricings by scanning a curated pool of quality candidates through 29 high quality undervalued stocks that keep fundamentals front and center.
- Strengthen your defensives by focusing on balance sheet resilience with the list of solid balance sheet and fundamentals (24 results) so weak finances do not quietly undercut your thesis.
- Boost your income focus by hunting for payout potential with 5 dividend fortresses before the market reacts and reprices the yield story.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com