
Did Major Project Wins Just Shift Fluor's (FLR) Investment Narrative?
- Fluor has recently been linked to a series of large contract opportunities, including LNG Canada Phase 2 and multiple data center and uranium enrichment projects, which are expected to support earnings through stronger bookings and an expanded pipeline of reimbursable work.
- Management's plan to repurchase about US$1.4b of stock in 2026 highlights a capital return focus that could influence Fluor's earnings per share and align with its asset light contracting approach.
- This article examines how Fluor's investment narrative is affected by stronger bookings momentum and the planned US$1.4b share repurchase program.
Scan how Fluor's contract pipeline compares with peers by running through the hand picked 42 power grid technology and infrastructure stocks tied to major infrastructure and energy transition build outs.
Fluor Investment Narrative Recap
To own Fluor, you need to be comfortable with a project driven business that is still unprofitable today, yet working through a large backlog and prospect list across LNG, data infrastructure, mining and nuclear related work. The near term story leans on converting that prospect pipeline into reimbursable or disciplined lump sum contracts without repeating past problem jobs.
The key short term catalyst is bookings momentum turning into higher quality earnings as the asset light model scales and cash generation targets are tested. The biggest risk remains execution issues and guidance resets, especially where foreign exchange or productivity on lump sum work can still pressure margins and keep earnings volatile.
The most relevant development is Fluor targeting about US$1.4b of share repurchases in 2026, funded in part by more than US$2.4b of past divestiture proceeds. That plan intersects directly with the operational story because it relies on Fluor hitting its updated adjusted operating cash flow guidance of US$300 million to US$320 million and managing project risk tightly.
For you as a shareholder, this capital return plan can amplify any improvement in earnings per share if bookings, such as LNG Canada Phase 2 and data center or uranium enrichment work, convert into revenue at the margins management is aiming for. It also increases the stakes around project delivery, because any fresh charges, foreign exchange hits or guidance cuts could limit flexibility to execute that US$1.4b buyback on the timetable management has laid out.
Fluor Consensus Assumptions and Valuation Set Up
Fluor's narrative projects US$19.7b revenue and US$497.9 million earnings by 2029. This is tied to analysts penciling in 8.3% yearly revenue growth and an earnings swing of about US$2.5b from a loss of US$2.0b today to those forecast profits.
The consensus framework that analysts are using links the contract pipeline directly to a recovery story in the income statement. Forecast revenue growth of 8.3% a year over the next three years, combined with a move in profit margins from a loss of 12.8% today to a 2.5% margin in three years, is what underpins the long term earnings bridge for Fluor.
On the earnings line, the jump from a loss of US$2.0b today to forecast earnings of US$497.9 million by 2029 is substantial. That change is also where the planned shrink in share count, with analysts expecting outstanding shares to fall about 7.0% a year over the next three years, becomes important for per share metrics and for the planned US$1.4b buyback to have meaningful impact.
Valuation work in the stock research ties these operating assumptions to a 2029 snapshot. To line up with the consensus price target, you would need to assume Fluor reaches US$19.7b of revenue, delivers US$497.9 million of earnings in 2029 and trades on a P/E of 17.4x on those earnings, compared with a current implied P/E of 3.3x loss based.
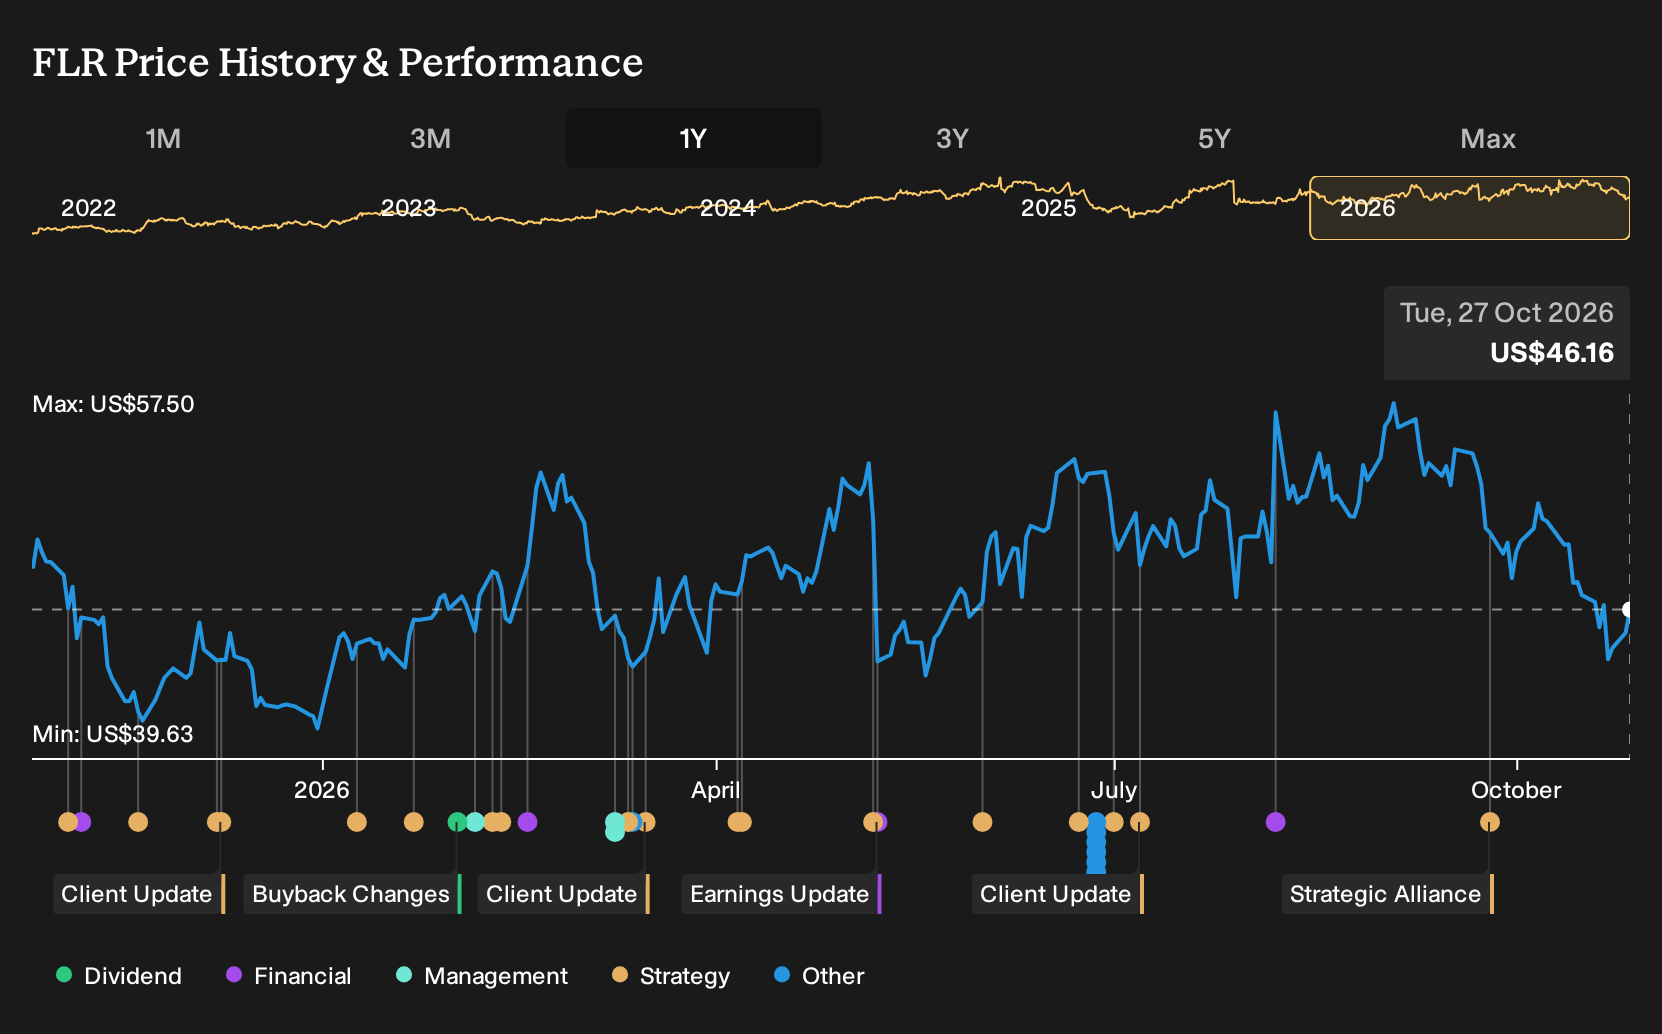
That framework is packaged into a US$61.69 analyst target price compared with a current share price of US$49.33. The spread reflects the view that the contract mix shift toward reimbursable work, use of more than US$2.4b of divestiture proceeds and cash generation targets together justify a higher multiple on the 2029 earnings estimate if the execution plan holds.
Uncover how Fluor's fair value indicates a 34% potential upside to its current price before the gap starts to close.
Exploring Other Perspectives
One angle the lowest Fluor analysts focus on is legal and contract risk. They lean on outcomes like the US$71 million Mission Solutions segment loss and still forecast about US$19.7b revenue and US$667.7 million earnings by 2029. That is a tighter, more cautious story. Treat it as one reference point and explore how this fresh contract news might reshape both views.
Explore 4 other Fluor fair value estimates, including one that suggests it could be worth just $50.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Fluor research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Fluor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fluor's overall financial health at a glance.
Looking for more investment ideas beyond Fluor?
If the Fluor story has sharpened your thinking about project driven earnings and capital returns, you can use that same lens to evaluate other opportunities using the Simply Wall St Screener.
- For investors who care most about quality at a sensible entry point, start with a curated set of 29 high quality undervalued stocks that combine fundamentals with a price that may not fully reflect them.
- If capital preservation sits high on your checklist, filter for companies with sturdier financial footing using our 30 resilient stocks with low risk scores and see which businesses line up with your risk tolerance.
- When balance sheet strength is non negotiable, narrow the field to a list of solid balance sheet and fundamentals (24 results) and focus your time on companies with cleaner finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com