
Why Primerica (PRI) Is Getting Fresh Attention Today
Primerica (PRI) heads into its next earnings report with investors focused on whether its pattern of topping profit forecasts can continue, as confidence builds around investment and savings product performance and client asset values.
At a share price of $277.55, Primerica’s short term pattern has cooled, with the 90 day share price return down 14.19%, while the year to date share price return remains positive at 7.27% and the 5 year total shareholder return stands at 71.64%.
Scan for other financials showing a similar mix of earnings momentum and recent share price pressure by reviewing our hand picked 29 high quality undervalued stocks alongside Primerica.
Primerica trades at a clear discount to both analyst targets and an implied intrinsic estimate after a sharp 90 day pullback. Is the current price a temporary air pocket, or closer to where fair value truly sits?
Most Popular Narrative: 14.5% Undervalued
Primerica’s most followed narrative pegs fair value at $324.50 using a 7.24% discount rate, compared with the latest close at $277.55. That gap hinges on how investors weigh fee driven growth against expense and distribution pressures over the coming years.
Ongoing investments in technology and digital tools, which are contributing to insurance and other operating expenses expected to grow 10 to 12% in Q3 2026 and 6 to 7% in Q4 2026, are aimed at scaling Primerica’s distribution platform and advisor support in ways that can improve productivity and operating leverage, with potential benefits to net margins once projects mature.
See why 8 investors see Primerica as 14% undervalued.
Result: Fair Value of $324.50 (UNDERVALUED)
Still, the narrative around Primerica can crack if term life distribution remains under pressure and rising technology driven expenses continue to outpace revenue growth.
Find out about the key risks to this Primerica narrative.
Another View: Primerica Through The Earnings Multiple
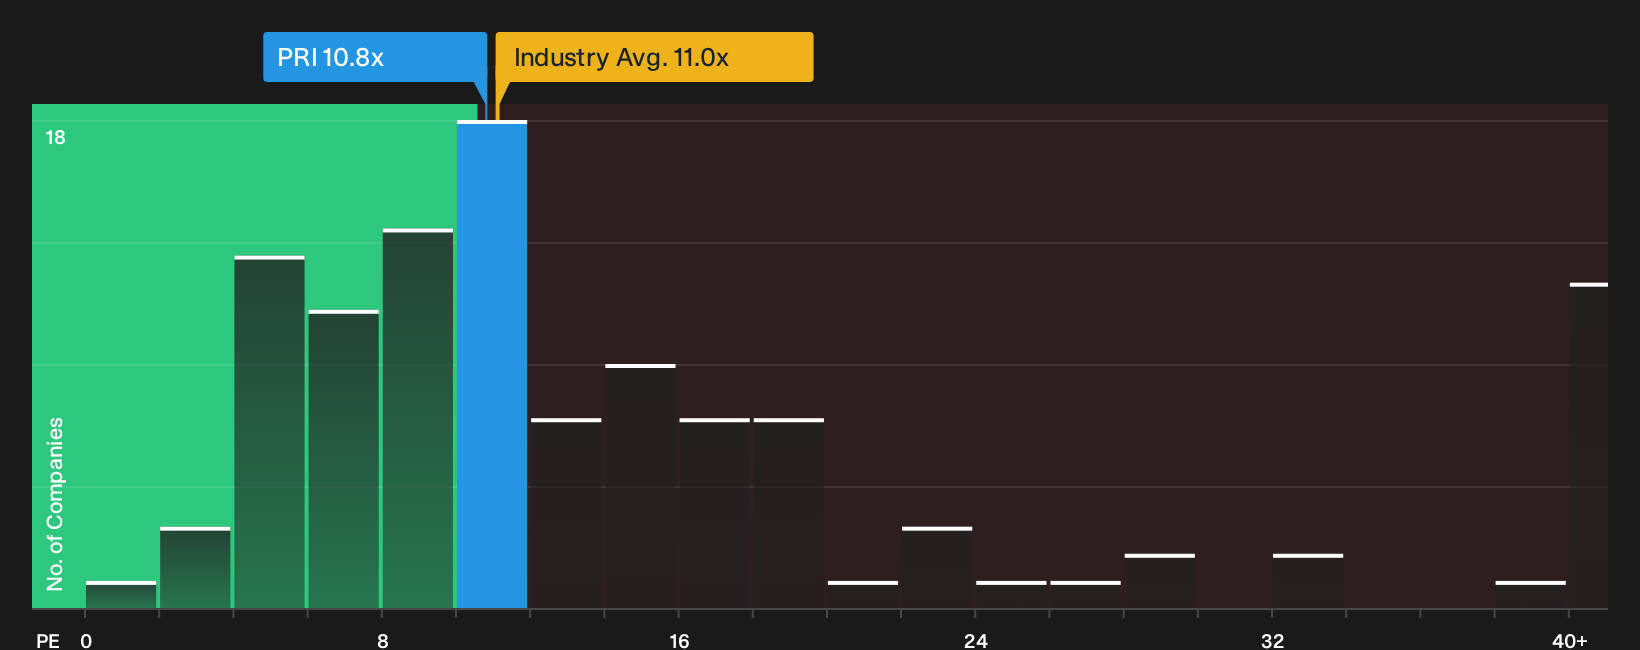
Primerica might look cheap against analyst fair value estimates, yet the picture changes when you just look at the earnings multiple. The shares trade on a P/E of 10.8x, only slightly below the US Insurance sector on 11.4x, and modestly above a fair ratio of 10x. That mix points to limited safety margin if growth underwhelms, but also to limited overpricing if forecasts hold. Which signal do you put more weight on: the narrative fair value or the earnings benchmark?
To see how these earnings ratios and the fair ratio fit into a fuller assessment of valuation risk and opportunity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Primerica’s value can be confusing, so weigh the concerns and the upside for yourself, then size up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Primerica?
Round out the work done on Primerica by lining up a few fresh candidates. The right watchlist today can shape tomorrow’s opportunities.
- Target bigger upside potential by scanning a 21 high quality undiscovered gems that many investors may not yet be watching closely.
- Build a sturdier core to your portfolio with a list of solid balance sheet and fundamentals (24 results) that can better handle tougher conditions.
- Dial down portfolio stress by focusing on a 30 resilient stocks with low risk scores that scores well on financial resilience and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com