
Is InterDigital (IDCC) Undervalued On Its Brazil Patent Win?
InterDigital (IDCC) just secured a preliminary injunction in Brazil against TCL over patents tied to HEVC video coding, putting its licensing terms and intellectual property enforcement approach under a brighter investor spotlight.
InterDigital’s latest Brazilian court win lands at a moment when momentum has been mixed, with the share price rising 25.9% over the past 90 days after some earlier softness, while the 1-year total shareholder return is down 10.9% despite a very large 3-year and 5-year total shareholder gain.
Scan beyond InterDigital and see how other IP rich tech businesses with patent driven models are shaping up in our hand picked list of 21 high quality undiscovered gems
InterDigital’s sharp 90 day rebound sits against a 1 year total return that is still down. This raises a simple question: Is most of the upside already in the rear view mirror, or not yet fully priced in?
Most Popular Narrative: 29% Undervalued
InterDigital’s most followed valuation story pegs fair value around $462.67 a share, well above the last close of $328.81. This puts the recent court win into a bigger revenue and licensing context.
The continued build out of streaming and cloud video licensing, backed by recent injunction wins related to HEVC patents against large media groups, points to further fixed fee contracts that could broaden ARR and support EBITDA margins if more major video platforms sign on similar terms.
See why 20 investors see InterDigital as 29% undervalued.
Result: Fair Value of $462.67 (UNDERVALUED)
Still, the bullish InterDigital story leans heavily on the Amazon arbitration outcome, as well as on enforcement costs not climbing to a point where they erode margins.
Find out about the key risks to this InterDigital narrative.
Another Way To Look At InterDigital’s Valuation
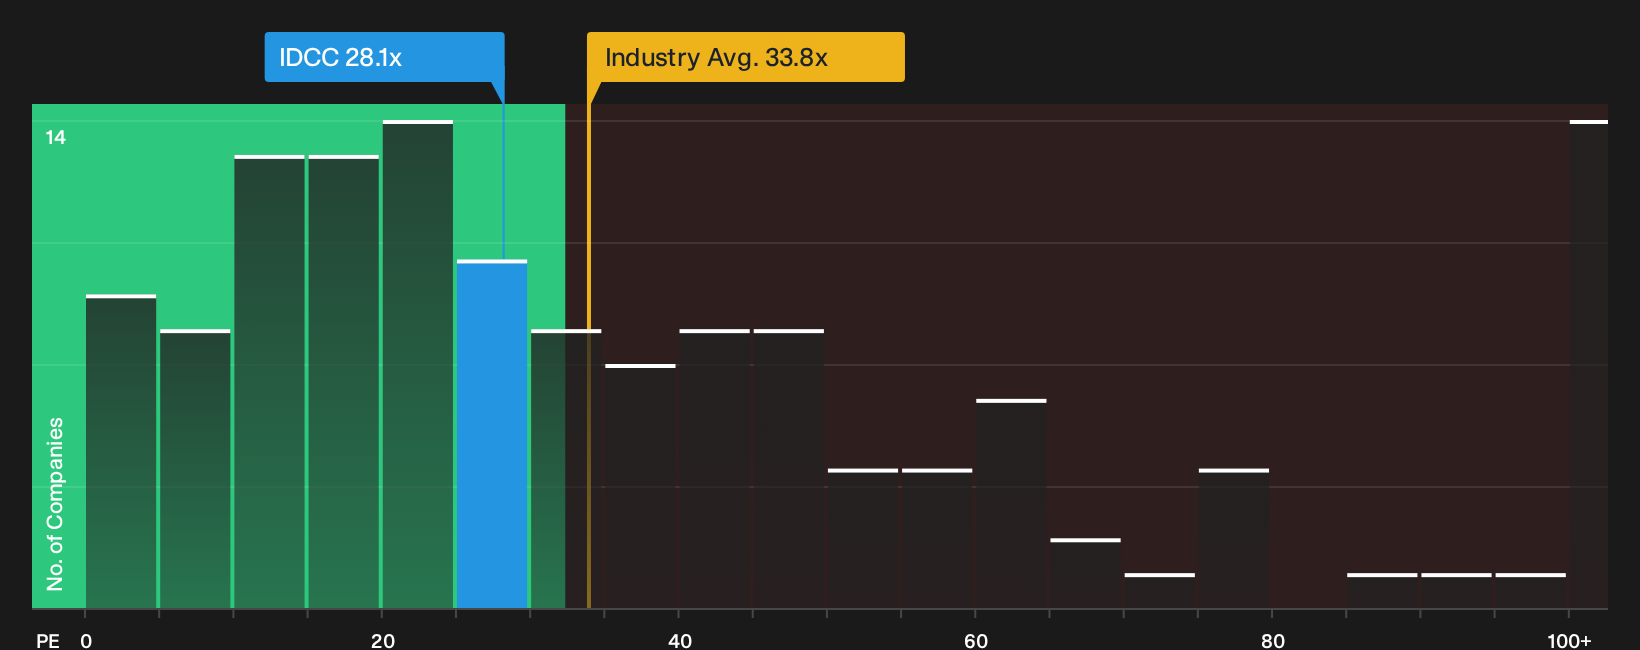
That 29% undervalued story leans heavily on future earnings power. A different read comes from today’s P/E. InterDigital trades on 28.1x earnings, which is cheaper than the US Software sector on 32.7x and below peers at 30.3x, yet still above a 24.8x fair ratio that our model suggests the market could drift toward over time. Is that gap a margin of safety, or a warning that the multiple has less room to stretch?
For a closer look at how this earnings multiple maps to real world pricing risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimistic or cautious after all this, the key is to pressure test the numbers yourself and move before sentiment shifts again. To see what investors currently view as the main bright spots, take a look at the 3 key rewards.
Looking for more investment ideas beyond InterDigital?
If InterDigital has sharpened your thinking, do not stop here. Broaden your watchlist now so you are not spotting the next opportunity in hindsight.
- Target potential mispricings by scanning a focused set of 29 high quality undervalued stocks that combine solid fundamentals with attractive entry points.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can better handle tougher conditions than highly leveraged peers.
- Lock in income ideas by shortlisting a set of 5 dividend fortresses that offer higher yields while still passing basic quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com