
Missed Mitsubishi Chemical Group's Rally? Here Is What Changed
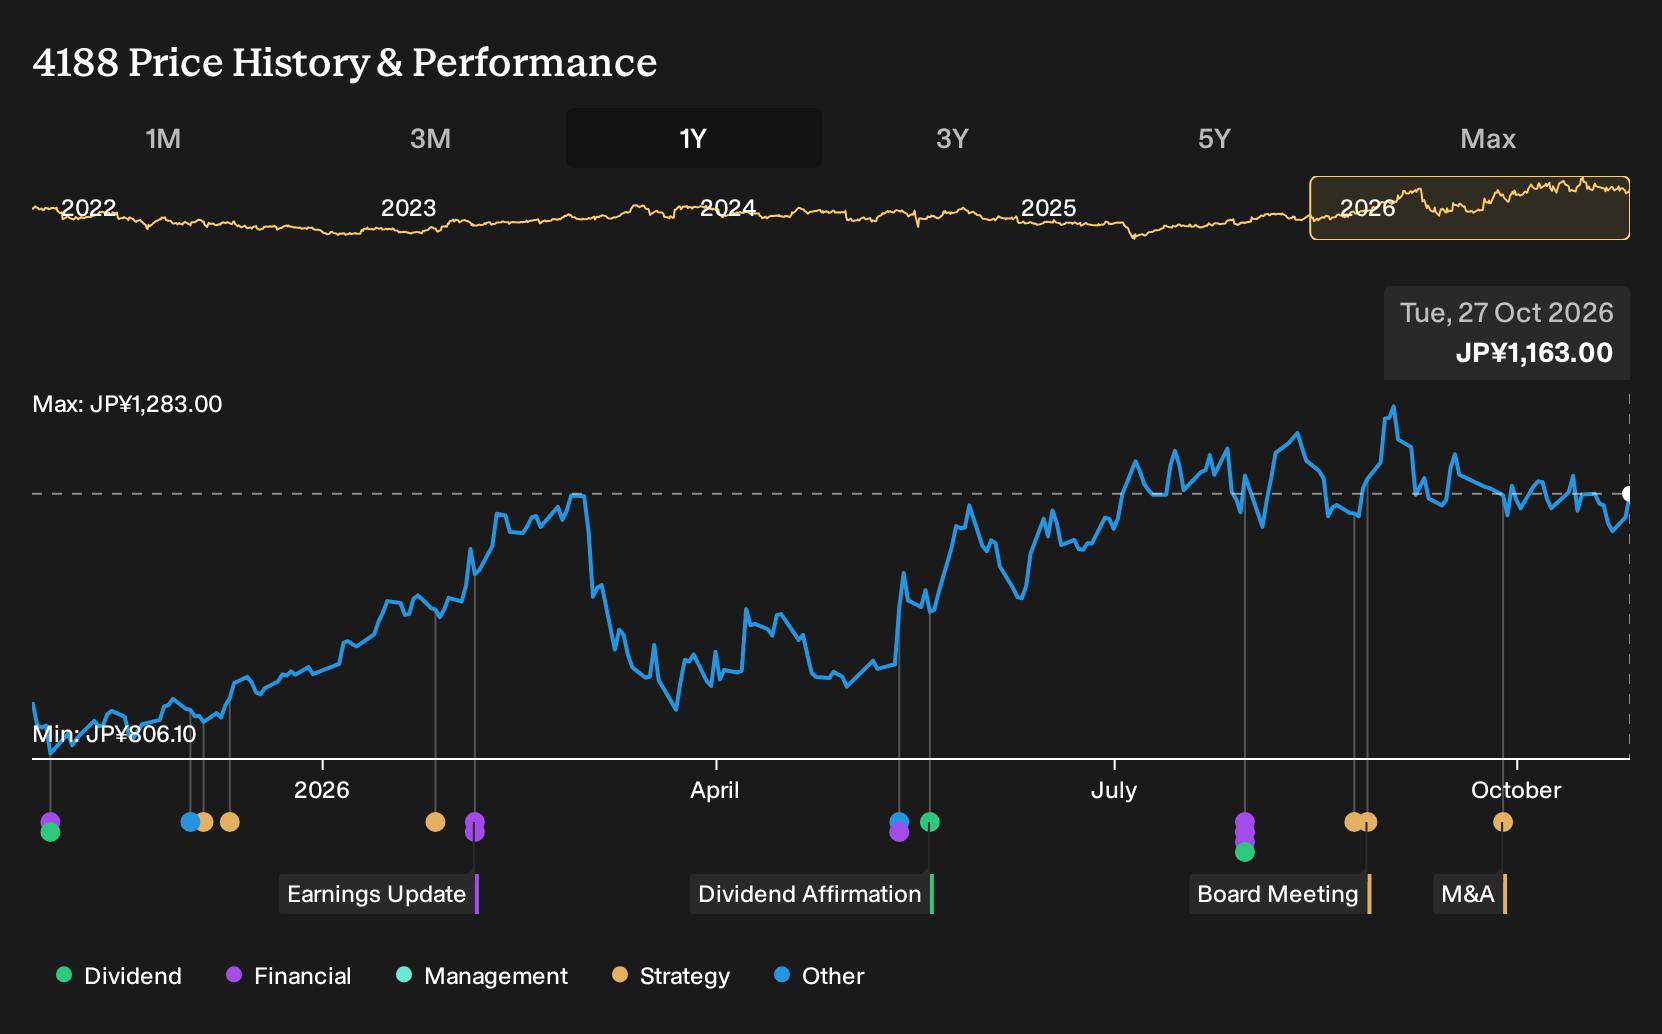
If you only skimmed Mitsubishi Chemical Group headlines about regulatory pressure, Chinese competition and struggling legacy units, a strong payoff might have seemed unlikely. Holding Mitsubishi Chemical Group over the past year would have returned 42.0%, including dividends. That gain landed while analysts argued over whether fair value sat closer to ¥923 or ¥700. If you had faced that split view at the start, what exactly in the record would have justified taking the risk?
If the move has made Mitsubishi Chemical Group harder to judge, start where the gap is still open and scan 16 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Mitsubishi Chemical Group
The shares cost ¥874 at the start of the period, and Mitsubishi Chemical Group sat between two very different stories about its future.
On the optimistic side, the specialty materials thesis pointed to a Fair Value of ¥923. This price was implied by expectations that shifting toward higher value and sustainable materials, together with cost cuts and divestitures, would support more stable earnings.
The pessimistic view argued for a Fair Value of ¥700, based on concern that tougher environmental rules and lower cost Chinese rivals in MMA and petrochemicals would keep profitability under pressure.
What The Results Changed For Mitsubishi Chemical Group
The clearest new fact for Mitsubishi Chemical Group was Q1 2027 earnings. Revenue was ¥1,004,246m and net income reached ¥57,706m, with net margin at 5.7% versus 1.9% a year earlier. That shift in profitability lined up more with the optimistic specialty materials story, although recycled carbon fiber and FY26 plans also kept the transition risks in view. Overall, the evidence cut both ways.
The practical takeaway is simple. When a thesis hinges on a margin rebuild, track the actual net margin in each report and compare it with the original forecast, rather than focusing only on the headline sales line or share price.
What Today's Mitsubishi Chemical Group Price Already Assumes
Mitsubishi Chemical Group now trades at ¥1,163, after a 42.0% gain over the past year. The selected Narrative’s Fair Value sits below the current price, reflecting a view that restructuring costs and weaker chemicals earnings could leave profitability sensitive.
A buyer today effectively banks on specialty and semiconductor related materials lifting core operating income enough to outweigh MMA volatility and restructuring charges. The question is how that assumption holds up against the Narrative’s emphasis on fragile group margins and suspended Saudi MMA capacity.
"The numbers imply the share price already reflects optimistic assumptions about successful execution on Chemicals portfolio reshaping, specialty materials expansion, and cost savings. This is occurring even though the company still faces MMA spread risk, potential prolonged suspension of the Saudi MMA plant, and incomplete restructuring in Chemicals."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Go Straight To The Source
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 16% below our estimate - adds salespeople to win more long-term maintenance contracts and denser local portfolios.
- Company 2 - 50% below our estimate - ties staff incentives to subscription growth as security platforms expand deeper into AI tools.
- Company 3 - 36% below our estimate - leans on AI tools to charge more for performance based hiring and matching services.
Three companies from the same screener. Open all 23 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com