
Does Phase 3 Dose Selection Change The Bull Case For Xencor (XNCR)?
- Xencor reported updated Phase 1 data for XmAb819 in advanced clear cell renal cell carcinoma, selected a 400 mcg/kg intravenous dose for further development, and outlined plans for a global randomized trial and potential accelerated approval discussions with the FDA.
- The early efficacy signals in heavily pretreated, high-risk kidney cancer patients highlight a potential new use case for Xencor's bispecific antibody platform in solid tumors, with future trials also exploring combinations and alternative dosing schedules.
- We will now look at how Xencor's investment narrative could shift as XmAb819 advances with a selected 400 mcg/kg dose.
Xencor Investment Narrative Recap
To own Xencor, you need to believe its XmAb platform can convert strong early science into later stage products in cancer and autoimmune disease, despite the business currently reporting a loss of US$163.3 million. The updated XmAb819 data matters because it adds another potential pillar alongside TL1A programs, which could support the long-term pipeline story.
In the near term, the key operational swing factor is whether Xencor can move XmAb819 efficiently into registration enabling studies and keep timelines for a global randomized trial on track. The biggest risk remains execution and funding around multiple costly late stage programs while the group is still unprofitable.
The most relevant recent move is Xencor selecting 400 mcg/kg intravenous as the proposed Phase 3 dose for XmAb819 after reporting a 45.5% confirmed objective response rate in the current efficacy evaluable cohort. That decision gives the oncology franchise a clearer development path and tightens the focus for upcoming regulatory and trial milestones.
For you as a shareholder, this creates a more defined catalyst map around FDA accelerated approval discussions in 2027 and the planned randomized study versus tivozanib. It also concentrates risk around whether larger studies can replicate these early signals while managing Grade 3 or higher adverse events, in particular liver enzyme elevations and rash, within a viable benefit risk profile.
Xencor's narrative projects US$160.0 million revenue and US$25.5 million earnings by 2029. This assumes 15.1% yearly revenue growth and an earnings increase of about US$188.8 million from current earnings of a US$163.3 million loss.
Uncover why Xencor's fair value indicates a 28% potential upside to its current price before the gap to market expectations narrows.
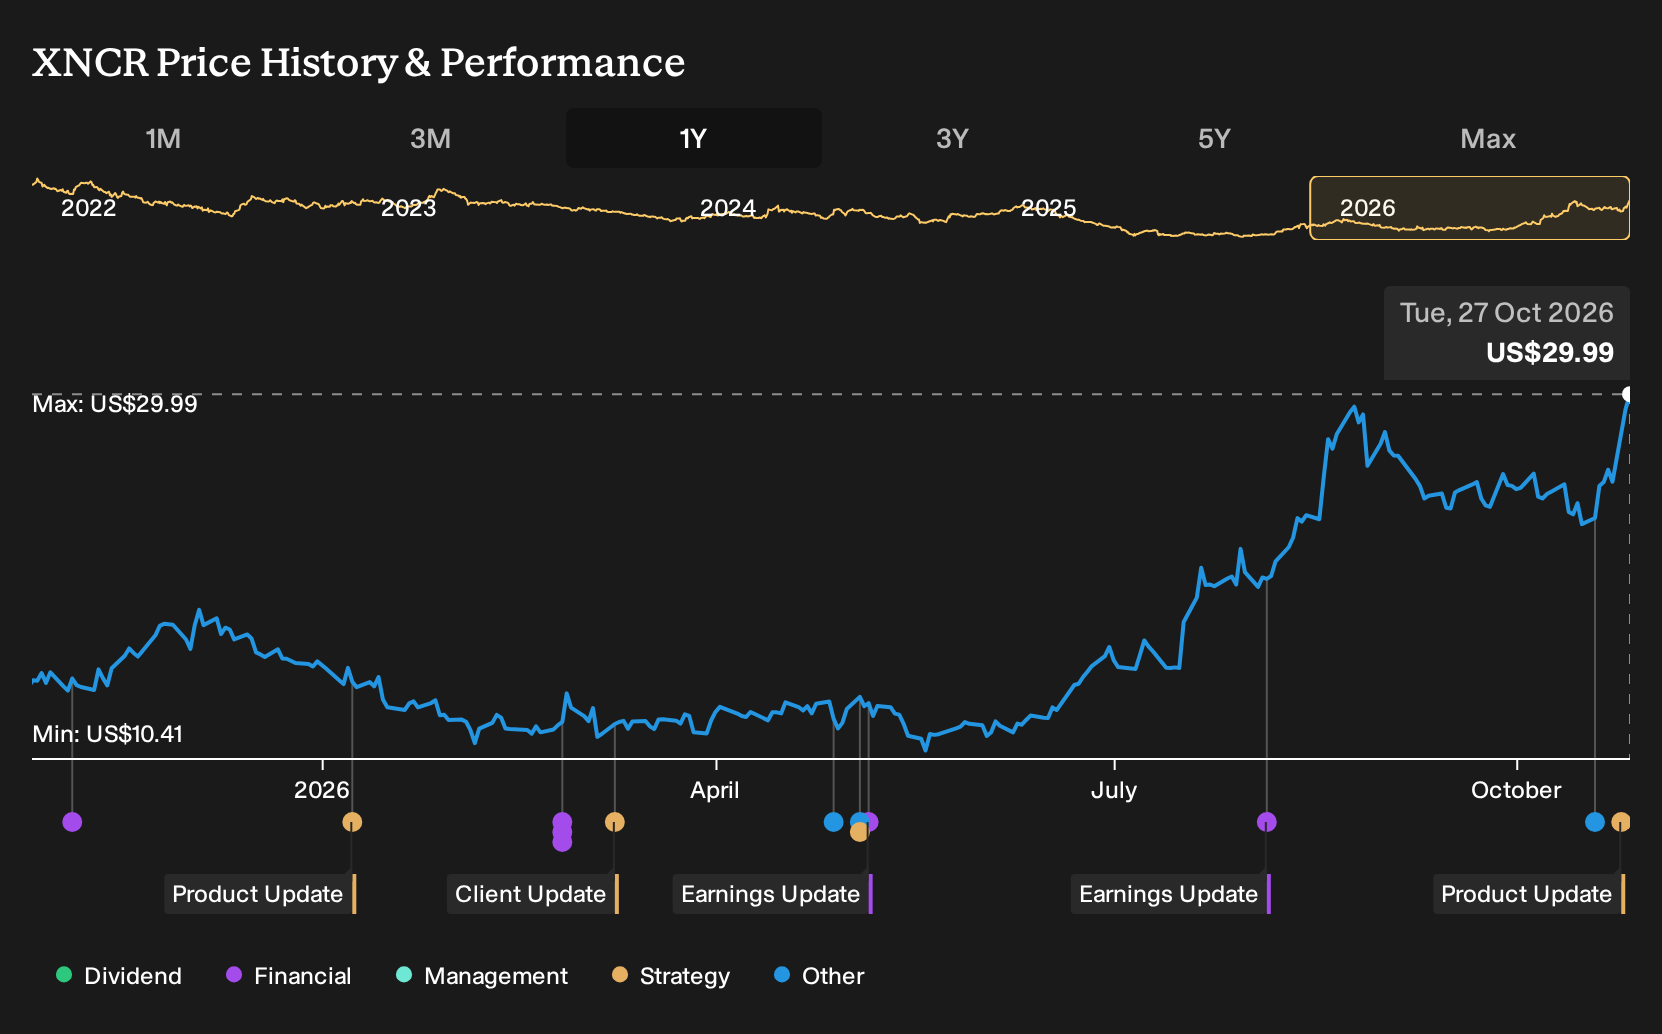
Exploring Other Perspectives
You have one big swing factor that bearish analysts keep coming back to. They worry Xencor’s TL1A drugs never reach the ulcerative colitis efficacy levels needed to justify broad use, which helps explain why they were modeling only US$70.7 million revenue and US$12.2 million earnings by 2029. Those projections, set before the XmAb819 update, show how sharply opinions can differ. It makes sense to compare several viewpoints before deciding how this new data might reshape expectations.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Xencor research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Xencor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xencor's overall financial health at a glance.
Looking for more Xencor-like investment ideas?
If Xencor is already on your watchlist, it can help to widen the lens and compare it with other companies that share similar qualities in balance sheet strength, income potential, or perceived mispricing. The Simply Wall St Screener gives you a structured way to filter for those traits instead of relying only on headlines or hype.
- For investors who care most about resilient businesses and capital preservation, check out a curated group of lower risk opportunities through the 30 resilient stocks with low risk scores.
- If steady income matters more than near term excitement, consider income focused opportunities by scanning the 5 dividend fortresses that prioritize higher yields.
- When you want a broader watchlist of companies with firm financial footing rather than single story bets, the list of solid balance sheet and fundamentals (24 results) can surface candidates with stronger fundamentals to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com