
Travis Perkins (LSE:TPK) Looks Fairly Valued After Revenue Slipped 1.8%
Trading update puts Travis Perkins revenue trend in focus
Travis Perkins (LSE:TPK) has come under closer scrutiny after its latest trading statement showed group revenue declining 1.6% in the third quarter and 1.8% for the year to date to 30 September 2026.
Recent trading updates appear to be feeding into sentiment, with Travis Perkins shares delivering a 90 day share price return of 10.97% and a 7 day move of 6.22%. However, the 1 year total shareholder return is still down 2.19% and the 5 year total shareholder return has fallen 52.99%. This points to short term momentum building after a much weaker longer run outcome.
Spot shifts in building suppliers like Travis Perkins early by scanning our hand picked list of solid balance sheet and fundamentals (10 results) for potential alternatives and comparables.Recent gains put Travis Perkins in a very different place compared with a year ago. Is most of the recovery already reflected in the share price, or is there still clear valuation upside ahead?
Most Popular Narrative: 3% Undervalued
The most followed valuation storyline currently places Travis Perkins fair value at about £6.55, slightly above the latest close at £6.32. That small gap keeps attention on whether operational fixes and modest growth expectations can support a higher long term valuation.
Sustained investment in digital infrastructure and omnichannel offerings, especially through Toolstation and centralized procurement, positions the company to capitalize on the growing shift to digital engagement and supply chain optimization in construction, supporting long-term revenue per customer, margin improvement, and increased capital efficiency.
See why 7 investors see Travis Perkins as 3% undervalued.
Under this narrative, analysts model revenue growth of roughly 2.8% a year, profit margins moving from a loss position of 3.9% to a positive 2.0%, and earnings reaching £98.7m by around June 2029. Those forecasts are then discounted back using a rate of 10.99%, which reflects the required return used in the Simply Wall St company report.
To line up with that £6.55 view, the story also assumes Travis Perkins would trade on a P/E of 19.4x those future earnings, above the current 15.4x for the wider GB Trade Distributors group. That higher multiple only holds if the expected turnaround in profitability, better use of digital channels, and steadier margins actually show through in reported numbers.
For readers, the takeaway is that the current narrative is asking you to accept modest growth, improved margins, and a premium P/E multiple to justify only a small uplift from today’s share price. Any shortfall on execution, especially around ERP fixes, cost control, or demand in UK construction, could narrow that valuation gap quickly.
Result: Fair Value of £6.55 (UNDERVALUED)
Still, the Travis Perkins story can slip if UK construction demand stays weak, and if digital execution problems or ERP setbacks keep dragging on margins and cash flow.
Find out about the key risks to this Travis Perkins narrative.
Another view on Travis Perkins valuation
The first storyline presents Travis Perkins as modestly undervalued on future earnings. A contrasting perspective comes from the SWS DCF model, which estimates future cash flow value at £1.83 compared with a market price of £6.32, implying the shares trade well above that estimate. Which yardstick do you trust more when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
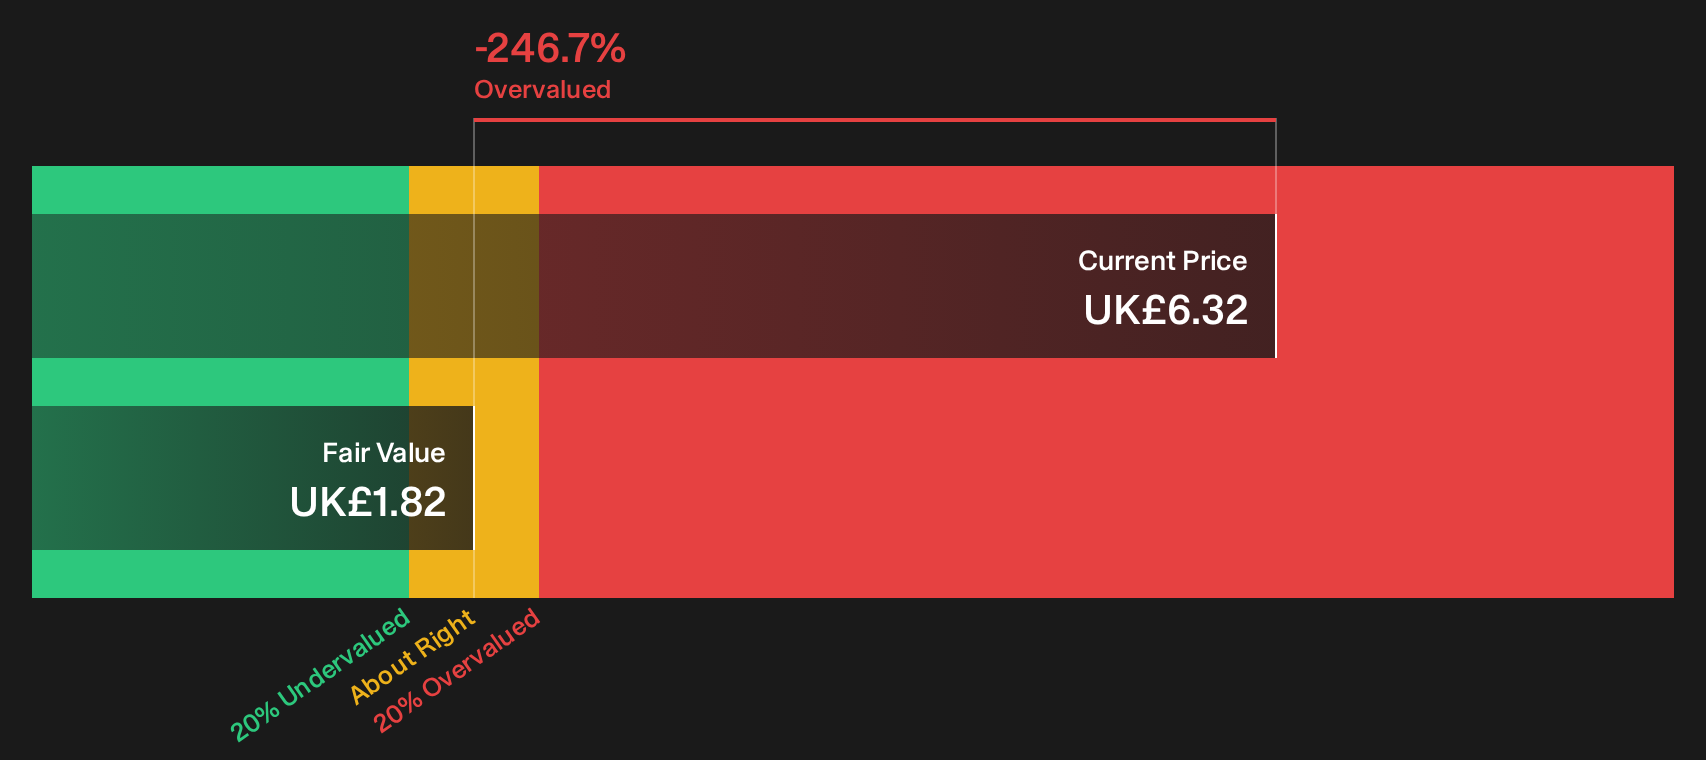
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Travis Perkins for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 10 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signal on Travis Perkins leaves you undecided, that is the point. Move quickly from reading to testing the data yourself and see the 2 key rewards.
Looking for more investment ideas beyond Travis Perkins?
If Travis Perkins leaves you on the fence, widen your watchlist now and pressure test your thesis against fresh ideas before the next market move passes you by.
- Target resilience first by scanning companies with sturdier finances using the 4 resilient stocks with low risk scores.
- Spot potential value gaps quickly by running the 10 high quality undervalued stocks and comparing pricing against quality and fundamentals.
- Hunt for under-the-radar opportunities early by checking the 5 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com