
Does China Plant Review Change The Bull Case For Bekaert (ENXTBR:BEKB)?
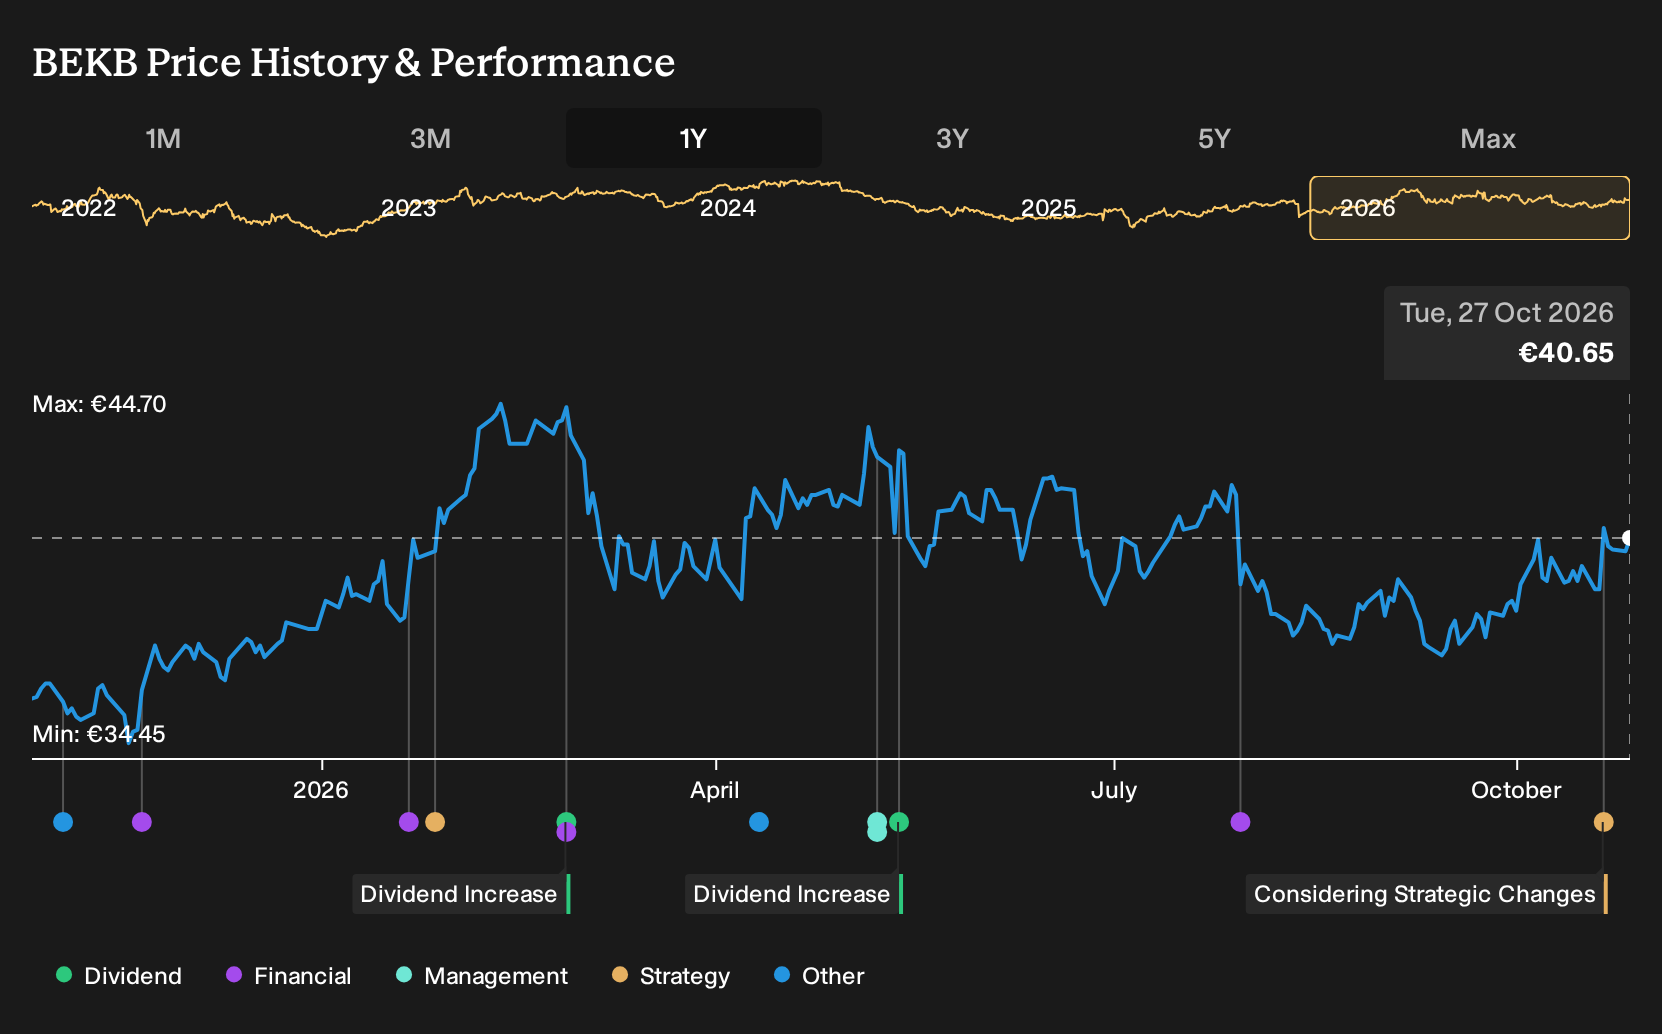
- NV Bekaert has reportedly hired an adviser to review options for its Chinese manufacturing facilities, including a possible separation of the plants or local partnerships, while stating its current priority is to deliver its 2026 results safely.
- The review of the Chinese operations highlights how NV Bekaert is reassessing a key production base at a time when cost efficiency and local partnerships could materially affect its future operating setup and capital allocation.
- We will now look at how NV Bekaert's review of Chinese manufacturing options could influence the broader investment narrative around the group.
Scan NV Bekaert's peer group by reviewing the hand picked list of solid balance sheet and fundamentals (207 results).
NV Bekaert Investment Narrative Recap
To own NV Bekaert you need to believe management can keep shifting the group toward higher value wire solutions while sorting out weaker pockets like ropes and lower margin Asian tire reinforcement. The Chinese review looks like plumbing work on a key production hub rather than a change to that overall direction. For now, the near term focus still sits on cleaning up earnings quality after large one off items and rebuilding margins from 2.2% net levels.
The most immediate swing factor remains execution on cost efficiency and mix, especially where global tire cord overcapacity and Asian pricing pressure meet Bekaert's Rubber Reinforcement footprint. Any future transaction around Chinese plants could influence regional exposure and unit economics, but at this stage the news is early and does not yet alter the main risk, which is a sustained tilt toward structurally lower margin Asian volumes.
Recent commentary around restructuring the hydrogen activities and ramping the Currento Microporous Layer for PEM electrolyzers ties directly into this China discussion. Both speak to a portfolio that is being tweaked for better returns, while trying to keep optionality in energy transition markets alongside more mature tire and construction products.
If Bekaert were to change how capital is tied up in Chinese facilities, that could sit alongside hydrogen restructuring, cost programs, and the Bridon-Bekaert Ropes recovery work as part of the same execution test. Investors may want to see whether these moving pieces collectively simplify the group and support the existing plan for earnings growth and continued low leverage, without adding fresh operational complexity in already competitive Asian steel markets.
NV Bekaert's current analyst narrative points to revenues of €3.9b and earnings of €293.8 million by 2029, based on an assumed 2.9% yearly revenue growth rate and an earnings step up of about €214 million from current earnings of €79.9 million.
Uncover why NV Bekaert's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Another angle you might consider is the more cautious view on NV Bekaert's Asian exposure. The lowest analysts were already assuming only 1.2% yearly revenue growth to about €3.7b and earnings of €254.7 million by 2029, so this China review could either reassure that group or push forecasts lower. Those more pessimistic voices had not yet factored in any potential separation or partnerships around the Chinese plants, which means their already cautious narrative on mix and margins may shift again once this news is fully reflected.
Explore another NV Bekaert fair value estimate, including one that suggests it could be worth just €44.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so rely on your own research and judgment.
- A great starting point for your NV Bekaert research is our analysis highlighting 2 key rewards and 3 important warning signs that could inform your investment view.
- See our latest analysis for NV Bekaert. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it possible to review NV Bekaert's overall financial profile at a glance.
Looking for more investment ideas beyond NV Bekaert?
Once you have formed a view on NV Bekaert, it can help to compare that thinking with other opportunities that match your preferences on balance sheets, income or risk levels. The Simply Wall St Screener lets you filter for these types of companies quickly, so you can spend more time assessing the stories that matter to you.
- If you want potential value combined with resilient finances, start with a curated set of 195 high quality undervalued stocks that pair supportive cash flows with stronger balance sheets.
- For investors who care most about income, you might focus on dependable payers by reviewing a hand picked group of 224 dividend fortresses that currently offer higher yields.
- If capital preservation sits at the top of your checklist, concentrate on stability first and scan a focused collection of 223 resilient stocks with low risk scores that score better on risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com