
PayPal (PYPL) Q3 Results Lean On Buybacks As Growth Stays Soft
PayPal Holdings came into this Q3 2026 report with a mixed recent run, the share price down over the past week yet slightly higher over the past month. The stock jumped about 2% to US$56.09 after the release, which suggests investors liked what they saw more than they feared what they remembered.
The key headline is earnings power. Basic EPS landed at about US$1.26 for the quarter and non GAAP EPS, highlighted on the call, grew to US$1.45, backed by roughly US$2.0b in adjusted free cash flow. For a payments heavyweight wrestling with modest top line progress, that profit engine is the real story today.
Like the earnings profile at PayPal Holdings but want more payment and fintech stocks that pair strong cash generation with resilient balance sheets? Filter for that combination in the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$8,584m vs. US$8,417m (up about 2%).
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): US$1,073m vs. US$1,248m (down about 14%).
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.26 vs. US$1.31 (down about 4%).
- Adjusted Free Cash Flow (Q3 2026): about US$2.0b in the quarter, supporting buybacks and the broader PayPal Holdings capital return plan.
Tired of squinting at rows of PayPal Holdings figures and trying to keep all the ratios straight in your head? See the full visual breakdown of the business, with a clear view of its valuation at a glance, in the company report for PayPal Holdings.
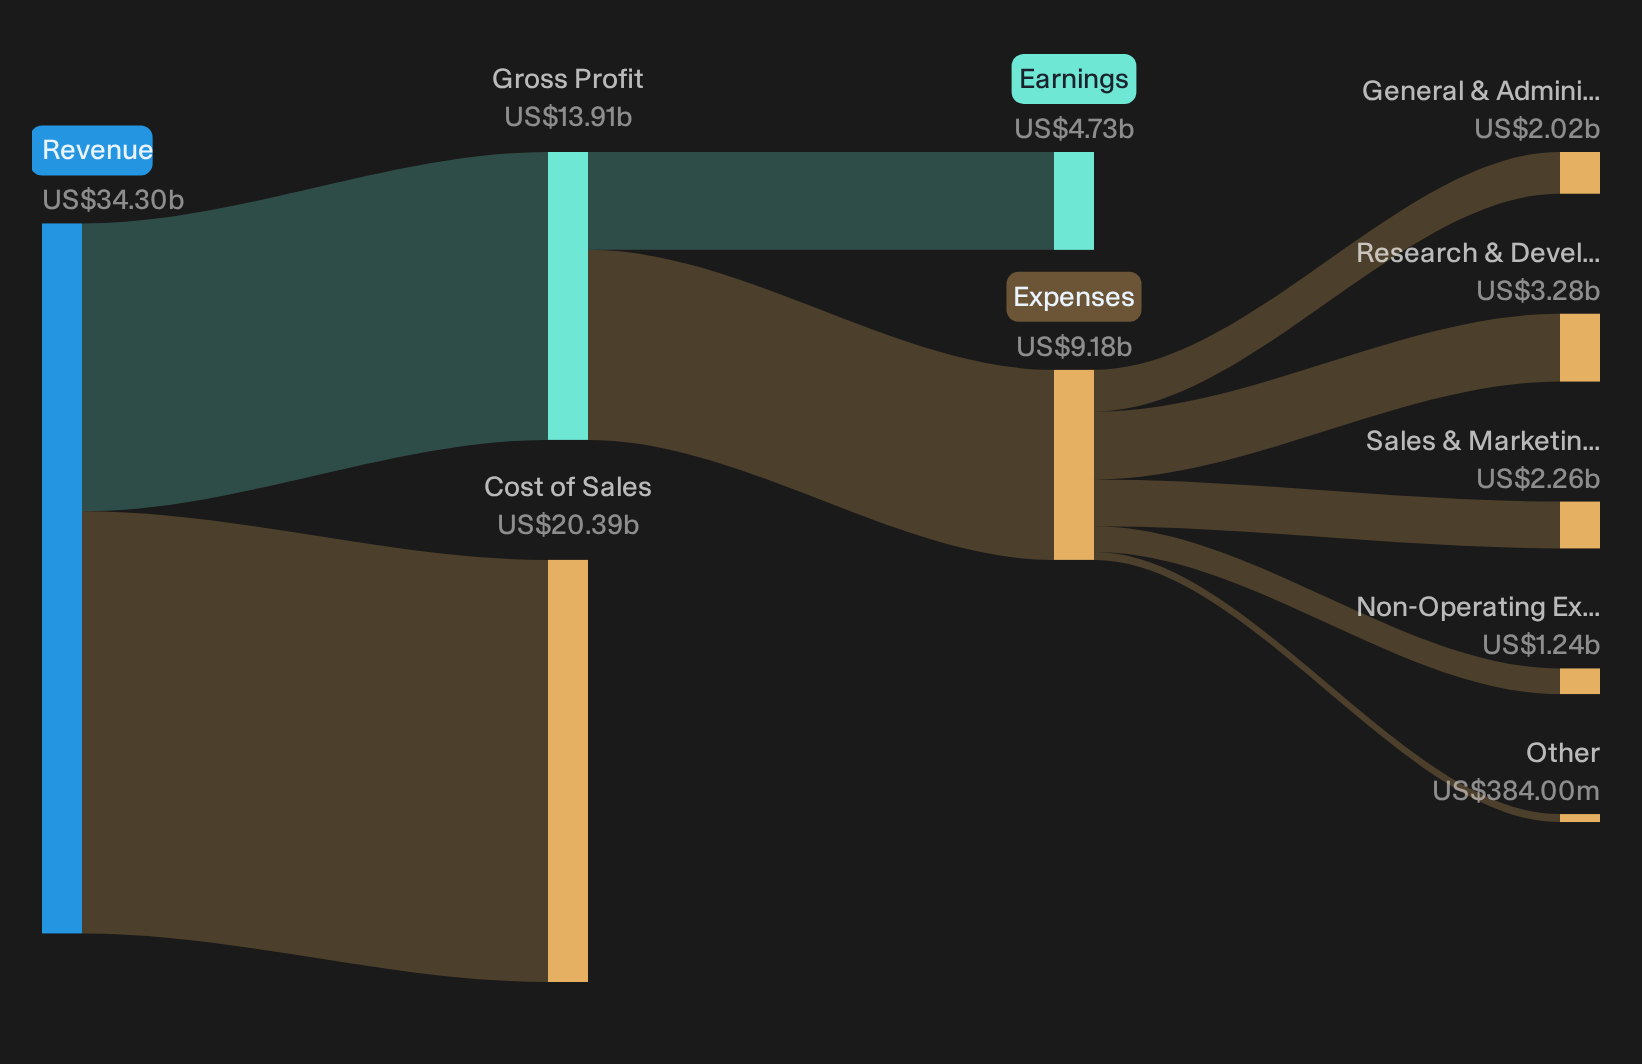
PayPal bull case hinges on checkout and buybacks
The optimistic pitch says PayPal just needs a steady franchise and a powerful repurchase program. The claim is clear.
"The buyback engine. PayPal retires roughly 8–9% of its shares per year (~16% total buyback yield at recent prices; share count fell from 920M to 892M in a single quarter). At a depressed price, every dollar of buyback retires more shares. The same total profit spread over a shrinking share count mechanically compounds EPS."
Q3 shows this engine still running, with US$1.5b spent on repurchases and adjusted free cash flow of about US$2.0b. Non GAAP EPS rising to US$1.45 supports the per share math, helped by tighter non transaction costs and improving transaction margin dollars.
Bear case tests PayPal’s erosion and margin fears
The worry is simple. If the franchise thins out, the financial engineering turns hollow.
"Erosion instead of stabilization. Early indicators are slightly negative (active accounts marginally down, transactions per account -1%). If the base erodes, buybacks destroy value instead of creating it. This is the single most important risk."
Latest figures point to pressure but not a break. Revenue grew about 2% and transaction margin dollars advanced roughly 2%, or 3% excluding interest on customer balances. Branded checkout TPV limped along in the low single digits and net income excluding extra items fell 14%, so the franchise is holding but not yet clearly strengthening.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Cash Machines
PayPal Holdings just reminded investors how much story can sit behind a single quarterly print. The real opportunity is hunting for stocks that could be undervalued before the crowd catches on.
- Company 1 - 31% below our estimate - focus on converting record program wins in complex regulated hardware into sustained production runs and recurring service work.
- Company 2 - 22% below our estimate - turn an installed base of cloud and productivity users into paying AI subscribers embedded directly in everyday workflows.
- Company 3 - 42% below our estimate - expand from solar trackers into storage and inverter systems that deepen project relationships and raise lifetime revenue per site.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com