
PriceSmart (PSMT) Stock Stumbles As Q4 Earnings Meet A Margin Squeeze
PriceSmart stock dropped about 4% in regular trading to roughly US$166 after its Q4 2026 earnings hit the tape, even as the retailer closed out the year with higher revenue of US$1.52b and quarterly net income of US$36.7m. Traders focused on the near term and sold into a three month slide that has already taken the shares down about 14%.
Longer horizon investors will likely care more about the full year picture, including US$5.88b in revenue and US$5.40 in trailing twelve month earnings per share, and how that compares with a P/E multiple above both peers and the wider industry.
Like PriceSmart's earnings power but unsure about paying up for a richer P/E during a pullback? Line this up against our 29 high quality undervalued stocks to see how it compares with other high quality operators priced more conservatively.
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs Q4 2025): US$1,516.3m vs. US$1,331.0m (up about 13.9%)
- Net Income, excl. extra items (Q4 2026 vs Q4 2025): US$36.7m vs. US$30.7m (up about 19.4%)
- Basic EPS (Q4 2026 vs Q4 2025): US$1.21 vs. US$1.02 (up about 18.8%)
- Gross Margin (FY 2026 vs FY 2025): 16.0% vs. 15.7% (up about 0.3 percentage points)
Tired of scrolling through dense tables and earnings figures for PriceSmart? Explore the full story in charts instead and see how the valuation stacks up in our company report for PriceSmart.
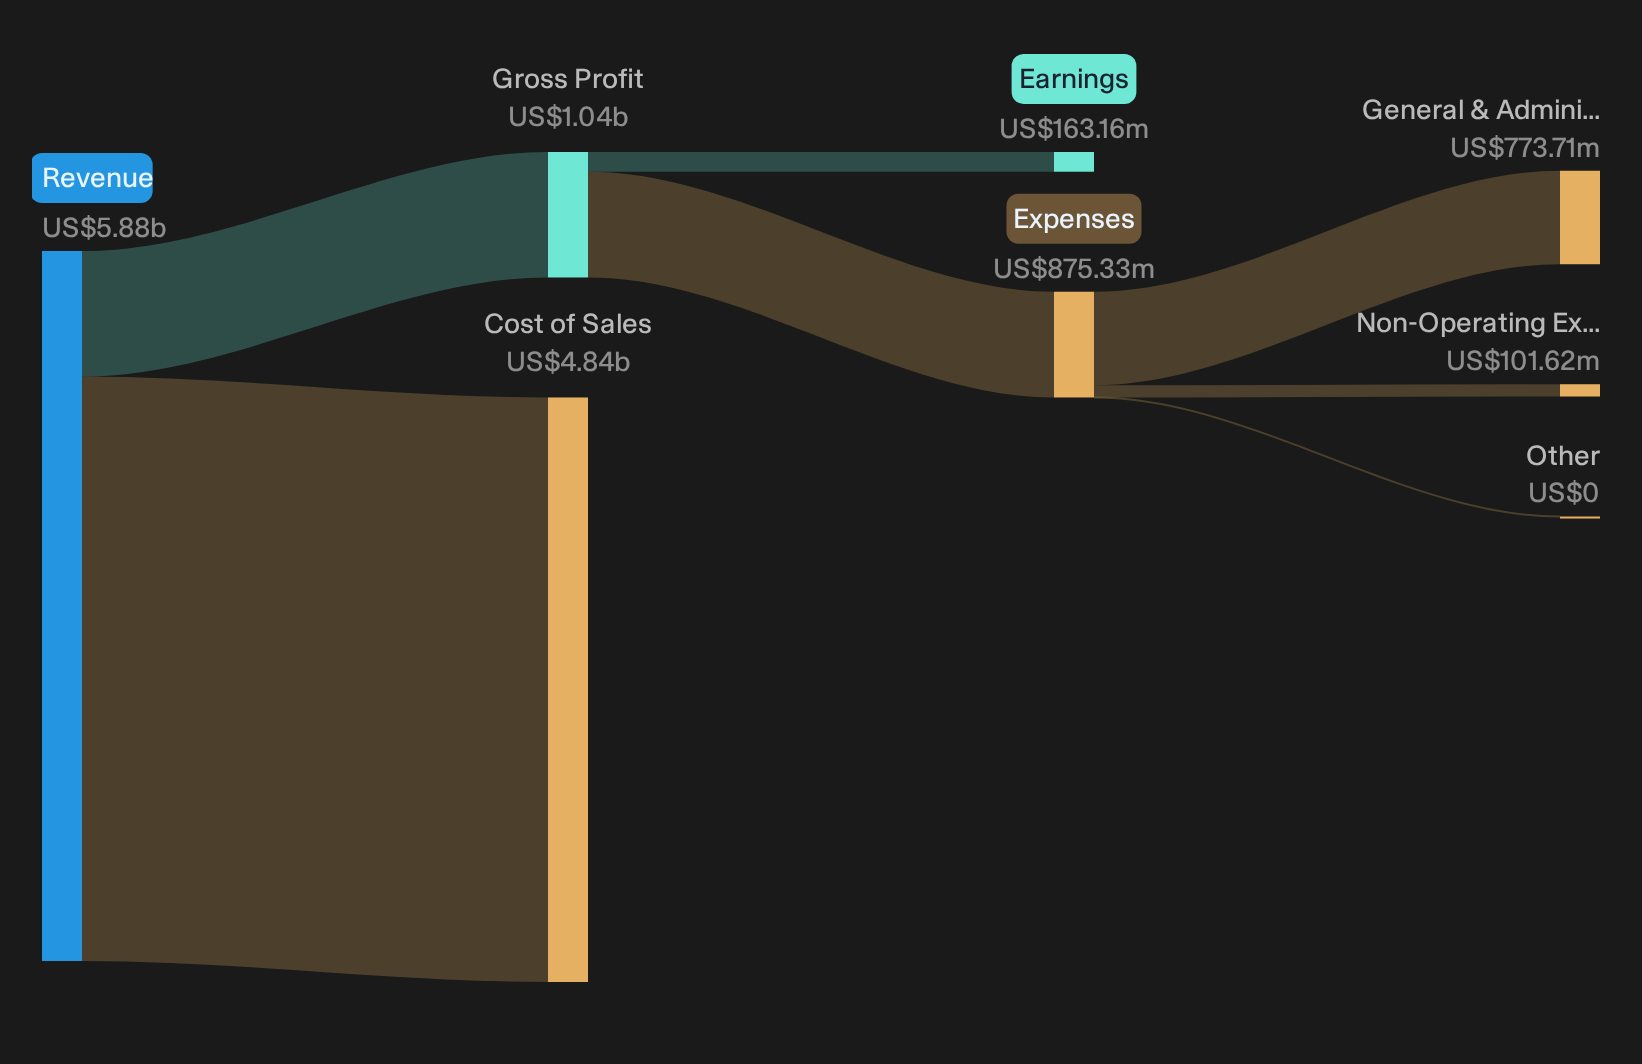
PriceSmart’s Bullish Expansion Story Meets Real Membership Gains
The upbeat view on PriceSmart hinges on whether new clubs, better logistics, and technology actually support a larger, more profitable network rather than just adding cost and complexity.
"Bullish analysts expect PriceSmart to build on double digit net merchandise sales growth, rising membership income and growing digital channels in order to support a larger and more profitable warehouse club network over time."
On that score, several milestones are being hit. Net merchandise sales rose at double digit rates in Q4 and for the year. Membership accounts increased 8.7%, renewal rates reached 90.4%, and Platinum penetration climbed to 23.4%. Digital channels approached 7% of merchandise sales. Gross margin improved to 16.0%, although SG&A compression lagged, which keeps the profitability side of this thesis partially unproven.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
PriceSmart Bear Case: Costs Rising Faster Than Proof
The skeptical view argues that PriceSmart’s expansion and systems projects risk locking in higher costs without clear payback yet.
"Large scale technology and data projects, including the RELEX forecasting platform now expected to complete in fiscal 2027, the E2open trade management rollout and the membership omnichannel transformation system, require ongoing spend and training. Management has already acknowledged extended time lines, so further delays or adoption challenges could leave SG&A structurally higher without a matching uplift in revenue or operating margin."
Fresh results lean toward that concern. Gross margin ticked up, yet SG&A rose to 13.2% of revenue and operating margin compressed in Q4 as Chile startup and tech spending hit earnings.
Hunt For Mispriced Earnings Power
PriceSmart shows how a solid operational story and a sliding share price can move in different directions. The real opportunity sits in finding stocks that could be undervalued before the market catches up.
- Company 1 - 38% below our estimate - uses government-backed trade-in programs and rising secondhand adoption to scale recurring device recommerce volumes.
- Company 2 - 18% below our estimate - shifts new manufacturing capacity toward higher value AI data center optics and complex photonics packaging work.
- Company 3 - 23% below our estimate - expands surgical robotics installations and procedure coverage to deepen recurring usage of its orthopaedic platforms.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com