
Flexsteel Industries (FLXS) Stock Stung By Q1 Results And Margin Pressure
Flexsteel Industries just took a hard hit. The stock closed at about $67.39, a drop of 18.4% from the prior session, as investors reacted to fresh Q1 FY2027 results. At first glance, the step down in quarterly earnings per share to about $1.32 and softer operating margin grabbed the market’s attention and triggered selling.
Step back a little and the picture looks different. Over the last twelve months, earnings per share of about $6.47 and a P/E near 8.8x against higher industry multiples presents a furniture manufacturer that the market now prices more harshly than its recent profit record suggests.
Love Flexsteel Industries’ earnings power over the last year but concerned the latest quarter just reset expectations lower? Scan a more focused peer group with stronger recent execution and similar value characteristics in our 29 high quality undervalued stocks
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs. Q1 2026): US$113.97m vs. US$110.44m (up about 3.2%)
- Net Income (Q1 2027 vs. Q1 2026): US$5.42m vs. US$7.33m (down about 26.0%)
- Basic EPS (Earnings Per Share, Q1 2027 vs. Q1 2026): US$1.32 vs. US$1.38 (down about 4.7%)
- Operating Margin (Q1 2027 vs. Q1 2026): 6.0% vs. prior year period not specified in detail (margin pressured by foreign currency translation loss and higher freight, transport and input costs)
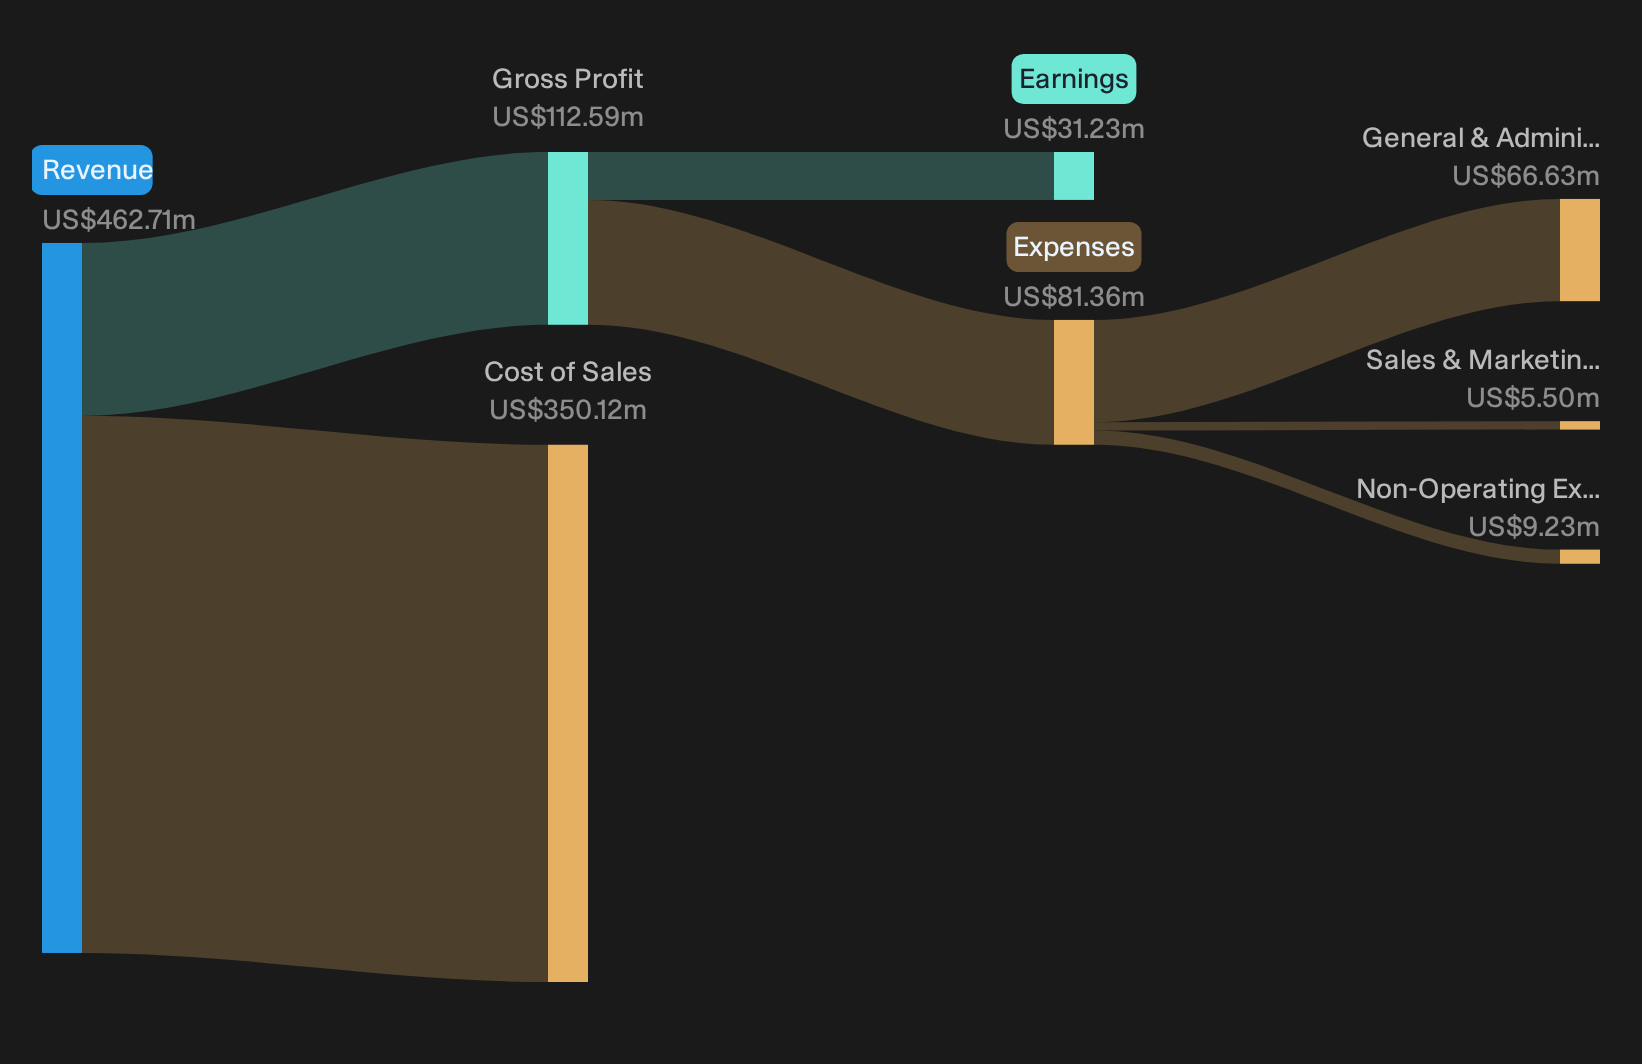
Flexsteel wellness and key accounts thesis on trial
Supporters argue Flexsteel Industries can lean on newer wellness lines and focused retail partners to keep the story intact even while the wider furniture market stays soft.
"Consumer led health and wellness products that have shown positive unit volume trends even when broader volumes were under pressure are expected to carry a larger weight in Flexsteel Industries' mix over time."
Q1 backs part of that script. Orders rose about 5% and backlog reached US$77.7m, with health and wellness platforms and soft seating singled out as growth drivers. The offset is margin. Gross margin moved to 22.0% and operating margin to 6.0%, held back by higher freight and a foreign currency hit.
Tariffs, input costs and mix risks under the microscope
Skeptics worry tariff and cost pressure, combined with weaker legacy categories, could undercut the wellness and big account story at Flexsteel.
"Weakness in made to order soft seating and case goods, where unit volumes are already under pressure and growth expectations are more cautious, could outweigh strength in health and wellness products."
The quarter shows that pressure, but not a collapse. Revenue increased about 3.2% despite exiting lower margin homestyles ready to assemble products, helped by soft seating growth and share gains with large omnichannel retailers. Margin compression ties more to tariffs, freight, energy linked inputs and foreign exchange than to an obvious demand drop in made to order seating.
The price and this Narrative do not agree. → Uncover what this Narrative says Flexsteel Industries is actually worth.
Hunt For Mispriced Earnings Power
Flexsteel Industries just reminded investors how quickly sentiment can swing on a single quarter. The real opportunity sits in finding stocks that could be mispriced before expectations reset.
- Company 1 - 31% below our estimate - builds accelerated computing racks that power data centre upgrades for intensive AI workloads.
- Company 2 - 42% below our estimate - expands a coconut based drinks platform as retailers prioritise functional hydration over sugary sodas.
- Company 3 - 46% below our estimate - wins large fixed price infrastructure contracts that convert a swollen backlog into higher margin work.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com