
Bank of Hawaii (BOH) Q3 Results Back Margin Gains As Stock Stays Flat
Bank of Hawaii just reported Q3 2026 results that kept its core engine, net interest income, grinding higher while the share price barely flinched. The stock slipped about 0.7% on the day, a muted move for a bank posting $1.49 in quarterly earnings per share and a return on average common equity of 15.4%. That disconnect captures today’s mood. Traders focused on a soft tape for financials, while the actual report showed a tenth straight quarter of net interest margin expansion and credit costs that stayed firmly in check.
Love that Bank of Hawaii kept net interest income and returns on equity solid, but want more options where balance sheets and fundamentals are front and center? Compare BOH with our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$196.01 million vs. US$180.14 million (up about 8.8%)
- Net Income, Excluding Extra Items (Q3 2026 vs. Q3 2025): US$58.99 million vs. US$48.08 million (up about 22.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.50 vs. US$1.21 (up about 23.8%)
- Net Interest Margin, or NIM (Q3 2026 Trailing Twelve Months vs. Q3 2025 Trailing Twelve Months): 2.45% vs. 2.39% (up 0.06 percentage points)
Bank of Hawaii just boosted its share repurchase plan again. Ask Charlie what Bank of Hawaii’s buybacks signal about management’s confidence.
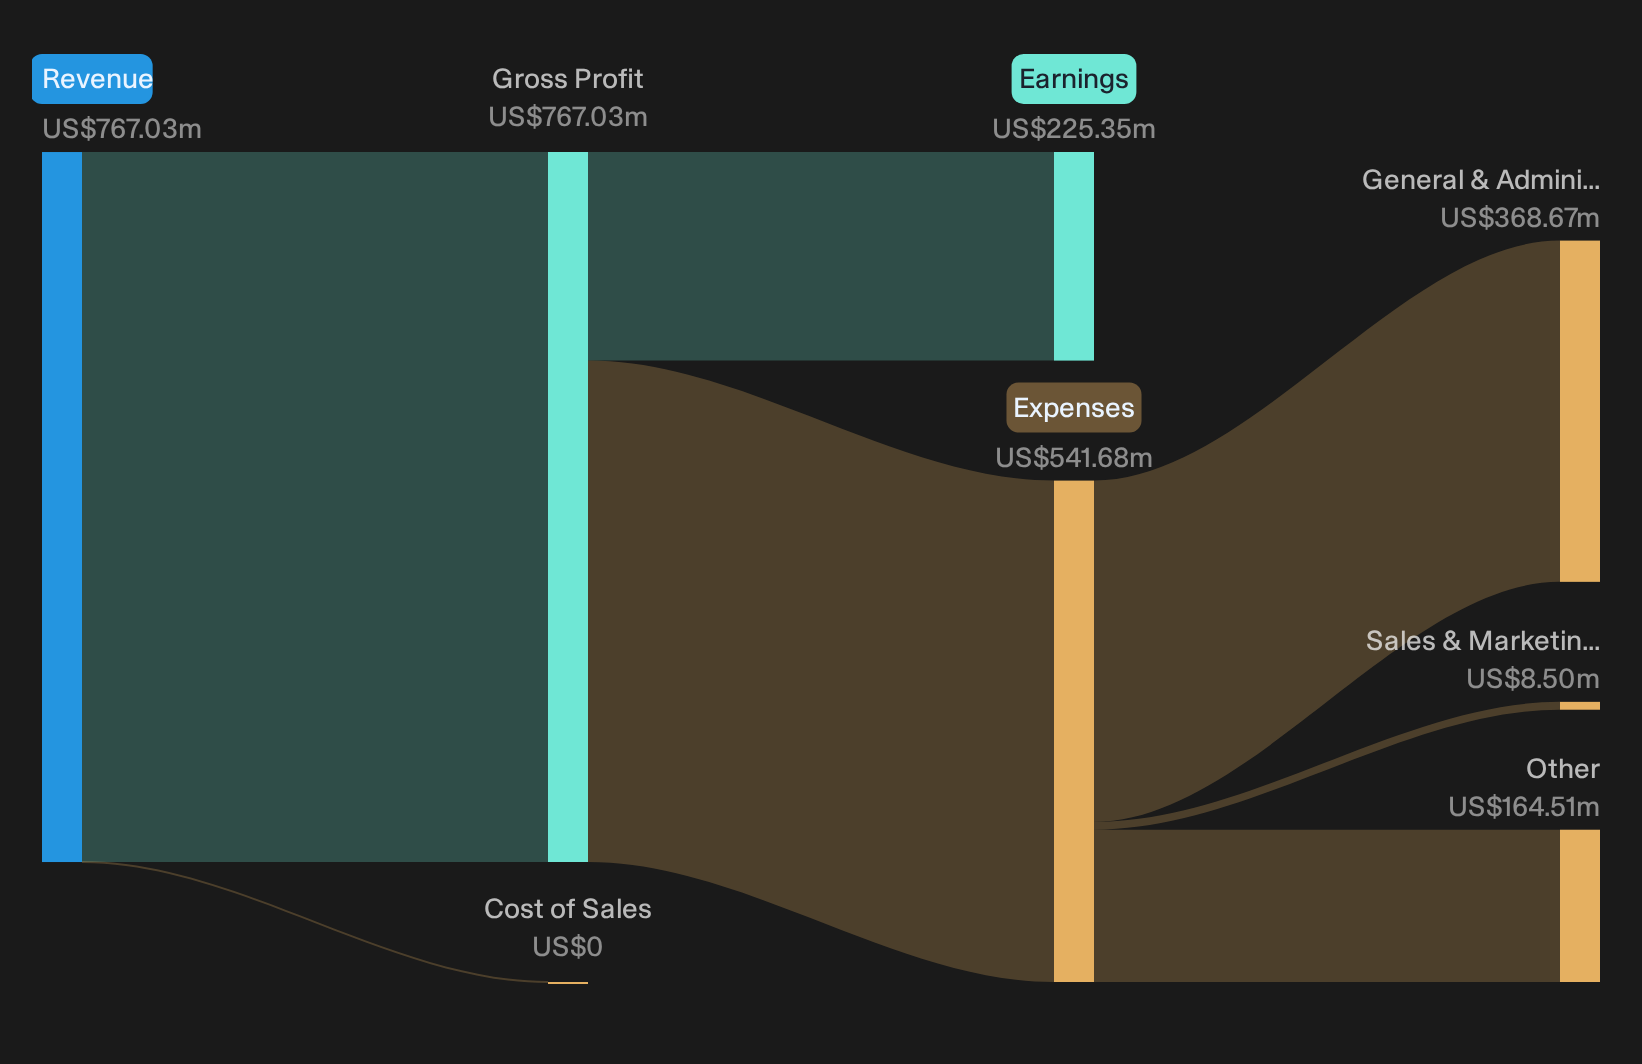
Bank of Hawaii Bull Case: Margin And Fee Milestones
Supporters expect Bank of Hawaii’s funding and fee engines to do the heavy lifting. The narrative hinges on relationship deposits, measured loan growth and stable wealth revenues feeding a higher margin profile.
"Analysts expect Bank of Hawaii to keep using its low cost, relationship based deposit base and measured loan growth to support earnings as net interest margin trends toward management’s 2.9% target and fee income from wealth and advisory businesses holds near recent levels."
Q3 NIM at 2.82% and a tenth straight quarter of expansion show the repricing plan is tracking toward that 2.9% goal. Net interest income rose alongside modest commercial loan growth, while Q3 noninterest income of US$42.7m sat close to the guided US$43m, so the fee diversification target is broadly intact. The funded run off of about US$200m in higher cost public deposits and noninterest bearing deposits at roughly 27% of total indicate the low cost funding pillar is still holding up. Wealth related fees of US$45.2m year to date, up double digits year on year, reinforce that the advisory channel is contributing.
Bank of Hawaii Bear Case: Concentration And Margin Execution Risk
Skeptics focus on whether a Hawaii heavy book and fine margin expectations leave little room for error on credit or funding.
"Bank of Hawaii's concentration in Hawaii remains a live issue because 94% of loans are tied to that market. Any downturn in the local economy or stress from region specific events could pressure asset quality metrics and limit revenue growth and earnings resilience."
Current results argue that this specific risk has not broken the thesis yet. Delinquencies sit at 46 bps, net charge offs at 9 bps and criticized assets have eased to 2.37%. Nonperforming assets did rise to 30 bps from 8 bps due to a single commercial real estate exposure, but management expects to exit that position with an immaterial loss that is already reserved. The allowance for credit losses is US$146.2m at about 1.02% of loans and provision expense in Q3 was US$2.8m, which is consistent with a still conservative credit stance. The share price reaction, down about 0.7% on the day, points to lingering worry about geographic concentration and margin execution, yet the quarter itself does not show broad based strain in the Hawaii portfolio.
One Narrative disagrees with today's price. → See where this Narrative says Bank of Hawaii should trade.
Hunt For Quiet Fundamental Shifts
Bank of Hawaii just showed how a steady earnings story can still meet a lukewarm share price reaction. The real opportunity is spotting companies that could be undervalued before stronger fundamentals get fully reflected in valuations.
- Company 1 - 42% below our estimate - use record demand for larger LED displays, transportation projects and youth sports to scale higher margin software, services and manufacturing.
- Company 2 - 19% below our estimate - expand a teahouse network as overseas locations reshape sales mix while supply chain and membership programs deepen spending per customer.
- Company 3 - 15% below our estimate - convert surging data center construction demand into long dated projects while managing concentration risk, working capital swings and a controlling shareholder.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com