
HSBC (LSE:HSBA) Stock Can Q3 Earnings Rebuild Market Confidence?
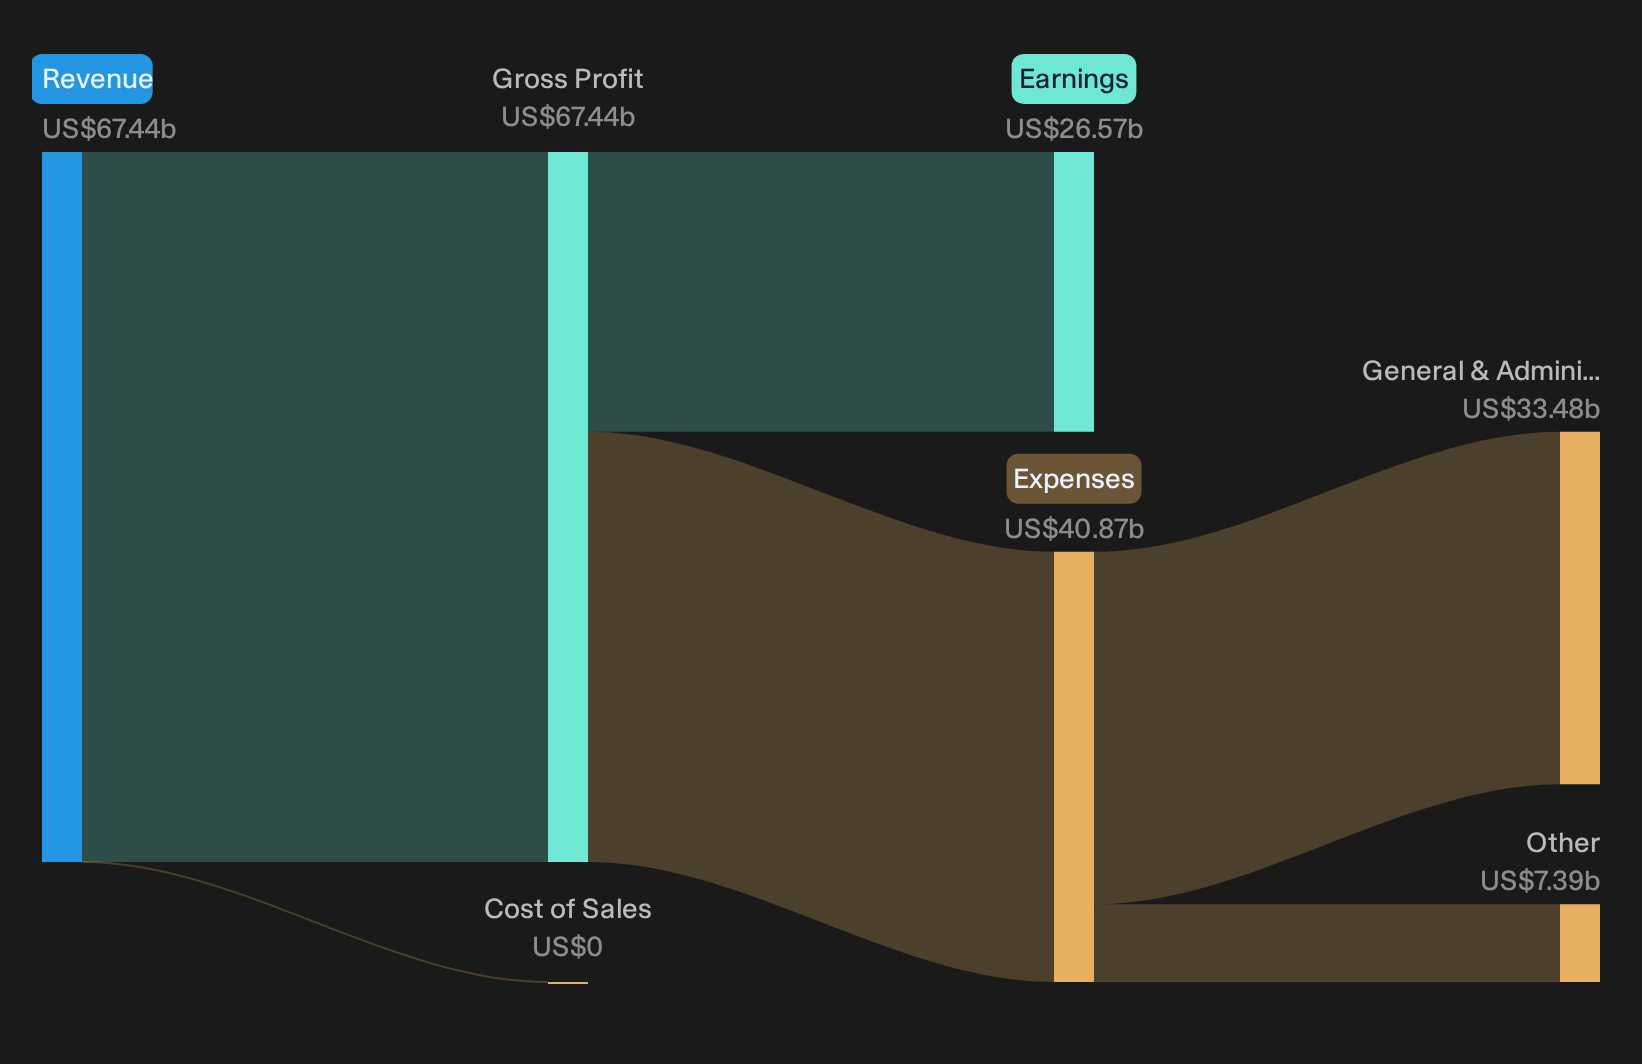
HSBC Holdings came into Q3 results with the stock under pressure, down over 16% across the past three months, and investor patience wearing thin. The bank just printed another heavy quarter of profit, with Q3 2026 net income of US$7.6b and profit before tax excluding one off items at US$10.0b. Yet the shares closed at £12.91 on 27 October, barely rewarding that earnings power. The expectation gap is clear. The market is fixated on near term worries, while the income statement still shows a highly profitable global lender.
Impressed by HSBC Holdings generating US$7.6b in quarterly net income but uneasy about a share price that has fallen 16% in three months? Take a look at our screener for high quality lenders trading on compressed expectations with the 10 high quality undervalued stocks.
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$17,788m vs. US$16,780m (up 6.0%)
- Net Income excl. Extra Items (Q3 2026 vs. Q3 2025): US$7,552m vs. US$4,873m (up 54.9%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.440 vs. US$0.282 (up 56.2%)
- Net Interest Margin (NIM), Q3 2026 TTM vs. Q3 2025 TTM: Trailing net profit margin 39.4% vs. 29.1% (improved profitability on a trailing basis)
Basel 3.1 could lift HSBC’s CET1 by up to 50 bps. Ask Charlie what HSBC will do with extra Basel capital.
HSBC’s Wealth Pivot Clears Early Execution Hurdles
The bullish story says HSBC’s tilt to Asia wealth and insurance will carry earnings power well beyond the current rate cycle, so the first test is whether those engines are actually moving.
"Rapid expansion of Wealth and new customer flows in Asia, including US$29b of net new invested assets with more than half from Asia and over 900,000 new to bank customers year to date, shows HSBC is plugged into long term growth in cross border capital and rising affluent wealth."
Q3 numbers largely back that up. Wealth net new money in Asia reached US$38b in the quarter, lifting global flows to more than US$95b year to date, while Private Banking revenue grew 16%. Those are concrete volume and revenue milestones, not just ambition. They sit alongside strong Hong Kong deposit growth and a steady pivot of capital toward Asia facing businesses.
One Narrative disagrees with today's price. → See where this Narrative says HSBC Holdings should trade.
HSBC Bear Case: Concentration Fears Meet Early Results
The risk narrative argues that HSBC is loading more of its future on Hong Kong just as one of its most cyclical exposures, commercial property, is under strain.
"The planned privatization of Hang Seng Bank concentrates earnings and capital in Hong Kong at a time when commercial real estate credit quality remains under pressure. A weaker Hong Kong office market for longer could limit profit growth and RoTE expansion from this deal and weigh on earnings volatility."
Q3 credit data gives mixed evidence. Expected credit losses were US$0.8b, with Hong Kong commercial real estate described as low net charge and full year guidance held at around 45 bps. That suggests the feared stress is not yet flowing through impairments. However, the share price slide over 90 days indicates that investors still appear to be pricing in concentration risk.
Hunt For Mispriced Earnings Power
HSBC Holdings reports robust profits while the share price remains cautious. The real opportunity sits in finding stocks that could be undervalued before the gap closes.
- Company 1 - 30% below our estimate - expand underwater sensing and autonomous defence systems as protection programmes extend in duration.
- Company 2 - 25% below our estimate - restart Spanish copper developments so permits and mine ramps support higher concentrate output.
- Company 3 - 32% below our estimate - grow fee based earnings by raising capital into renewable energy and social infrastructure funds.
Three companies from the same screener. Open all 10 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com