
Tieto (HLSE:TIETO) Stock Faces Q3 Earnings Pressure From Revenue Slide
Tieto closed today at €18.90, roughly flat over the past week, even as fresh Q3 2026 figures landed with a mixed message. The headline is clear. Revenue came in at €397m while basic earnings per share dropped to €0.37 from €0.73 in Q2, as the company leaned hard into restructuring its IT services portfolio.
In the short term, that profit squeeze explains the muted share reaction. Over a longer horizon, investors are weighing those thinner quarterly earnings against a P/E of 9.2x and a discounted valuation compared with both peers and a recent DCF estimate.
Like the value case on Tieto Oyj but uneasy about a quarter where earnings shrink faster than revenue while restructuring plays out? Look for peers that pair compressed P/E ratios with cleaner profit trends in our 195 high quality undervalued stocks
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €397.0m vs. €454.2m (fell 12.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): €40.8m vs. €34.9m (rose 17.0%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.37 vs. €0.29 (increased 24.3%)
- Earnings from Discontinued Operations (Q3 2026 vs Q3 2025): loss of €0.7m vs. loss of €104.3m (materially smaller loss)
Margins are up even as Tieto’s revenue keeps shrinking. Ask Charlie what makes Tieto’s 2027 growth outlook believable.
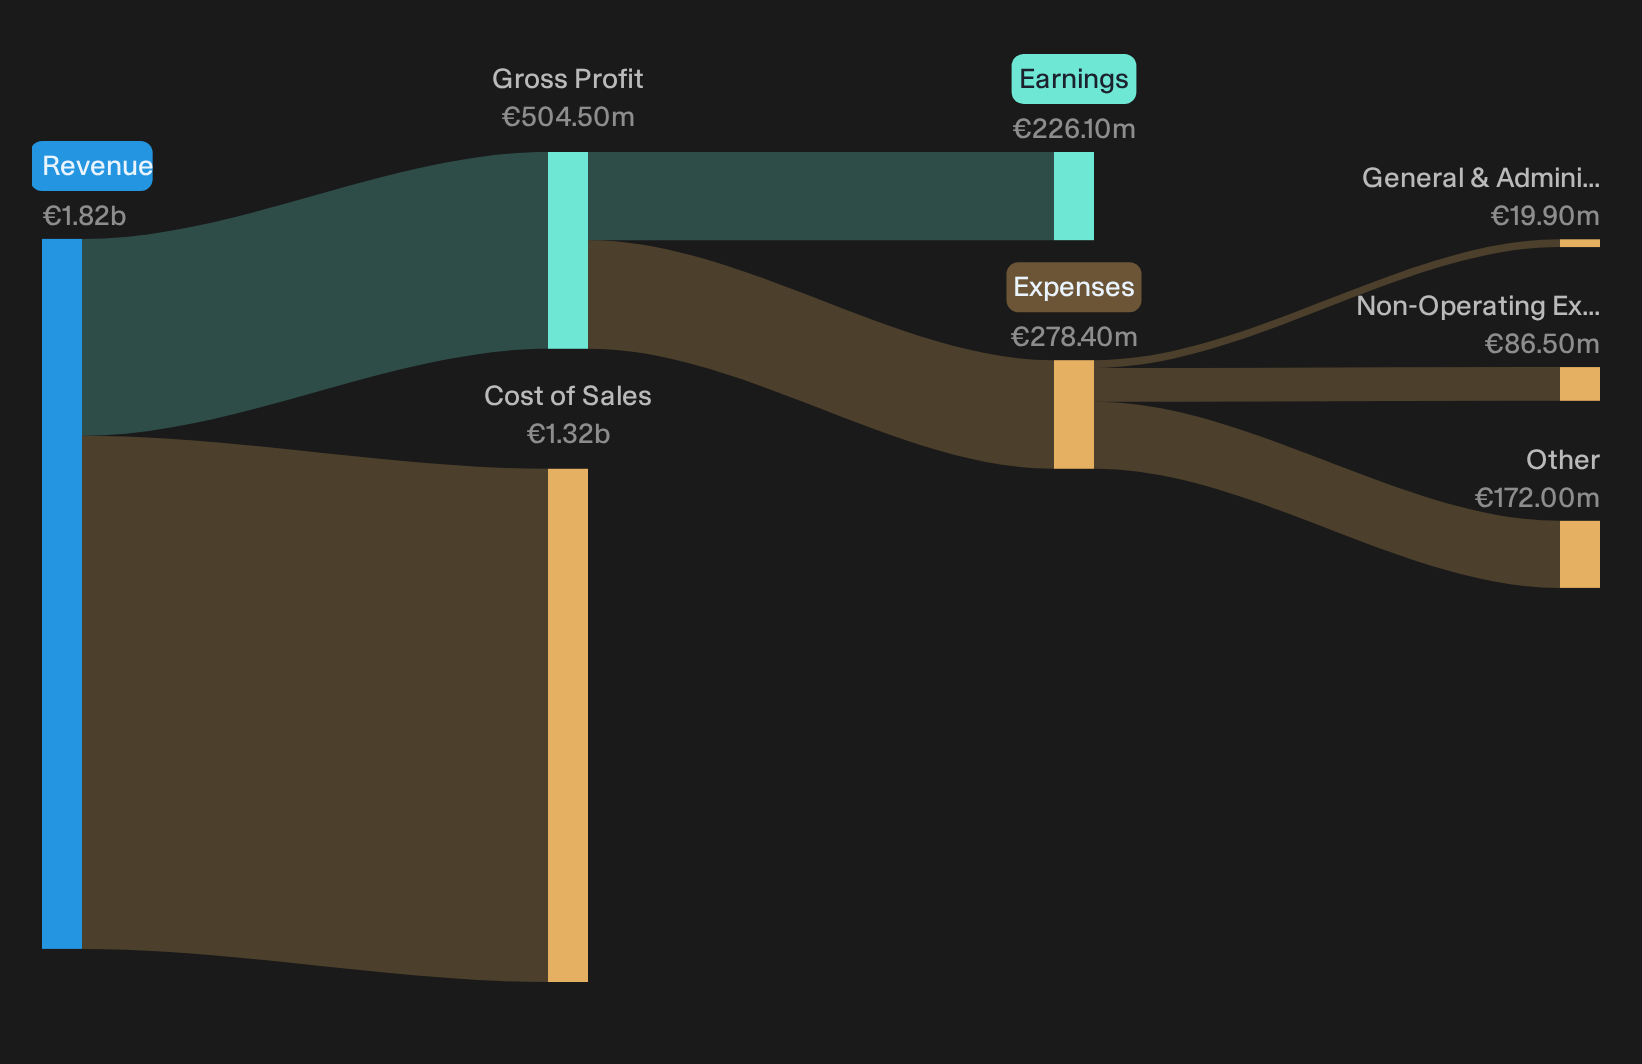
Tieto margin story hits targets while revenue sags
For the bullish view on Tieto Oyj to work, cost cuts and portfolio clean up need to translate into structurally better profitability.
"The reaffirmed 2026 adjusted EBITA margin target of 14.8% to 15.8%, combined with H1 2026 profitability already at 14.8% and ongoing delivery of the €130 million cost program, creates room for Tieto Oyj to convert a structurally lower cost base into higher net margins than many investors currently assume."
Q3 puts a clear tick next to that ambition. Group adjusted EBITA margin reached 18.0%, full year guidance was raised to 15.5% to 16.0%, and €125m of the €130m savings are already in place, even as organic revenue declined 11%.
One Narrative disagrees with today's price. → See where this Narrative says Tieto Oyj should trade.
Bear case on Tieto revenue hits fresh milestones
Bearish investors worry that Tieto Oyj’s cost saves and AI push will not offset softer demand and shrinking legacy work.
"Although Tieto Oyj is investing in AI capabilities and broad employee upskilling, the 5% organic revenue decline in Q2 2026 and weaker software volumes suggest that AI enabled offerings may not convert into sufficient new demand."
The latest quarter deepens that concern. Group organic revenue fell 11% in Q3, with Tech Consulting and Banktech both weak and 2026 organic growth guidance cut again to a decline of 6% to 5%. Strong adjusted EBITA margins rely heavily on a €130m cost program, while top line trends still point in the wrong direction.
Hunt For Mispriced Earnings Stories
Tieto Oyj just showed how a tighter margin story can sit alongside falling revenue and a quiet share price. The real opportunity sits in finding stocks that could be undervalued before the market adjusts.
- Company 1 - 30% below our estimate - sells proximity focused IT consulting as utilization and emerging AI tools reshape billable hours and pricing power.
- Company 2 - 42% below our estimate - handles payment flows for large digital platforms as merchants expand countries and channels and shift volume toward higher margin local methods.
- Company 3 - 31% below our estimate - supplies specialty chemical ingredients as added defense and nutrition capacity replaces exposure to lower margin agricultural and basic products.
Those are three of them. See every one of the 195 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com