
Alliance Resource Partners (ARLP) Q3 Earnings Power Up On Coal And Royalties
Alliance Resource Partners came into this Q3 2026 report with its stock quietly grinding higher, up low single digits over the past month, and it just added another 1.1% on the day to about $26.70. That modest move hides a punchy headline. Coal and minerals earnings surged, with basic earnings per unit jumping to about $1.09 on revenue of roughly $603 million.
Investors often view Alliance Resource Partners as a mature cash engine rather than a growth story. This quarter challenges that script as profit momentum, not just distributions, takes center stage.
Love Alliance Resource Partners' solid per unit earnings but want more assets with similar cash generation and balance sheet strength on your radar? Scan the list of solid balance sheet and fundamentals stocks (24 results) for more candidates that pair resilient finances with income potential.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$603.0 million vs. US$571.4 million (+5.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$139.6 million vs. US$94.2 million (+46.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.09 per unit vs. US$0.73 per unit (+48.0%)
- Coal Sales Volume (Q3 2026 vs. Q3 2025): 9.3 million tons vs. 8.7 million tons (+7.4%)
Tired of scrolling through dense earnings summaries and raw figures for Alliance Resource Partners? See the full financial picture, including a clear visual view of its earnings power, in the interactive company report for Alliance Resource Partners.
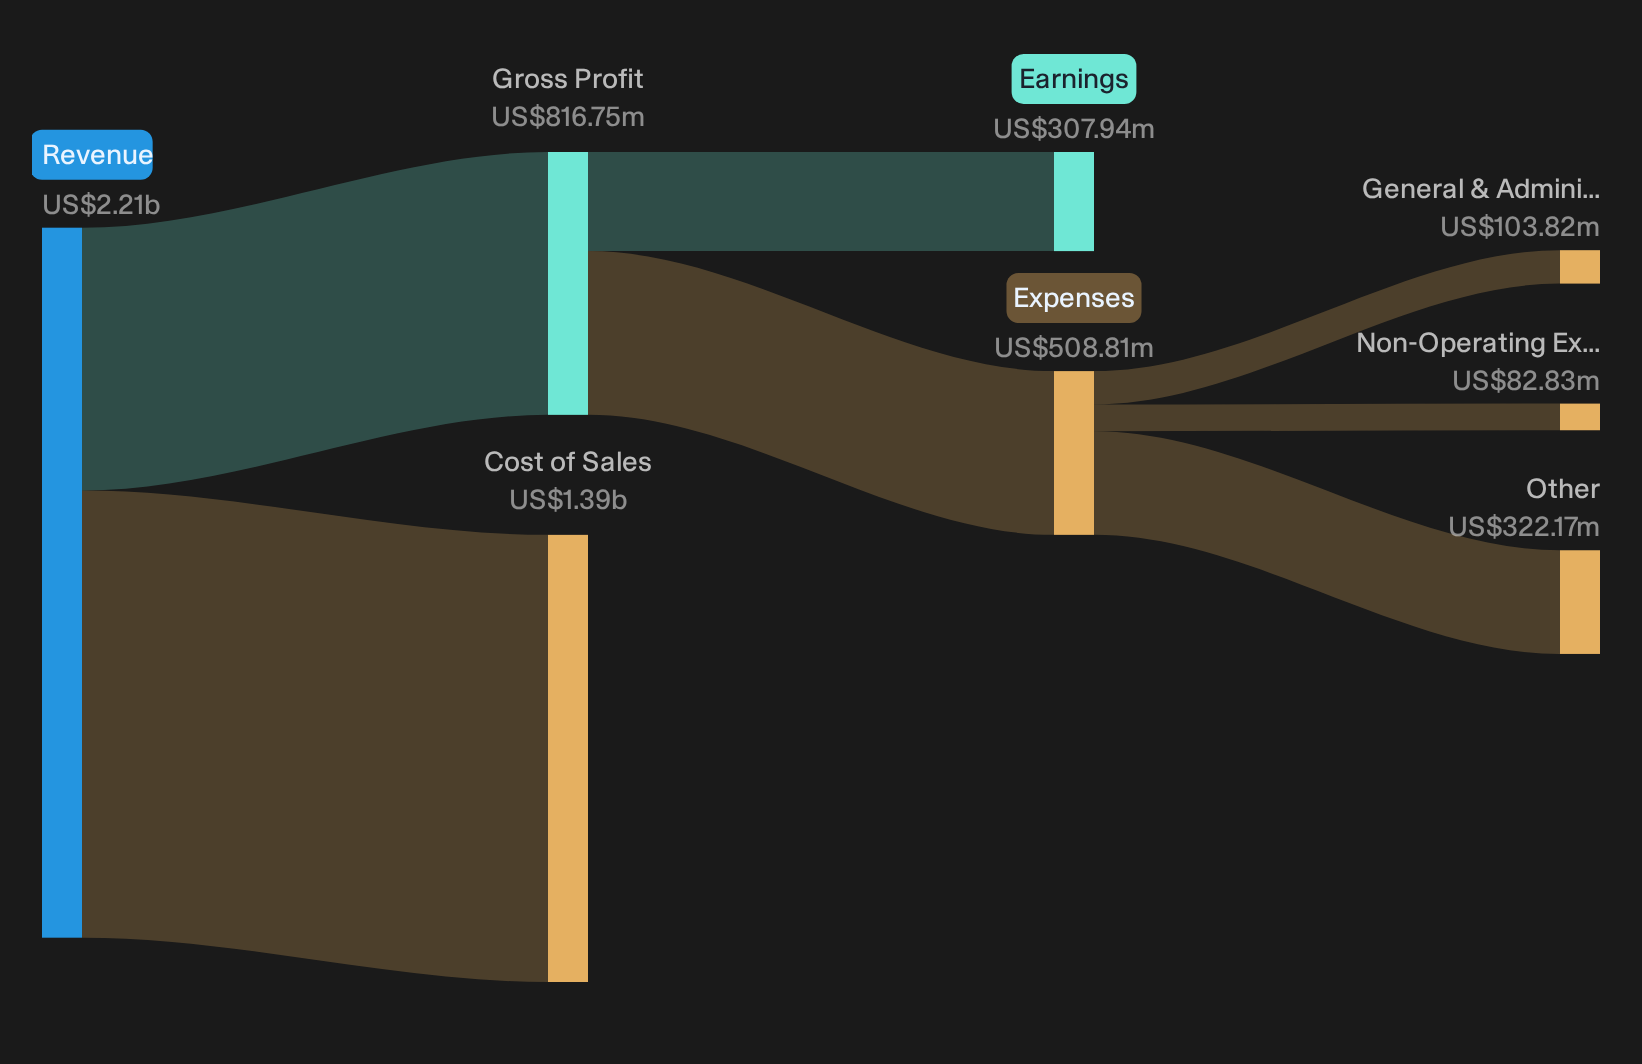
ARLP’s Hybrid Cash Engine Thesis On Trial
Alliance Resource Partners is often framed as a coal and royalties cash machine that can keep funding distributions through cycles.
"The main thing that has to go right is that Alliance Resource Partners continues to translate its coal mine productivity gains and expanding royalty volumes into sustained free cash flow while keeping leverage low."
Q3 ticks key boxes. Coal volumes rose to 9.3 million tons with lower segment expense per ton, while Oil & Gas Royalties posted record US$59.8 million revenue. Adjusted EBITDA attributable to ARLP reached US$233.9 million and net leverage stayed under 1x, even after funding AllDale III & IV.
Testing ARLP Risk Concerns Against Q3 Reality
The main pushback on Alliance Resource Partners is that normalization and asset noise could blunt this resilience story.
"The fall in average coal sales price per ton to US$54.87 in Q2 2026, as higher priced legacy contracts at Tunnel Ridge and Mettiki rolled off, shows that pricing is already normalizing. A continued shift into lower priced index linked contracts could limit revenue growth and compress net margins, even if volumes hold near current guidance."
Q3 coal pricing per ton slipped again to US$53.93, yet segment adjusted EBITDA rose on better costs and 7.4% higher tonnage. Digital assets swung to a US$16.5 million gain after earlier fair value losses, which underlines earnings volatility but not a hit to underlying coal or royalty trends this quarter.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Quiet Cash Engines
Alliance Resource Partners just showed how a steady business can still surprise when the income statement does the talking. The real opportunity could sit in stocks that look mispriced before the crowd catches on.
- Company 1 - 27% below our estimate - threads its hardware and software into the infrastructure moving, securing, and managing intensifying AI data traffic.
- Company 2 - 19% below our estimate - scales high voltage construction as hyperscale data center projects expand its backlog and tighten working capital.
- Company 3 - 23% below our estimate - embeds AI copilots and developer tools into existing cloud and productivity contracts for enterprise workflow upgrades.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com