
Soriana Climbed While Sales Fell
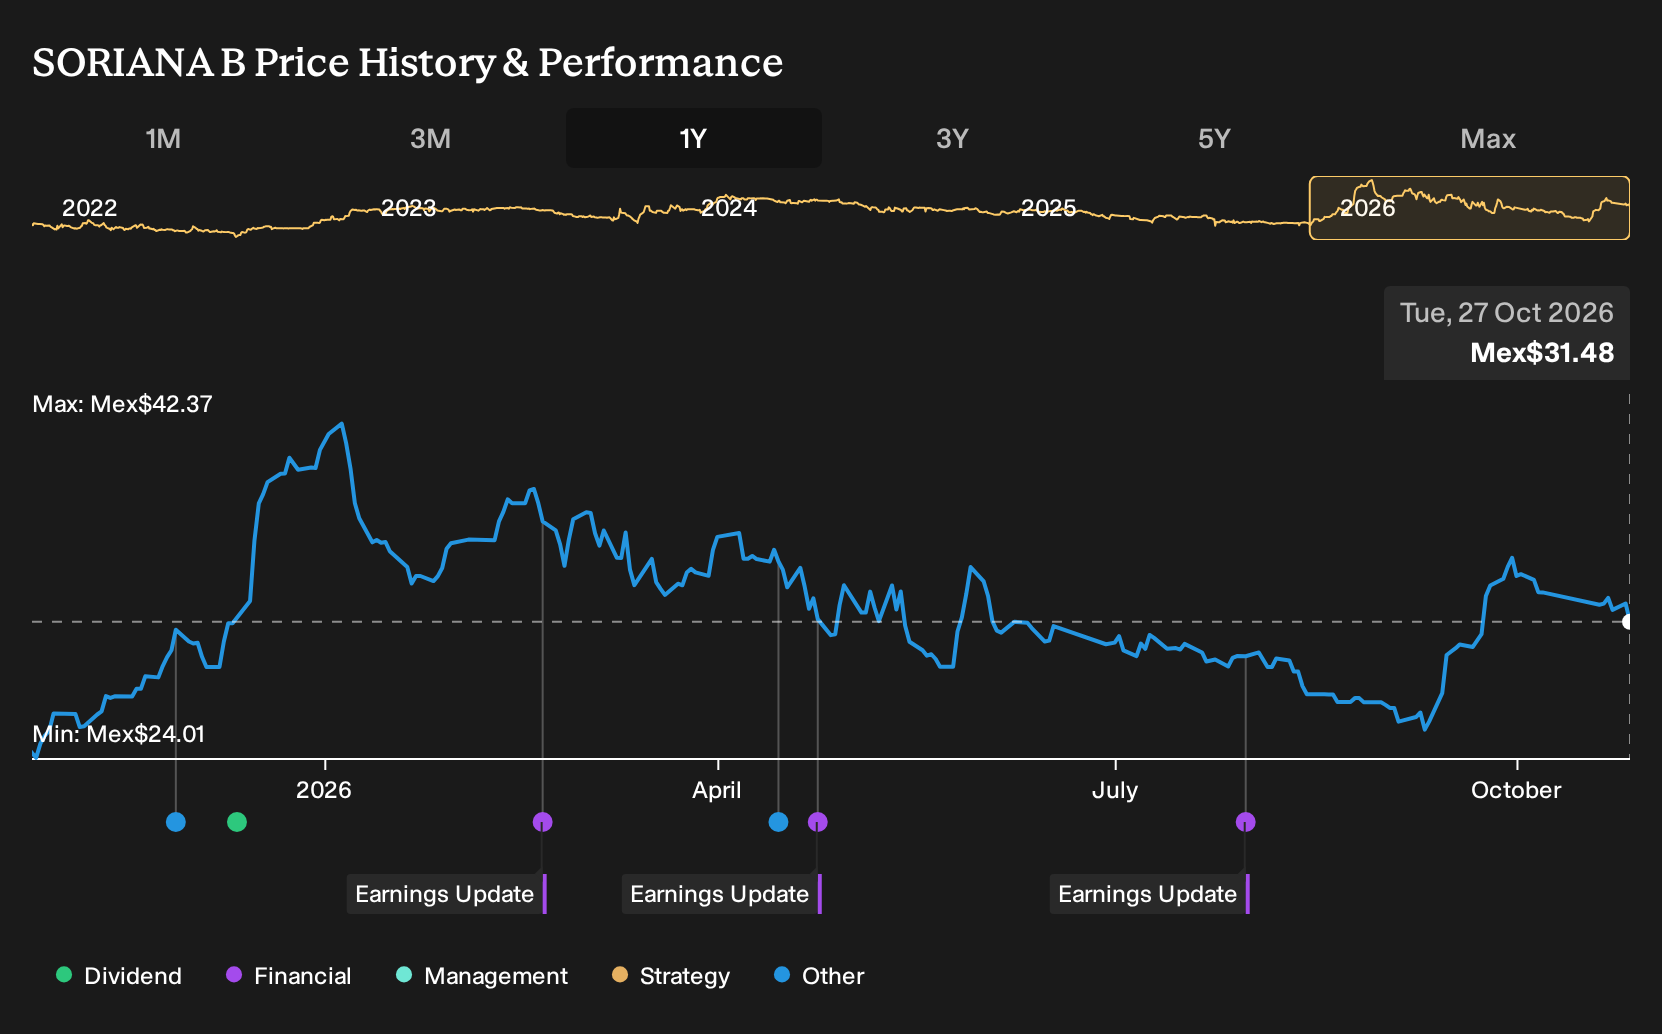
If you had bought Organización Soriana S. A. B. de C. V on 26 October 2025 and simply sat tight, the past year looks very different today. Investors who held Organización Soriana S. A. B. de C. V over the past year are up 37.3%, including dividends. That outcome now sits beside fresh numbers, with revenue at MX$45,809.998m in Q2 2025 versus MX$43,558.932m in Q2 2026 and net income excluding extra items at MX$736.048m versus MX$1,082.286m, plus a net margin shift from 1.6% to 2.5%. If that decision were in front of you again, how much weight would you really give to early worries about weak traffic and digital execution compared with hopes pinned on private label, loyalty, and home improvement expansion?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Organización Soriana S. A. B. de C. V harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Stories Investors Had To Weigh On Organización Soriana S. A. B. de C. V
The shares cost MX$24.88 at the start of the period, and investors in Organización Soriana S. A. B. de C. V had to decide which story they trusted more.
The bullish narrative put fair value at MX$33, or 33% above the start price, based on expectations that investment in private label, digital sales, loyalty and the Sodimac home improvement venture would lift net margins and support higher earnings.
The bearish view set fair value at MX$19, or 24% below the start price, and focused on risks that weak digital execution, intense competition and a concentrated store footprint could compress profit margins toward 1.5% and limit revenue growth.
What The Results Changed For Organización Soriana S. A. B. de C. V
The clearest signal came from profitability. Organización Soriana S. A. B. de C. V reported net income excluding extra items of MX$1,082.286m in Q2 2026 versus MX$736.048m a year earlier, with net margin moving from 1.6% to 2.5%. Revenue slipped to MX$43,558.932m from MX$45,809.998m, so the evidence cut both ways on the earlier growth-focused bullish narrative.
The episode centered on one assumption investors can test in any situation. When an investment thesis relies on improved economics, it can be useful to track net margin and absolute profit in relation to that thesis, even if revenue trends in a different direction.
What Today's Soriana Price Already Assumes
Organización Soriana S. A. B. de C. V now trades at MX$32.49. The selected Narrative puts Fair Value below that level and frames the gap around whether margin gains from private label, rentals, and automation can continue to offset cost pressure and softer store productivity.
A buyer today is effectively assuming those higher margin channels and efficiency projects can support earnings over time. How does that compare with the risk that weaker same store trends and rising operating expenses continue to weigh on profitability and revenue?
"The current valuation suggests the share price already reflects successful margin expansion from private label, real estate rentals, automation, and loyalty driven sales mix, despite recent revenue pressure and higher operating expenses."
One Narrative disagrees with today's price. → See where this Narrative says Organización Soriana S. A. B. de C. V should trade
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 42% below our estimate - sells hardware-agnostic oncology software that integrates into competing treatment machines and workflows.
- Company 2 - 31% below our estimate - targets AI data centres standardising on its GPU hardware and proprietary software stack.
- Company 3 - 25% below our estimate - builds antibiotic bone grafts surgeons repeatedly choose as additional medical applications gain approval.
That is three of the list. See the full list of 207 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com