
Rambus (RMBS) Stock Price Cools Despite Record Q3 Earnings
Rambus stock eased 1.6% to US$88.91 today, extending a weak month for the shares, just as it posted another quarter of record results for Q3 2026. The immediate price reaction looks cautious, yet the headline is hard to ignore. Revenue reached US$218.3m and non GAAP earnings per share came in at US$0.84, both powered by demand tied to artificial intelligence infrastructure.
Short term traders are focused on a soft tape and high P/E multiples. Longer term investors are watching a different story, one built around product momentum, rich margins and a multi year AI memory cycle.
Love the record Rambus print and AI tailwind but uneasy about paying up for rich P/E multiples in a choppy tape? Stress test that instinct against a curated set of resilient compounders in our 30 resilient stocks with low risk scores
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$218.3m vs. US$178.5m (up roughly 22% year on year)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): US$74.6m vs. US$48.4m (up roughly 54% year on year)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.69 vs. US$0.45 (up roughly 54% year on year)
- Net Profit Margin, Excl. Extra Items (Q3 2026 vs Q3 2025): about 34.2% vs. about 27.1% (margin higher year on year)
Rambus is already pointing investors to 2027 AI upside. Ask Charlie what Rambus sees driving 2027 AI demand.
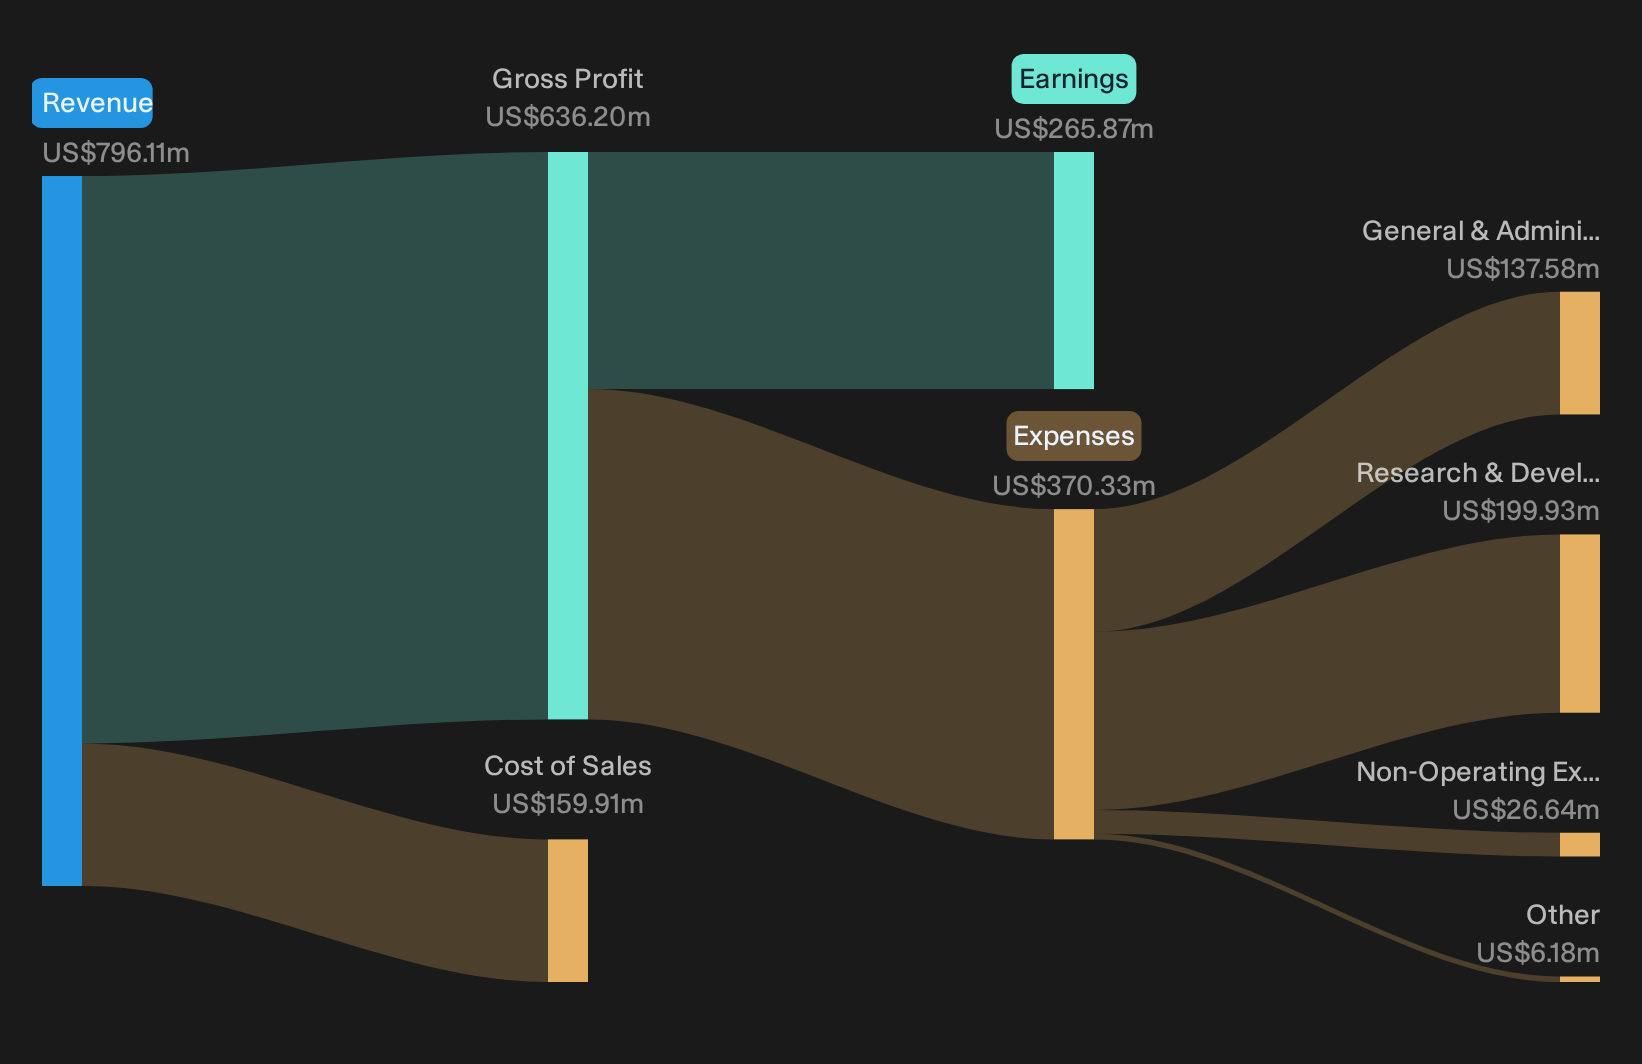
Rambus earnings: product mix starts to do the talking
Rambus bulls argue that the AI buildout should translate into broader product breadth and sturdier profitability over time.
"New companionship products such as DDR5 PMICs and client chipsets are gaining adoption, moving from low single digit to upper single digit and toward double digit contributions of product revenue."
Q3 shows that thesis moving from slideware to execution. Product revenue reached about US$114m and now makes up just over half of sales, with contract and other revenue also climbing. Non GAAP product gross margin sits around 60% and total Q3 operating cash flow hit US$102m. For a portfolio that is intended to lean on mix and capital efficiency, those are important milestones hit.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Rambus bear case: margin strain and inventory risk linger
Bears worry that Rambus overbuilds supply just as AI demand cools and DDR5 server ramps disappoint.
"Ongoing tightness in back end capacity and longer lead times, combined with Rambus plans to build inventory, create a risk that sudden changes in server or AI demand leave the company with less productive stock. This could compress gross margin and near term earnings."
Q3 shows that concern is not fully resolved. Inventory increased by about US$12m and management plans further builds. Product gross margin sits near the low end of the 60% to 63% band, with supply chain costs still a drag. Record revenue and strong EPS do not yet erase the margin and utilization question.
Hunt For Quiet Pricing Gaps
Rambus just showed how a strong operational story can still meet a cautious share price. The real opportunity lies in spotting stocks that could be undervalued before the market closes the gap.
- Company 1 - 42% below our estimate - focus on larger LED infrastructure projects as software, services and streamlined factories handle more delivery.
- Company 2 - 19% below our estimate - scale a teahouse network as overseas locations expand GMV and membership programs deepen customer ties.
- Company 3 - 31% below our estimate - convert a record funnel of regulated-sector manufacturing wins into sustained programs while maintaining margins and cash discipline.
Those are three of them. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com