
Centrus Energy (LEU) Stock May Trade Above Fair Value As Supply Chain Deal Closes
Centrus Energy has gone from a sharp multi year share price climb to heavy declines over the past year, which puts fresh attention on what investors are really paying for its earnings today. With the stock recently closing at US$109.42, the key issue is whether that tag still lines up with what the business is generating and expected to generate in profit terms.
- Over the last 3 years, Centrus Energy has delivered a 106.2% share price gain. As a result, a lot now rides on whether that past move is backed up by the durability of its earnings power.
- The US$116 million acquisition of Westerman Holdings, partly funded with equity, can reshape Centrus Energy's cost base and revenue mix. This feeds directly into how dependable and scalable its future earnings may be.
- The analysts covering Centrus Energy have run their own numbers. See what analysts think Centrus Energy's shares could be worth.
The issue now is whether Centrus Energy's current share price is adequately explained by the level and quality of the earnings that investors can reasonably link to the business today.
If you are questioning whether Centrus Energy's earnings justify its current P/E, it can help to compare that same earnings lens across 29 high quality undervalued stocks.
Has Centrus Energy Run Too Far on Earnings?
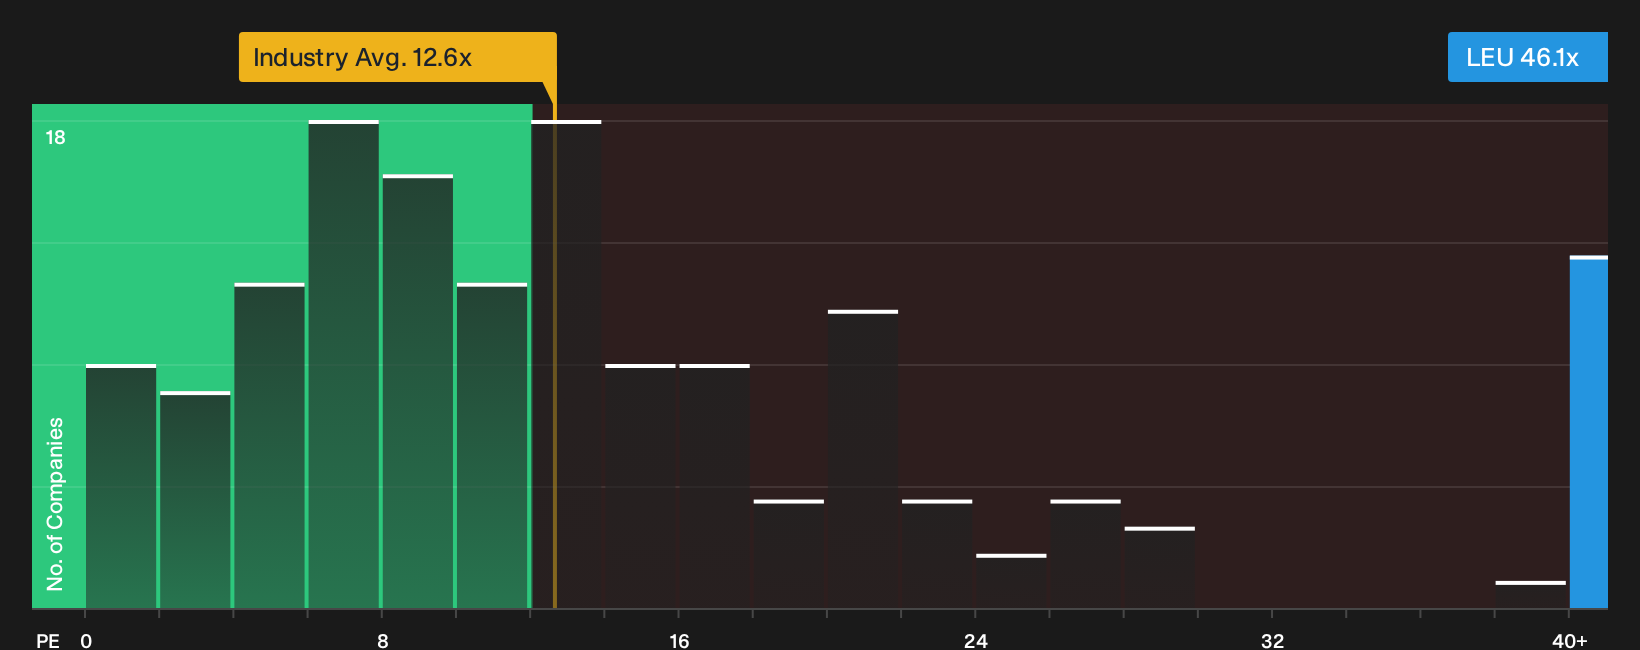
P/E suits Centrus Energy because earnings remain the main hook for how investors value its uranium enrichment and now broader manufacturing operations. On that yardstick, the shares trade at about 46.1x earnings, which is more than double the Oil and Gas sector average of 12.6x and also well above peers at roughly 21.6x. That is a rich headline multiple for a business still working through a sizeable Westerman integration and a capital intensive supply chain.
The tailored fair P/E benchmark suggests a much lower ratio would usually line up with Centrus Energy's mix of growth prospects, margins, scale and risk. As a result, the model flags the stock as overvalued on this framework. Because the gap is very wide, the fair multiple is better read as a caution signal that the valuation leans heavily on optimistic expectations rather than a precise target. Because the Westerman deal is expected to lift adjusted earnings, the current P/E also bakes in a lot of that potential uplift already. Explore the numbers behind Centrus Energy's P/E valuation.
The Centrus Energy Narrative: What Would Justify Today's Price?
Narratives for Centrus Energy pick up where the valuation puzzle leaves off and spell out which earnings, margin and growth assumptions would need to hold for the stock to be worth far more or far less than the current price. Each narrative treats fair value as a specific thesis about how Centrus Energy's business might develop. You can revisit this thesis over time as new information and results come through on the Community page.
One of the top community narratives on Centrus Energy: 42% undervalued
"Centrus Energy (LEU) offers the most direct public-market exposure to U.S. HALEU production, a critical bottleneck for advanced nuclear deployment..."
Discover why this Narrative puts Centrus Energy at 42% undervalued.
One more Centrus Energy check before you stop at the share price
Before you focus only on what Centrus Energy earns and what the market pays for it, you also need to look at who sets the course and how their incentives are structured. See who runs Centrus Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com