
Brown & Brown (BRO) Stock Price Faces Q3 Earnings Margin Squeeze
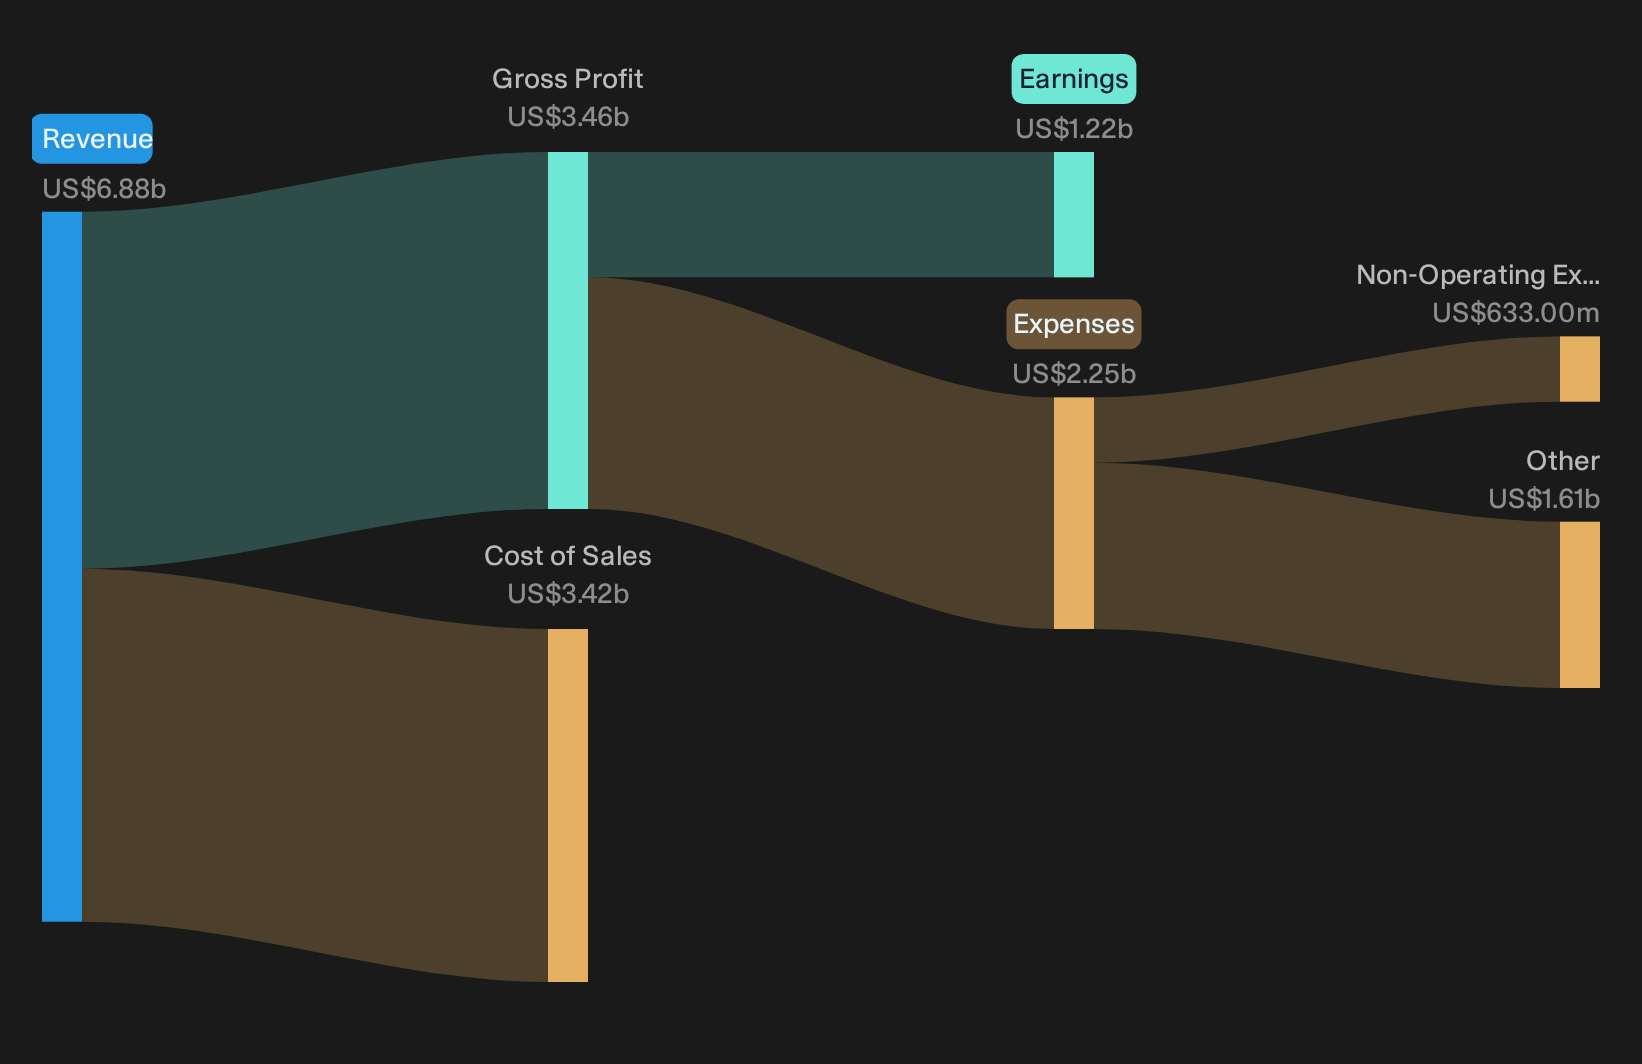
Brown & Brown just reported Q3 2026 and the market fired first, asked questions later. The stock dropped almost 5% to US$67.55 today, even though the headline print showed revenue of about US$1.7b and adjusted earnings per share of US$1.07. Traders fixated on pressure in profitability, with adjusted EBITDAC margin compressed to 34.6%. The emotional read is clear. Investors sold on a margin scare while the underlying earnings line moved only modestly, creating a sharp split between share price frustration and a more mixed, nuanced quarter underneath.
Love Brown & Brown’s steady top line but uneasy about that margin squeeze? Benchmark it against peers in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$1,725 million vs. US$1,550 million (+11.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$240 million vs. US$225 million (+6.7%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.73 vs. US$0.68 (+7.4%)
- Adjusted EBITDAC (earnings before interest, taxes, depreciation, amortisation and COVID-related costs) Margin (Q3 2026 vs. Q3 2025): 34.6% vs. 36.6% (margin compressed by 2.0 percentage points)
Earnings tell one story, but investors who care about what they are really paying for Brown & Brown look hard at the cash that actually comes through the door. If you focus on Brown & Brown's cash flows alone, the stock could be a striking 49% undervalued.
Brown & Brown: Bullish Automation Story Meets Mixed Reality
The upbeat narrative around Brown & Brown hinges on AI freeing people to drive more business while protecting profitability.
"Brown & Brown is rolling out AI enabled submission, policy checking and billing tools that are already saving tens of thousands of hours a year and automating more than 25% of the submission process in many programs, which can free producers and underwriters to handle more volume and support future organic revenue growth and operating margin resilience."
Q3 shows only modest organic expansion at 1.2% overall, with Retail organic growth at 2.6% and Specialty Distribution slightly negative. EBITDAC margin compressed 200 bps to 34.6%. Efficiency claims are credible, but this quarter suggests AI is, so far, cushioning pressure rather than clearly lifting growth or profitability.
Brown & Brown: Producer Risk Still Bites Despite Accession
The bear story focuses on people risk and the possibility that churn swamps all the clever tools and deals.
"Ongoing producer departures to a rival broker and the related customer losses, which management currently estimates at tens of millions of dollars of annual revenue, could persist or widen and offset benefits from AI driven efficiency and Accession if they lead to weaker Retail organic revenue and softer net margins."
Retail organic growth of 2.6% and a slightly wider Retail margin hint that producer disruption is manageable for now. The pressure sits in Specialty Distribution, where organic revenue slipped and margins eased. Combined with group margin compression and a 5% share price drop, the risk is not disproved, just partly contained.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Stories
Brown & Brown just reminded investors that headline results and share price reactions do not always move in lockstep. The real opportunity is finding stocks that could be undervalued before the market adjusts to the underlying performance.
- Company 1 - 34% below our estimate - builds AI superclusters that a leading model developer uses to expand cloud infrastructure capacity.
- Company 2 - 42% below our estimate - sells tracker and control systems that solar developers deploy after securing constrained grid interconnection access.
- Company 3 - 23% below our estimate - embeds AI copilots into productivity, coding and business software that enterprises integrate into established workflows.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com