
What Altius Minerals (TSX:ALS)'s Royalty Revenue Outlook Means For Shareholders
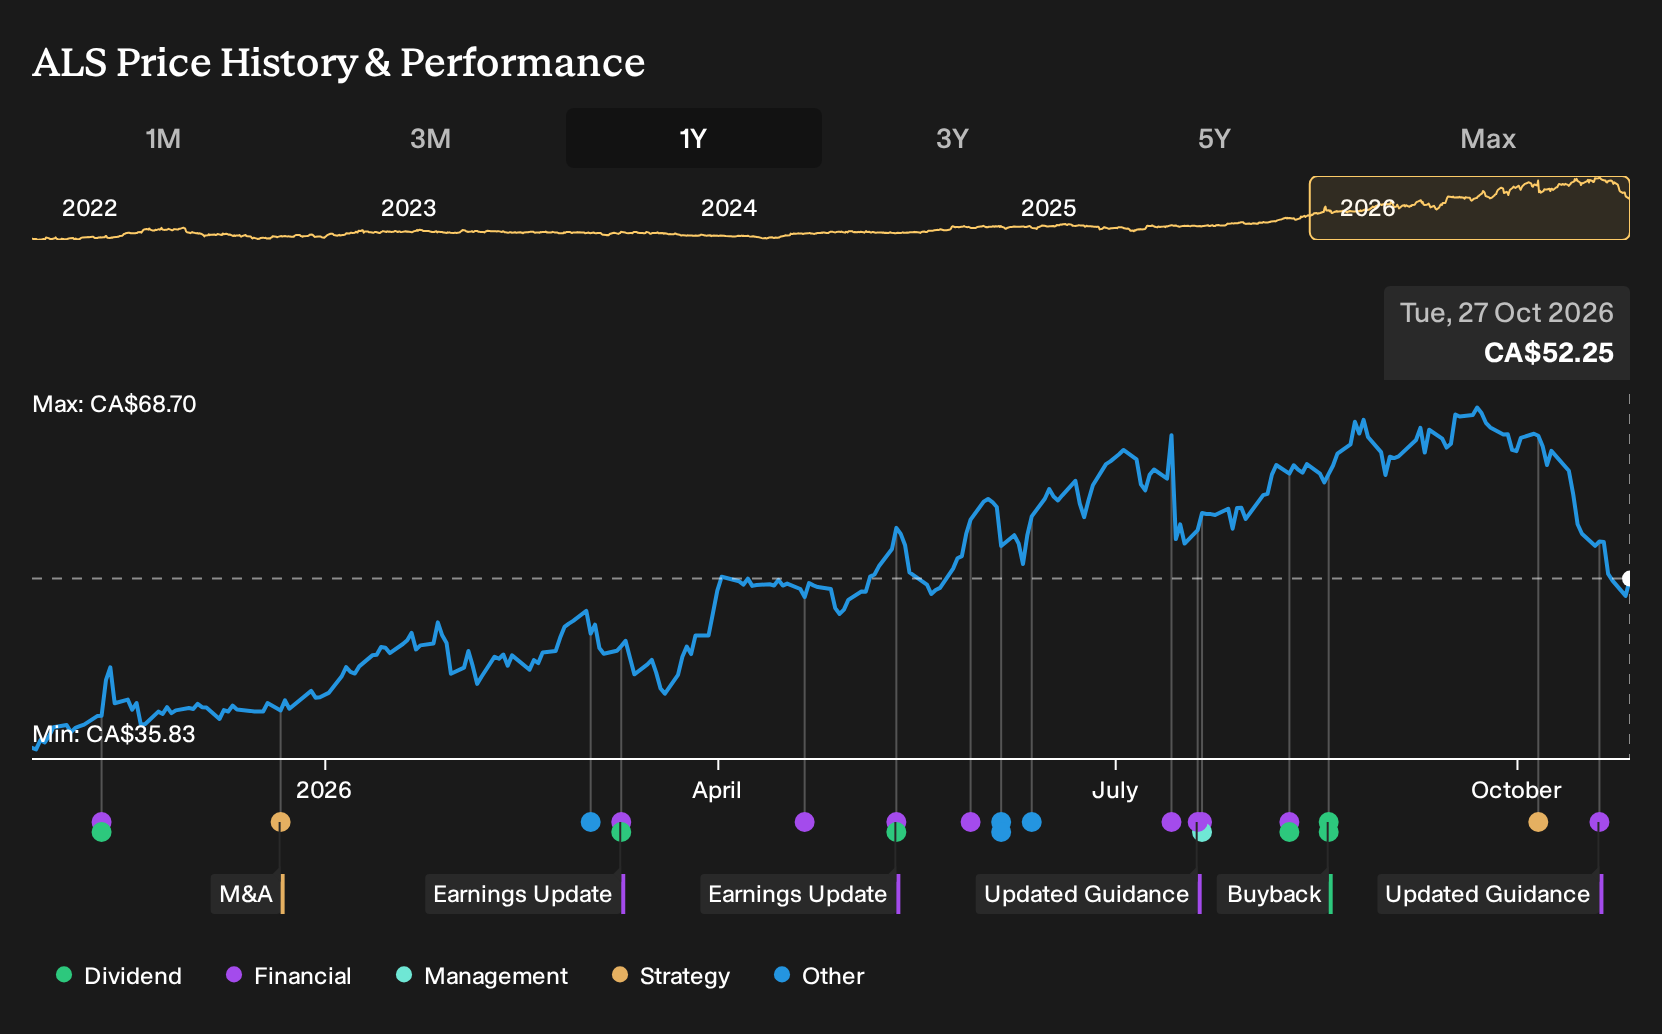
- Altius Minerals reported that third quarter 2026 attributable royalty revenue is expected to be about $33.2 million, compared with $21.4 million in the same period of 2025.
- The updated outlook highlights how Altius Minerals' royalty model can translate changes at underlying mines and projects into a different revenue mix for the parent business.
- We will now look at how this higher projected royalty revenue may influence Altius Minerals' existing investment narrative and risk balance.
Scan royalty-focused peers that could see similar shifts in cash flow by reviewing our hand-picked 9 high quality undiscovered gems aligned with moves like Altius Minerals' latest guidance.
Altius Minerals Investment Narrative Recap
To own Altius Minerals, you need to be comfortable with a royalty portfolio that leans on mature potash operations, several large copper and gold projects, and a growing renewable power book. The Q3 2026 guidance for CA$33.2 million of royalty revenue indicates that producing assets are currently doing the heavy lifting, but it does not change the reliance on counterparties to advance long-dated projects.
In the near term, the key swing factor is how quickly development royalties such as Chapada, CAMI, and Curipamba progress into higher volumes. The main risk remains that operators delay capital or permits, while Altius Minerals carries a large liquidity pool that could sit idle if attractive new royalties or buybacks do not materialize soon.
The guidance itself is the main operational update, because it outlines what the existing portfolio can generate without any major new deals or mine start-ups. When you set that against analyst expectations for softer earnings over the next few years, the question becomes how much of current revenue is tied to higher commodity pricing and non-cash items versus sustainable run-rate volumes.
Altius Minerals is also flagged as having a high level of non-cash earnings and a forecast decline in profit, even while revenue is expected to grow about 18.3% a year. This mix puts the focus on cash conversion, the quality of underlying mine performance, and whether management can deploy its sizeable liquidity into long-life royalties that offset any future compression in accounting earnings.
Altius Minerals' analyst narrative points to forecast revenue of CA$155.6 million and consensus earnings of CA$97.7 million by 2029, implying revenue growth of 35.0% per year and an earnings decline of about CA$197.2 million from current earnings of CA$294.9 million.
Uncover why Altius Minerals' fair value indicates a 27% potential upside to its current price, a discount that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate take on Altius Minerals leans on lithium royalties as the big swing factor. Bullish analysts were pencilling in CA$191.4 million of future revenue and CA$89.9 million of earnings by 2029, and a P/E of 79.1x, before this Q3 2026 guidance. That is a far more optimistic story. Consider using this guidance as a cue to compare those projections with your own expectations.
Explore 2 other Altius Minerals fair value estimates, including one that suggests as much as 32% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Altius Minerals research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Altius Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Altius Minerals' overall financial health at a glance.
Looking For More Ideas Beyond Altius Minerals?
If the latest Altius Minerals numbers have sharpened your thinking about royalties and cash flow quality, it can help to line that up against other opportunities that share some of the same traits. Use the Simply Wall St Screener to compare businesses across different balance sheet strengths, income profiles, and risk levels, then decide where Altius fits in your broader watchlist.
- If you prefer resilient businesses with room to reinvest rather than stretching for the highest yield, start with a list of solid balance sheet and fundamentals (7 results) that filters for companies with financial headroom.
- If your priority is capital preservation with fewer shocks along the way, consider a 8 resilient stocks with low risk scores that narrows the universe to stocks with lower risk scores.
- If you are income focused and want yield backed by fundamentals, use our 3 dividend fortresses to zero in on companies offering high payouts with more durable profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com