
Blue Ridge Bankshares (BRBS) Q3 Results Reflect Revenue Collapse And Losses
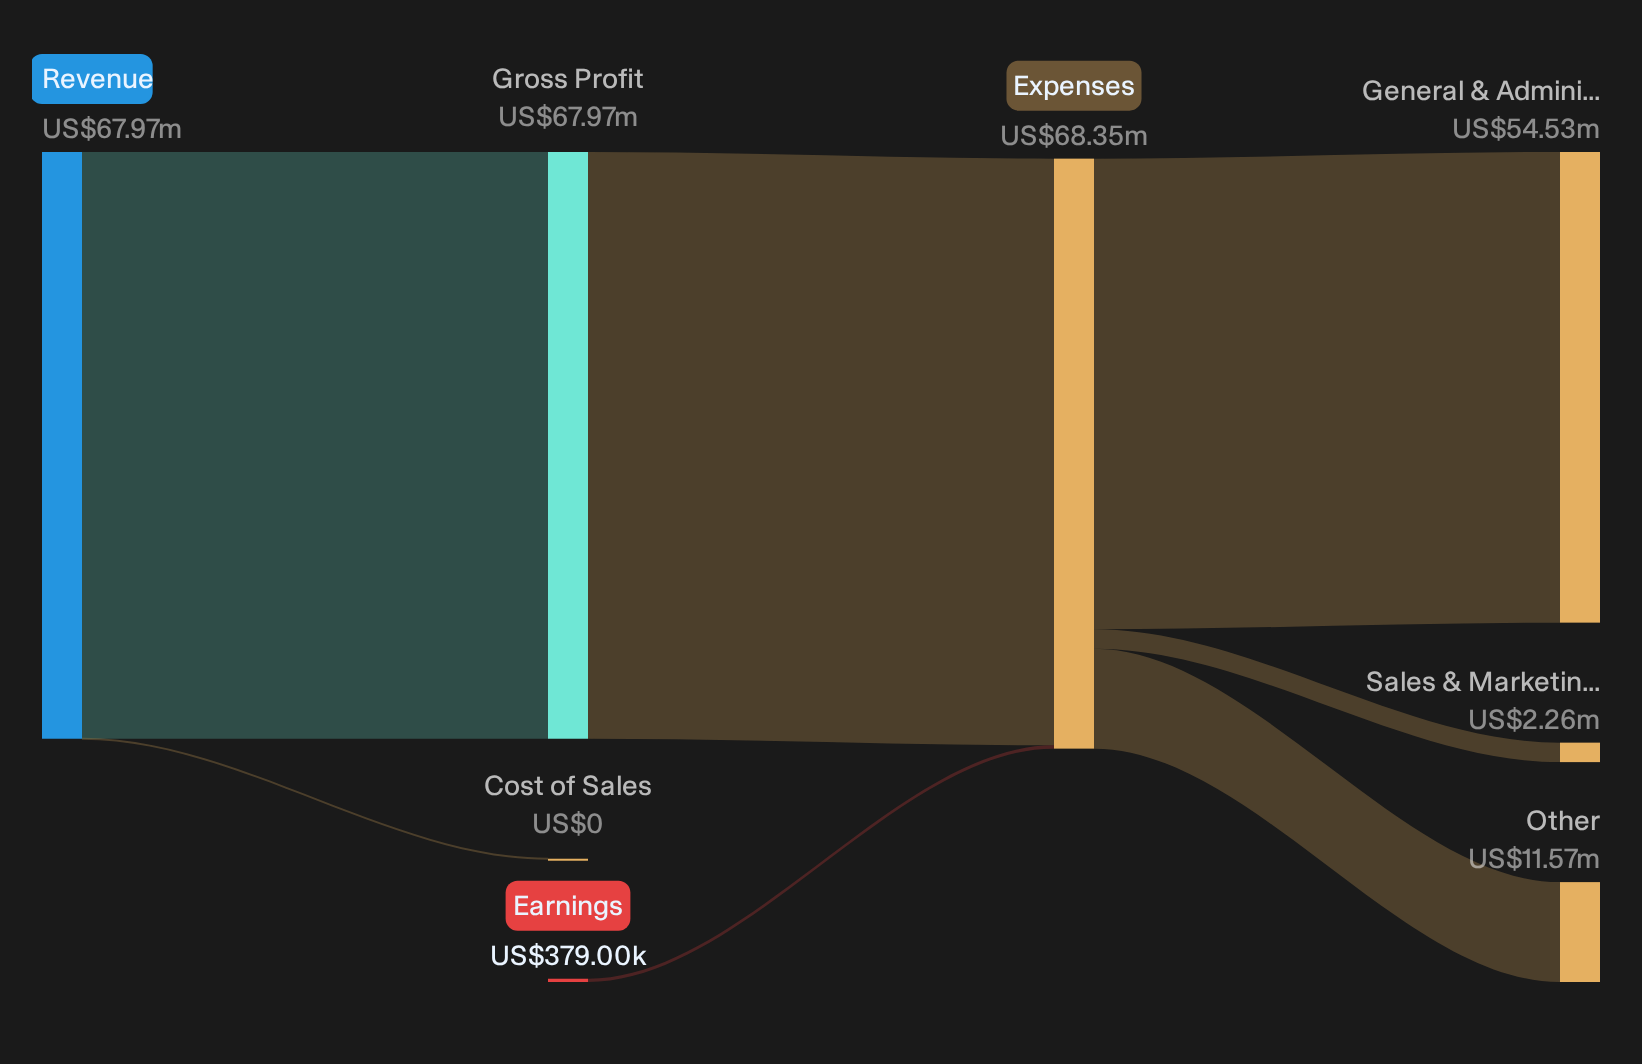
Blue Ridge Bankshares just reported Q3 2026, and the headline is simple. Revenue shrank to US$11.6 million while the bank swung to a net loss of US$4.2 million. Yet the stock barely flinched, slipping only 0.8% on the day.
That muted move hides a sharper story. You are looking at a regional lender already unprofitable over the past year and now showing fresh pressure on earnings and credit quality. Price action is acting calm. The income statement and balance sheet read more like a warning light than a shrug.
Concerned that Blue Ridge Bankshares is sliding deeper into losses while credit quality weakens? Consider benchmarking it against regional lenders with stronger balance sheets and earnings resilience in our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$11.55 million vs. US$27.54 million (sharp decline in quarterly revenue)
- Net Income/Loss (Q3 2026 vs. Q3 2025): loss of US$4.16 million vs. profit of US$5.60 million (profitability reversed into loss)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.05 per share vs. earnings of US$0.06 per share (per share result moved from profit to loss)
- Net Interest Margin (Q3 2026 vs. Q3 2025): 2.91% vs. 3.6% (compression in lending margin)
Losses rose even as the stock trades above book peers. Ask Charlie what makes Blue Ridge Bankshares worth a premium.
Blue Ridge bullish hopes lean on merger story
For anyone leaning positive on Blue Ridge Bankshares, almost all of the support now sits around the merger and adjusted earnings. Headline revenue roughly halved year on year and the quarter flipped from profit to a US$4.2 million loss. Yet adjusted pre tax profit of US$5.3 million suggests the core franchise can still earn money once merger and severance costs are stripped out. A flat share price reaction, with the stock slipping only 0.8%, hints investors were prepared for messy numbers during this transition.
Bearish case finds plenty of fresh fuel
The harsher view on Blue Ridge Bankshares finds more direct backing in the reported figures. Revenue dropped from US$27.5 million to US$11.6 million and net interest margin slid from 3.6% to 2.91%. Profit turned into a quarterly loss, and provisions for credit losses helped drive that swing. That combination points to pressure on both earnings power and asset quality, even before layering in merger execution risk. Short term share performance has held up, with positive 30 day and 90 day returns, but the operating trend looks fragile.
After revenue compression, a swing to losses and a low allowance for bad loans, it is worth asking whether these strains are isolated or part of a broader pattern. Review the independent risk analysis for Blue Ridge Bankshares which shows 2 important warning signsHunt For Quieter Mispricings
Blue Ridge Bankshares recently highlighted how share price moves can diverge from current earnings pressure. The real opportunity is in stocks that could be undervalued before wider market attention.
- Company 1 - 42% below our estimate - links merchants to digital payment rails in emerging economies as transaction volume shifts toward local methods.
- Company 2 - 27% below our estimate - supplies specialized and foundational semiconductors that manage intensive data movement, storage and processing across modern computing infrastructure.
- Company 3 - 38% below our estimate - runs a device trade-in and refurbishment platform as upgrade cycles incorporate recycling and recommerce practices.
That is three of the list. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com