
Asian Stocks That May Be Trading Below Estimated Value In October 2026
As of October 2026, the Asian markets are navigating a landscape marked by volatility driven by AI investment concerns and rising oil prices, similar to trends observed globally. In this environment, identifying stocks that may be trading below their estimated value can offer opportunities for investors seeking to capitalize on potential market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Thai Credit Bank (SET:CREDIT) | THB23.00 | THB45.73 | 49.7% |
| Smartsens Technology (Shanghai) (SHSE:688213) | CN¥101.63 | CN¥215.82 | 52.9% |
| P&H Tech (KOSDAQ:A239890) | ₩3110.00 | ₩6197.65 | 49.8% |
| PAL GROUP Holdings (TSE:2726) | ¥1479.00 | ¥2922.79 | 49.4% |
| Nissei ASB Machine (TSE:6284) | ¥8000.00 | ¥15771.63 | 49.3% |
| Natural Food International Holding (SEHK:1837) | HK$1.36 | HK$2.80 | 51.4% |
| Kissei Pharmaceutical (TSE:4547) | ¥3825.00 | ¥7679.17 | 50.2% |
| Kingnet Network (SZSE:002517) | CN¥15.18 | CN¥30.64 | 50.5% |
| Henan Mingtai Al.IndustrialLtd (SHSE:601677) | CN¥14.42 | CN¥28.15 | 48.8% |
| ENN Energy Holdings (SEHK:2688) | HK$49.34 | HK$97.34 | 49.3% |
We're going to check out a few of the best picks from our screener tool.
Ever Sunshine Services Group (SEHK:1995)
Overview: Ever Sunshine Services Group Limited is an investment holding company that offers property management services in the People's Republic of China, with a market capitalization of approximately HK$2.78 billion.
Operations: The company generates revenue of CN¥7.01 billion from its property management services in the People's Republic of China.
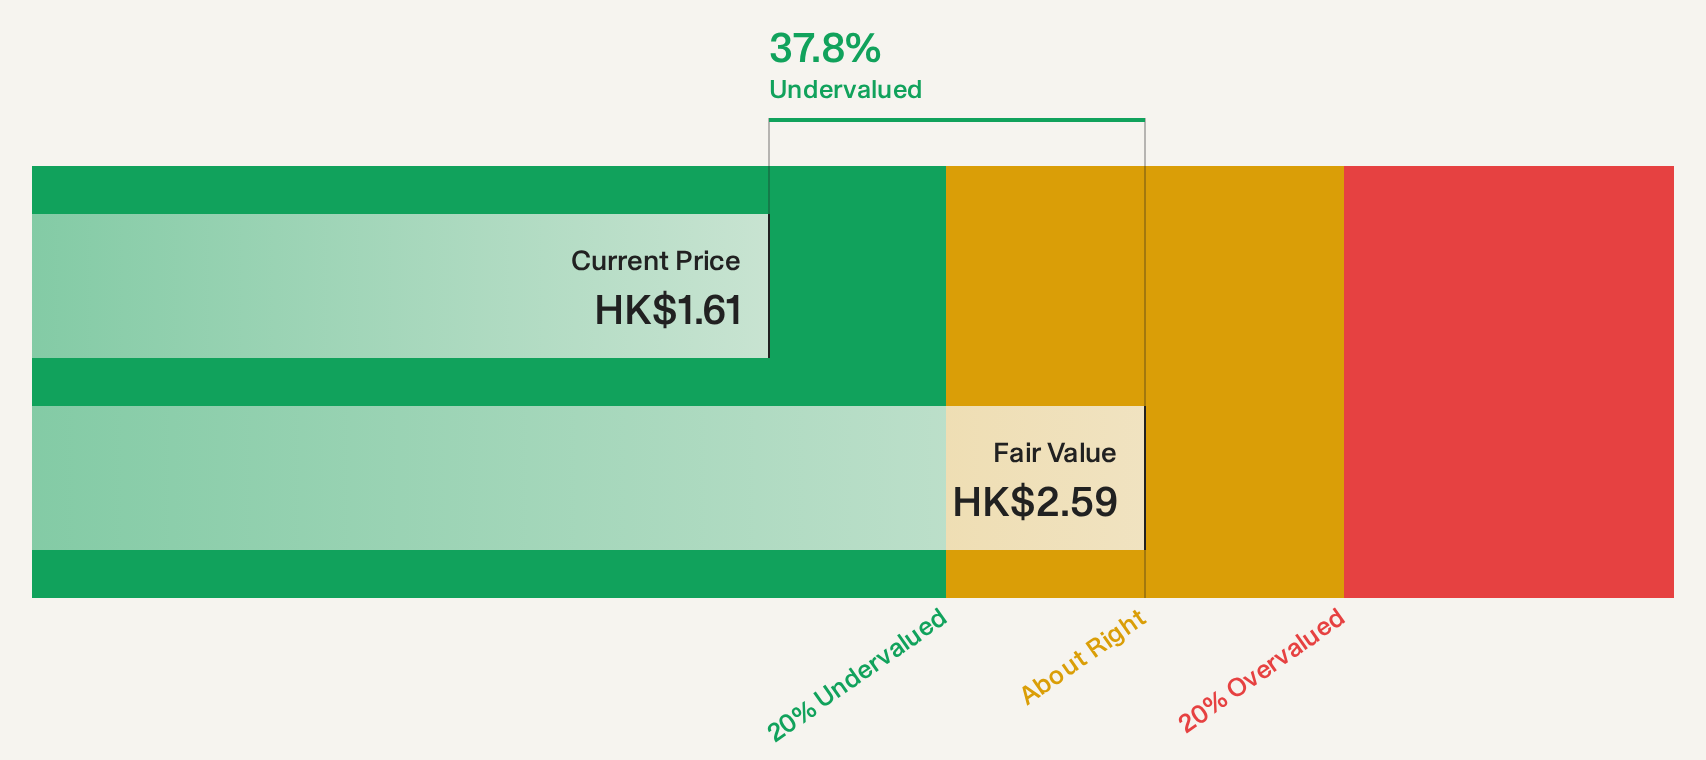
Estimated Discount To Fair Value: 38%
Ever Sunshine Services Group is trading at HK$1.61, significantly below its estimated future cash flow value of HK$2.59, indicating undervaluation. Despite a modest 2.8% earnings growth over the past year and slower forecasted revenue growth compared to the Hong Kong market, it trades 38% below fair value estimates. Recent executive changes may impact strategic direction, while share buybacks and dividend increases reflect positive capital management efforts amidst stable financial performance.
- Insights from our recent growth report point to a promising forecast for Ever Sunshine Services Group's business outlook.
- Get an in-depth perspective on Ever Sunshine Services Group's balance sheet by reading our health report here.
Zibuyu Group (SEHK:2420)
Overview: Zibuyu Group Limited is a cross-border e-commerce company based in China, operating in North America, Asia, Europe, and internationally with a market cap of HK$2.29 billion.
Operations: The company generates revenue primarily from its online retail segment, which amounted to CN¥5.53 billion.
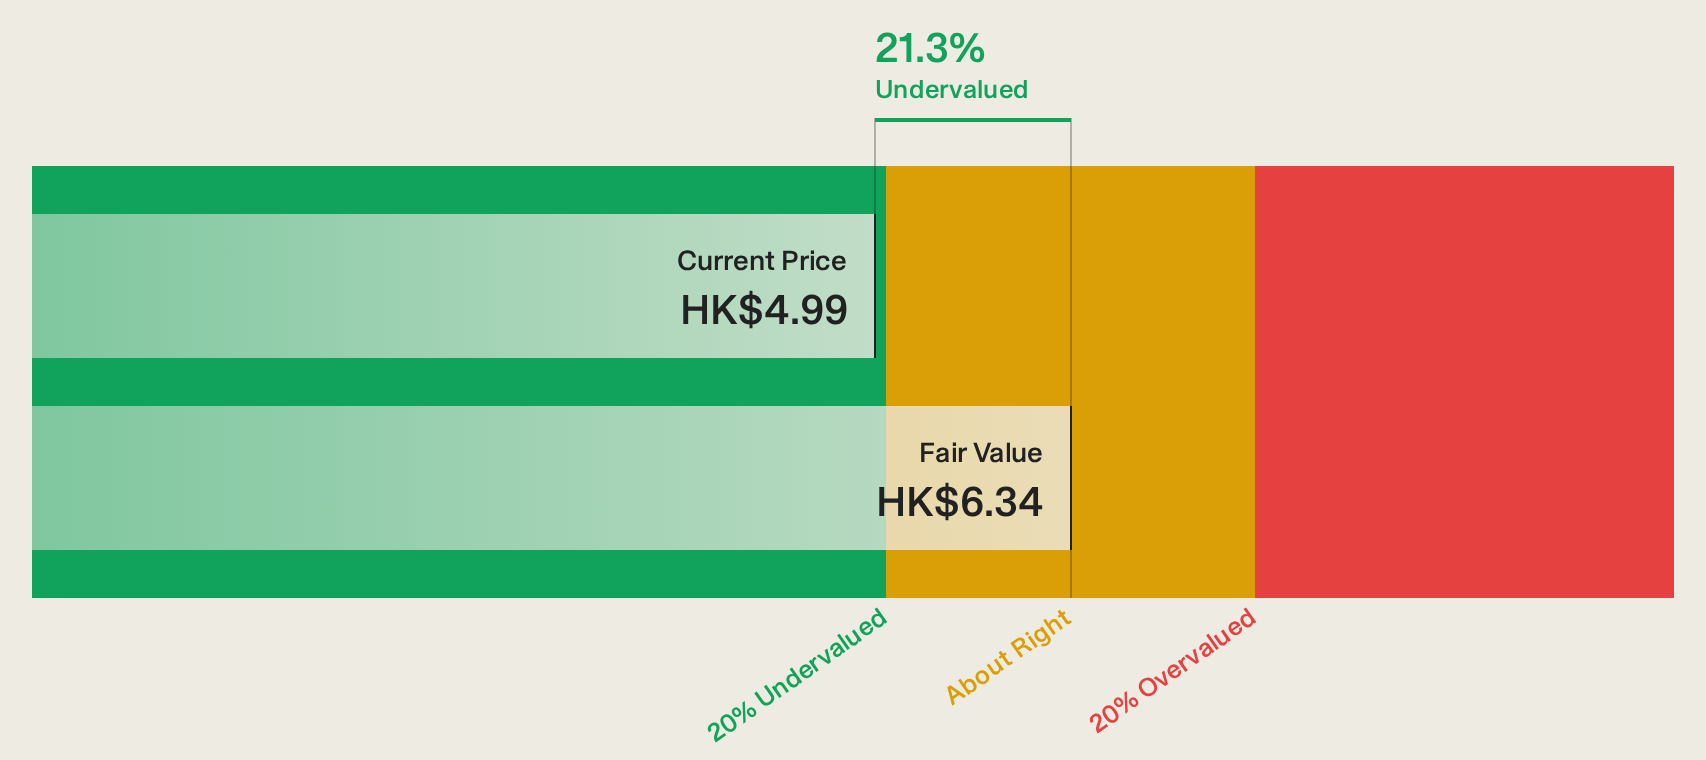
Estimated Discount To Fair Value: 27.6%
Zibuyu Group trades at HK$4.73, below its estimated future cash flow value of HK$6.53, suggesting undervaluation. The company's earnings grew 82.1% last year, with forecasts predicting significant annual profit growth of 24.3%, outpacing the Hong Kong market's 10.5%. Revenue is expected to rise by 25.6% annually, driven by strong performance on platforms like Amazon and TikTok, despite an unstable dividend track record and recent tax adjustments impacting net income slightly.
- Our earnings growth report unveils the potential for significant increases in Zibuyu Group's future results.
- Unlock comprehensive insights into our analysis of Zibuyu Group stock in this financial health report.
SuzukiLtd (TSE:6785)
Overview: Suzuki Co., Ltd. manufactures and sells connectors for car electronics parts in Japan, with a market cap of ¥46.52 billion.
Operations: The company's revenue is derived from segments including Die at ¥2.44 billion, Parts at ¥30.82 billion, Rental at ¥367.96 million, and Machinery and Appliances at ¥7.45 billion.
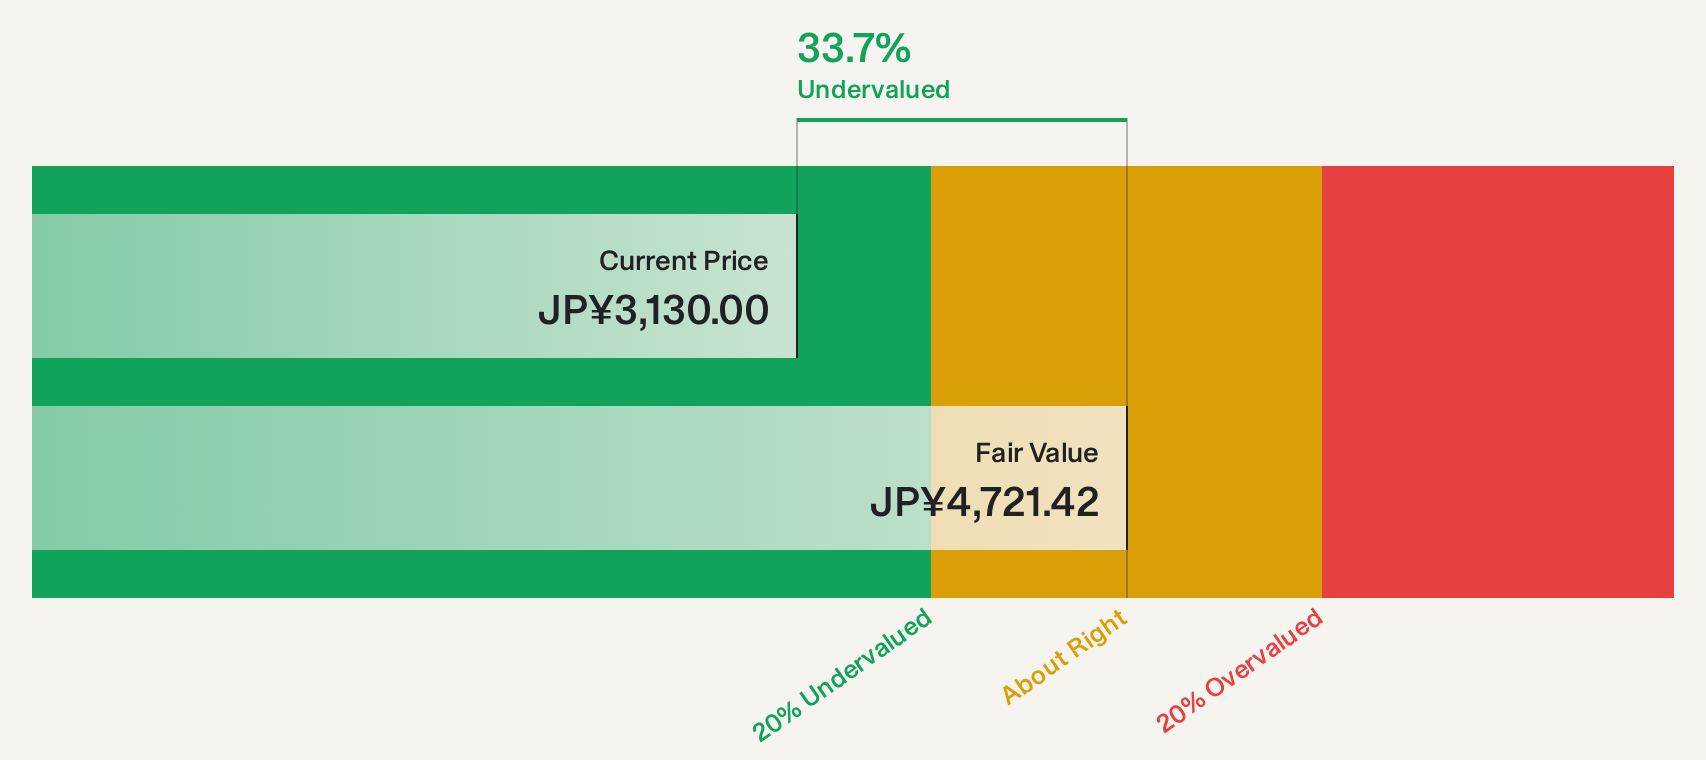
Estimated Discount To Fair Value: 33.3%
Suzuki Ltd. is trading at ¥3,240, below its estimated future cash flow value of ¥4,860.4, indicating it may be undervalued based on cash flows. Earnings grew by 35.8% last year; however, forecasted earnings growth of 7% annually lags behind the Japanese market's 9.4%. Despite a volatile share price and unstable dividend track record with recent decreases to ¥56 per share guidance for fiscal year-end 2027, the company remains a potential value opportunity in Asia.
- Our comprehensive growth report raises the possibility that SuzukiLtd is poised for substantial financial growth.
- Navigate through the intricacies of SuzukiLtd with our comprehensive financial health report here.
Key Takeaways
- Unlock more gems! Our Undervalued Asian Stocks Based On Cash Flows screener has unearthed 181 more companies for you to explore.Click here to unveil our expertly curated list of 184 Undervalued Asian Stocks Based On Cash Flows.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com