
Pharmacy Expansion Questions Put Tandem Diabetes Care Stock Execution In Focus
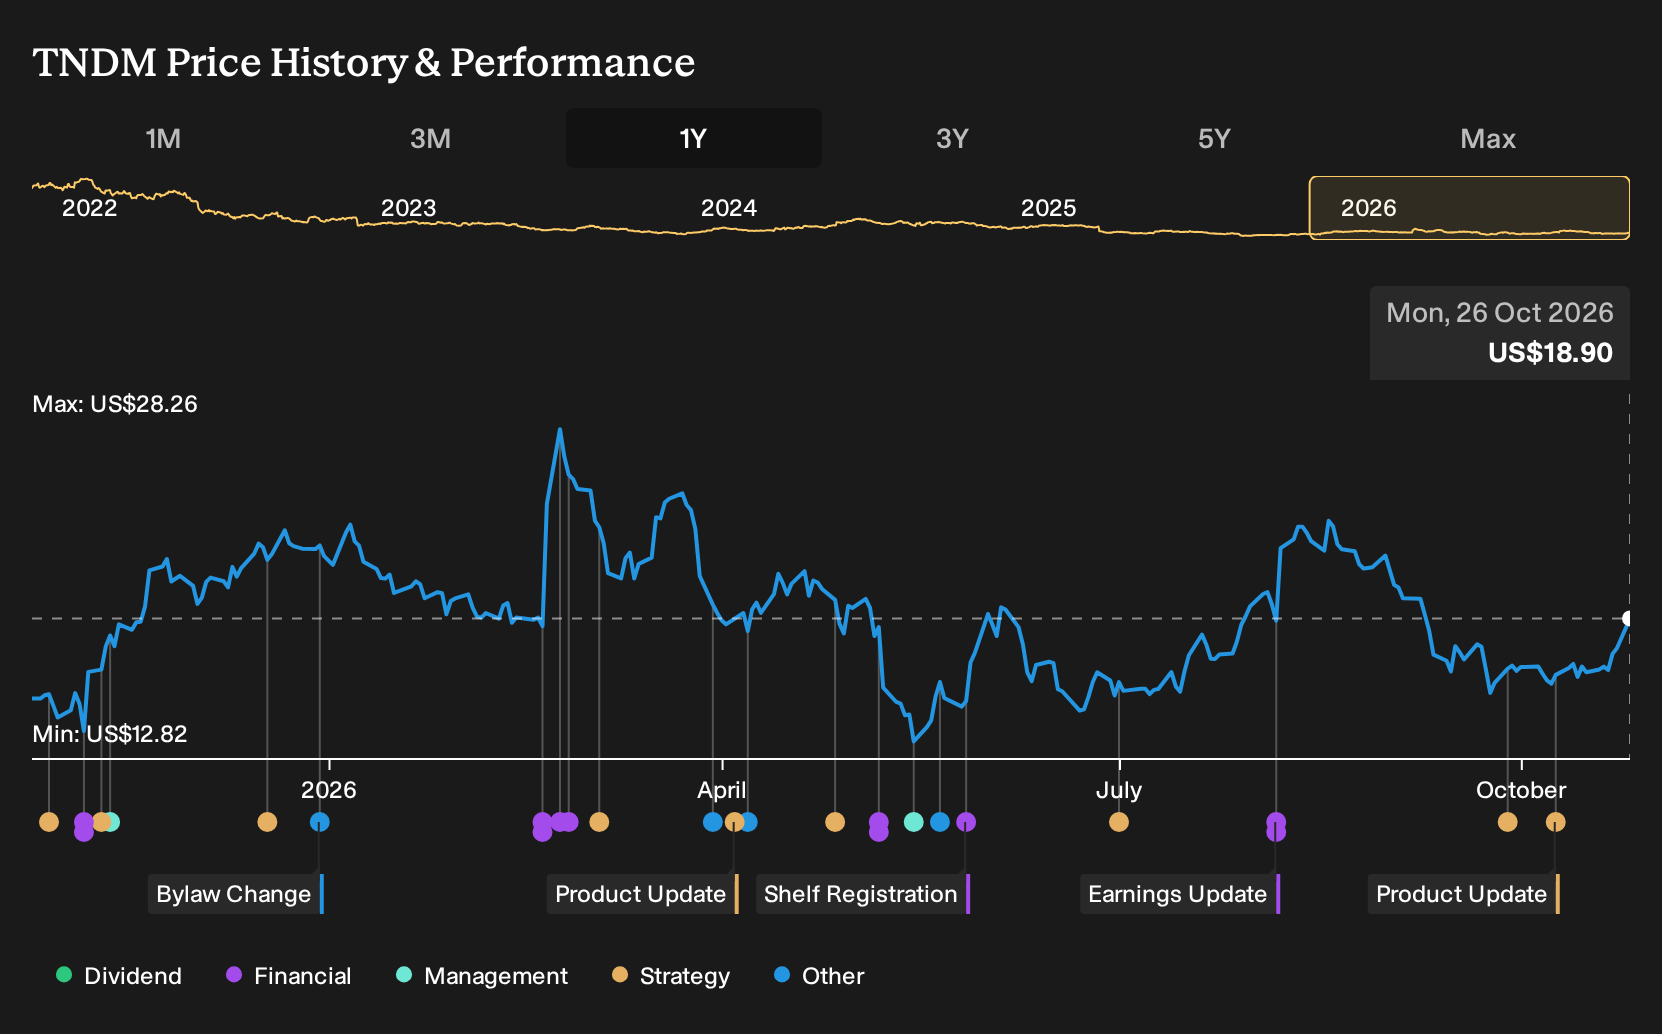
- Tandem Diabetes Care has seen its shares recover from a multi year slump while debate grows over how effectively it can monetize its insulin pump installed base amid pharmacy channel expansion and supply constraints.
- The current valuation reflects a lower price to sales ratio than peers. This puts execution around recurring supply revenues and competitive positioning under a sharper spotlight for investors tracking the durability of the business model.
- We will now explore how Tandem Diabetes Care's investment narrative might shift as investors reassess execution risks around its pharmacy buildout.
Tandem Diabetes Care Investment Narrative Recap
For a shareholder in Tandem Diabetes Care, the big belief is that a growing insulin pump installed base eventually converts into steady, higher margin supply and pharmacy channel revenue. The recent recovery in the share price does not change that core idea. The key short term swing factor still looks like how quickly pharmacy distribution reaches scale while keeping patient access smooth.
The biggest operational risk remains execution. Pharmacy buildout, international expansion and supply availability all add complexity at a time when Tandem Diabetes Care faces heavier competition and relies heavily on renewals. The latest news mainly sharpens focus on these execution questions rather than introducing a new fundamental threat.
Without fresh company announcements tied directly to this move, the most relevant context is Tandem Diabetes Care's ongoing focus on higher margin recurring sales from pumps, cartridges and infusion sets. That is where the pharmacy channel push meets the installed base story. Any disruption in that flow would feed quickly into sentiment on the stock.
Analysts already frame pharmacy expansion and international direct sales as major catalysts. The recent re rating simply places more weight on whether management can turn that thesis into cleaner execution, stable inventory and predictable renewals while the firm is still loss making and competing against larger rivals in a fast changing insulin pump market.
Tandem Diabetes Care's current analyst narrative points to revenue of about US$1.4b and earnings of US$63.4 million by 2029, built on assumed yearly revenue growth of 10.3%. That outcome would represent an earnings swing of roughly US$158 million from a loss of US$94.5 million today to the forecast profit level.
Uncover why Tandem Diabetes Care's fair value indicates a 54% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One sharp contrast comes from the bearish view that Tandem Diabetes Care could hit a wall on pharmacy execution. Those analysts were already modeling roughly 9.9% yearly revenue growth and still saw earnings stuck near a loss of about US$63.3 million before the news. That is a far tougher bar, so treat this rebound as a chance to compare very different playbooks.
Explore another Tandem Diabetes Care fair value estimate, including one that suggests it could be worth just $29.20!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tandem Diabetes Care research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tandem Diabetes Care. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tandem Diabetes Care's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tandem Diabetes Care?
If the Tandem Diabetes Care story has sharpened your thinking about recurring revenue and execution risk, it can be useful to test that framework across a wider watchlist using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan a curated set of 29 high quality undervalued stocks that may warrant a closer look on your radar.
- For investors who care most about resilience, focus on 30 resilient stocks with low risk scores that score well on financial strength and business stability checks.
- When balance sheet strength is your priority, filter for companies in the list of solid balance sheet and fundamentals (24 results) and compare how they manage debt, cash and core operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com