
Flowserve (FLS), Why Is Attention Building This Week?
Flowserve (FLS) heads into its Q3 earnings release this Wednesday after the close, with expectations centered on about 5.3% year on year revenue growth and lingering questions around its recently mixed guidance.
At a share price of US$70.84, Flowserve has inched higher over the past week. A 30 day share price return of about 4% in the red hints at some cooling momentum ahead of Q3, yet a 36.1% one year total shareholder return and strong multi year gains suggest longer term holders have been well rewarded.
Scan how Flowserve compares with other industrial stocks being priced for potential breakouts and earnings surprises using our hand picked 29 high quality undervalued stocks list.
Recent holders in Flowserve have already seen strong gains, yet the latest pullback and mixed guidance leave an open question: Is the bigger move already in the rear view mirror, or does the current valuation still offer meaningful upside?
Most Popular Narrative: 20.4% Undervalued
Against Flowserve's last close at $70.84, the most followed narrative anchors on a fair value estimate of $89.00. This frames the current Q3 setup as a test of whether margin and cash flow work are being fully recognised in the price.
The main thing that has to go right is continued execution on operational improvement and aftermarket growth, along with managing Middle East disruptions and integrating the Trillium valves acquisition into a higher-margin mix.
See why 36 investors see Flowserve as 20% undervalued.
Analysts backing this view are using a 9.0% discount rate and a revenue outlook that points to Flowserve reaching $5.6b of sales and $737.9m of earnings by 2029, with profit margins of about 13.2%. To line up with the $89.00 fair value, that path also assumes the stock trades on a P/E of 19.9x on those earnings, which is lower than the current P/E of 25.5x and below the present 23.7x level for the wider US Machinery group.
That gap between the current multiple and the implied future P/E effectively bakes in some multiple compression over time, so the thesis leans more on execution and earnings delivery than on re rating. For readers, the key judgement is whether the combination of margin targets, nuclear and power work, and Middle East recovery outlined in the narrative feels achievable under that 9.0% required return.
Result: Fair Value of $89.00 (UNDERVALUED)
Still, the narrative wobbles if Middle East disruption lingers or if cost and mix actions fall short of the margin and earnings path that analysts outline.
Find out about the key risks to this Flowserve narrative.
Another View: What Flowserve's P/E Signals
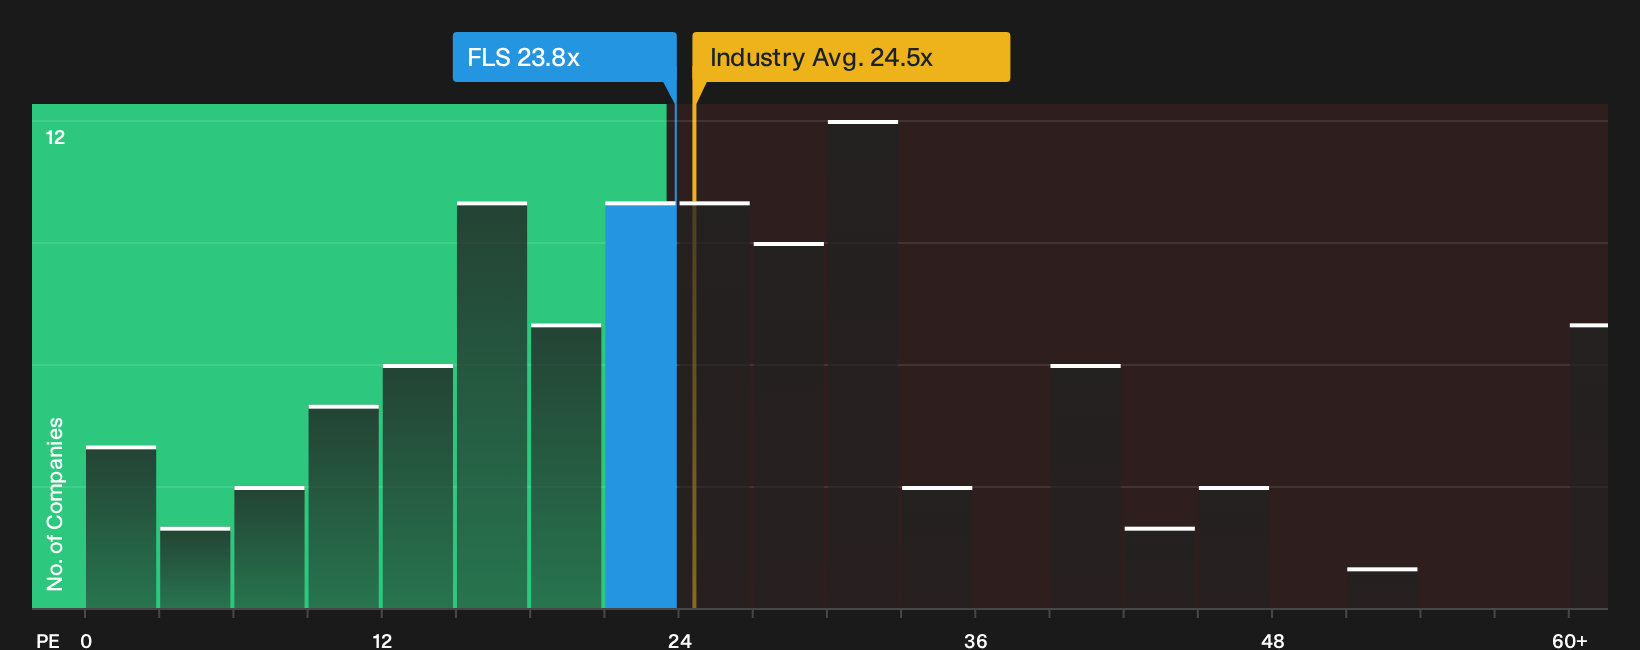
There is a second lens on Flowserve that leans less supportive. On a P/E of 23.8x, the shares trade above peer averages at 21.4x, even though they sit slightly below the wider US Machinery group on 24.4x and under an estimated fair ratio of 31.7x.
That mix of rich pricing versus close peers, cheaper levels than the broader industry, and a fair ratio well above today leaves investors weighing whether current earnings already carry a lot of optimism or whether the market could drift toward that higher fair ratio over time.
For a closer look at how this earnings multiple compares with peers and where valuation risk might sit, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and sentiment can feel confusing, so treat this as a prompt to move quickly, review the data carefully, and form your own stance using the 4 key rewards and 2 important warning signs
Looking for more Flowserve investment ideas?
If Flowserve has your attention today, do not stop at a single ticker. Broaden your watchlist with a few focused idea lists that highlight different angles of opportunity.
- Target resilient upside by reviewing companies flagged in the 21 high quality undiscovered gems before they are widely followed.
- Prioritise strength and staying power by scanning the list of solid balance sheet and fundamentals (24 results) for businesses with sturdier financial foundations.
- Dial down portfolio stress and concentrate on durability by checking the 30 resilient stocks with low risk scores that help reduce nasty surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com