
Australian Stock Market Today: ASX Futures Dip On Oil Supply Strains And CPI Focus
The Morning Bull - Australian Market Morning Update Tuesday, 27 Oct 2026
The Australian sharemarket is pointing slightly lower at the open, with SPI 200 futures down about 0.4%. The main story today is oil supply risk, as investors weigh tighter crude markets against already sensitive inflation expectations.
US Strategic Petroleum Reserve holdings sit at 282.6 million barrels, the lowest since 1982, after a planned release of 172 million barrels and an emergency exchange. Middle East risks and steady OPEC+ output are helping keep oil markets tight.
Higher and stickier energy prices feed directly into transport, manufacturing and household power bills, which can keep headline inflation firm and pressure rate expectations. That mix often squeezes interest rate sensitive areas while supporting cash flow rich resource producers.
The unresolved question is whether this oil driven price pressure lands just as the Fed and the RBA look for evidence that inflation is easing. Upcoming US oil inventory data and the Fed decision could quickly challenge today’s cautious equity tone.
Stocks to Watch Before the Opening Bell
Austal (ASB)
Austal has laid out a mixed FY26 picture, with A$2.03b in revenue but an EBIT loss of A$125.2m and NPAT loss of A$53.6m driven by its US operations. The order book of A$16.5b and A$5b in fresh defence contracts provide long production visibility. Investors will focus on any progress on the potential Austal USA sale to Hanwha.
Ingenia Communities Group (INA)
Ingenia is back in play after receiving a non binding proposal from AVID at up to A$5.40 cash per stapled security. The bid requires due diligence, board and securityholder approval, regulatory sign off and termination of Ingenia’s existing scheme with Peet. Attention now sits on whether AVID moves to a binding offer and how Peet responds.
Amotiv (AOV)
Amotiv has put two levers on the table. The group announced a buyback of up to 6,692,498 shares, or 5% of issued capital, as part of a capital management plan. It also entered a collaboration with Holley Performance Brands to expand automotive products across North America, Australia and New Zealand. The market will watch execution on both the capital return and new product rollout.
Top Movers
- GR Engineering Services (ASX:GNG) jumped 10.94% after a shareholder proposal for activist director election sharpened governance focus.
- SKS Technologies Group (ASX:SKS) climbed 10.11% as traders reacted to reaffirmed FY27 revenue guidance of about A$500m.
- Megaport (ASX:MP1) advanced 9.60% following positive interest in its new AWS Interconnect managed connectivity offering.

Top Losers
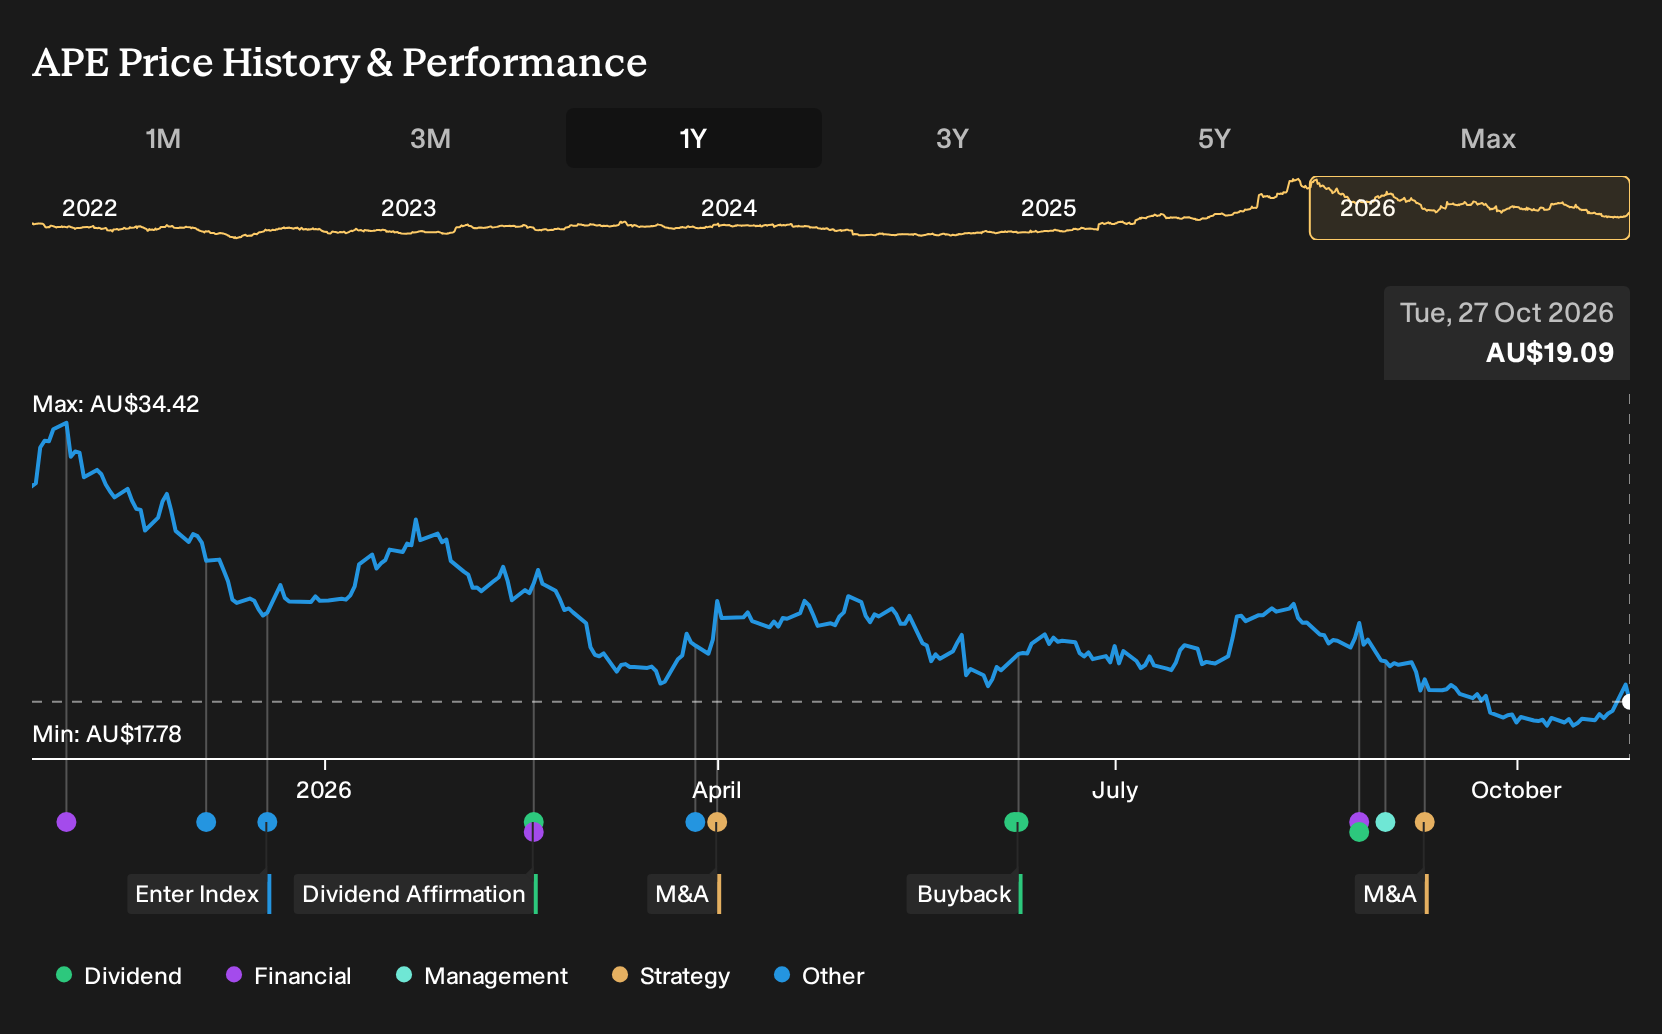
- Eagers Automotive (ASX:APE) fell 4.69% after investors weighed the BYD joint venture acquisition terms and earnings accretion guidance.
- Perseus Mining (ASX:PRU) declined 3.04% as traders squared positions ahead of upcoming quarterly updates and broader commodity data.
- Technology One (ASX:TNE) slipped 2.52% following profit taking after the recent rebound in Australian technology stocks.
On The Radar
For Australian investors, the next few sessions revolve around inflation readings, central bank commentary and a handful of heavyweight bank and resource updates that could sway rate expectations and sector positioning.
- Australia CPI Sep quarter print, Wed 28 Oct, carries a 0.7% consensus for monthly inflation and 4.2% for annual CPI. A softer result would ease pressure on local borrowing costs, while a hotter figure would keep rate expectations pinned high.
- RBA Trimmed Mean CPI, Wed 28 Oct, is forecast at 0.3% month on month and 3.6% year on year. Any move away from 3.6% is likely to influence views on how long the cash rate stays at 4.6%.
- RBA Senate appearance, Wed 28 Oct, gives lawmakers a chance to quiz policymakers on how they read inflation and employment. This can shape expectations for the 3 Nov RBA meeting and the outlook for rate sensitive banks and property trusts.
- US Fed interest rate decision, Wed 28 Oct, is expected to keep the funds rate near 4%. Any shift in tone on future moves would flow quickly into the US dollar and global risk appetite, and in turn the A$/US$ and local exporters.
- Westpac Banking, Mon 2 Nov, reports FY26 final results, where dividend decisions and any commentary on mortgage arrears will matter for how investors think about bank capital returns and household credit stress.
Sector & Industry Watch
Energy and Oil and Gas: Strong year, but taking a breather
Energy and Oil and Gas have eased over the past week even though year to date returns are firmly positive. That pause comes while oil supply risk stays in focus, with the US Strategic Petroleum Reserve at its lowest level since 1982 and local names like Woodside and Ampol active on portfolio moves and project deals.
If you hold fuel producers or petrol exposed stocks, tonight’s US API crude inventory data is the short term driver to watch. A clear build or draw can move global oil prices, which then shows up in bowser costs, sector earnings expectations and the overall mood on ASX energy names.
Materials and Metals and Mining: Miners under pressure despite busy updates
Materials and Metals and Mining have both fallen over the past 7 and 30 days, even with slightly positive 1 year returns. This weaker patch is landing alongside a flood of company news, from lithium studies at Wildcat Resources and Atlantic Lithium to rare earth funding at Astron and Energy Fuels, plus gold and copper moves from Turaco Gold, Brightstar Resources and Sandfire Resources.
If your portfolio leans toward iron ore, gold or battery metals, Wednesday’s Australia CPI and trimmed mean CPI are the main triggers. Those inflation reads feed into interest rate expectations, which help set discount rates for long life mines and appetite to fund the next round of ASX resource projects.
Financials and Banks: Lenders extend their recent rebound
Financials have pushed higher over the past week, with Banks climbing even more on a 7 day view and edging into positive territory year to date. Updates from BSP Financial Group, Omni Bridgeway, Clime Capital and Zip Co show lending, fees and fund management income still supporting parts of the sector despite earlier market volatility.
If you rely on bank dividends or broader Financials for income, focus on Wednesday’s Australia CPI and core inflation print. That release shapes views on future RBA moves, which matter for loan margins, deposit rates and the risk that more households or small businesses fall behind on repayments.
Real Estate: A REITs lift on deal flow and data
Real Estate has firmed over the past week and month, although returns remain weaker over the year to date and 1 year. Corporate activity around Ingenia Communities, court rulings involving DEXUS and trading updates from International Equities and Mustera Property show money still moving through the sector even with higher borrowing costs.
If you own A REITs for yield, Wednesday’s CPI and trimmed mean CPI are the key local checks. Any surprise on underlying inflation can alter how long markets expect 4.6% cash rates to stay in place, which flows directly into refinancing costs and what investors feel comfortable paying for listed property distributions.
Consumer Discretionary and Automobiles: Rate sensitive spending still finding pockets of demand
Consumer Discretionary has edged higher over the past week and month, although the 1 year and year to date picture is still weaker, while Automobiles have also risen on a 7 day and 30 day view. Recent news from Nick Scali, Universal Store, Star Entertainment Group, Eagers Automotive and Amotiv shows households still spending in selected areas like furniture, fashion, casinos and car related products despite higher living costs.
If your holdings include retailers, entertainment stocks or auto related plays, the detail inside Wednesday’s CPI on housing and services is worth close attention. That breakdown helps you judge how much cash is left after essentials, which is what ultimately drives optional purchases across this rate sensitive corner of the market.
Find Tomorrow's Top Performers
With Australia CPI and trimmed mean CPI set to guide how long the 4.6% cash rate stays in place, income focused investors can start with this list of 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com