
Koei Tecmo Holdings (TSE:3635) Lifts Interim Outlook, Is The Valuation Discount Enough?
Koei Tecmo Holdings (TSE:3635) just raised its interim earnings outlook and flagged stronger non operating income, and then scheduled an October 26 board meeting to revisit full year forecasts and the year end dividend plan.
At a share price of ¥1,725.5, Koei Tecmo Holdings has seen a 3.48% 1 day share price return and a 4.64% 90 day share price return, yet the year to date share price return is down 9.42% and the 1 year total shareholder return has declined 12.71%. This suggests that recent momentum has improved, even though longer term holders are still under water.
Spot opportunities beyond Koei Tecmo Holdings by scanning a hand picked set of resilient businesses with improving momentum using our 22 resilient stocks with low risk scores.The rebound in Koei Tecmo Holdings after the guidance upgrade puts you at a crossroads. Do you lean into this reset now, or hold out for a cheaper entry before the next move on valuation?
Preferred P/E of 12x for Koei Tecmo Holdings: Is it justified?
On valuation, the market is currently paying a P/E of 12x for Koei Tecmo Holdings, which is below both peer and industry averages and suggests investors are pricing the stock more cautiously than many entertainment rivals.
The P/E ratio compares the current share price to earnings per share and, for a content focused entertainment group like Koei Tecmo Holdings, it gives a simple shorthand for how much investors are willing to pay for each unit of profit. A lower multiple can reflect muted expectations for future earnings, while a richer ratio often implies investors are comfortable paying up for future growth or resilience.
Here, the picture is mixed. Earnings grew 60% over the past year and have grown 4.3% per year over the past 5 years, and the business is assessed as having high quality earnings. Yet forecasts point to earnings declining by an average of 5.5% per year over the next 3 years and Return on Equity is projected to ease toward 12%, which can help explain why the market is not attaching a premium P/E despite recent profit strength.
Compared to a peer average P/E of 18.4x and a JP Entertainment industry average of 16.8x, the current 12x multiple is materially lower and signals a clear discount. Against an estimated fair P/E of 15.8x, the current level is also below where valuation could gravitate if sentiment shifts, suggesting the market is assigning a meaningful margin of safety to the earnings stream.
Explore the SWS fair ratio for Koei Tecmo Holdings.
Result: Price-to-Earnings of 12x (UNDERVALUED)
Still, the narrative for Koei Tecmo Holdings can break if forecast earnings softness persists, or if key entertainment titles and licensed content underperform expectations.
Find out about the key risks to this Koei Tecmo Holdings narrative.
Another view on Koei Tecmo Holdings using our DCF model
Koei Tecmo Holdings may look inexpensive on a 12x P/E, yet our DCF model points the other way. At ¥1,725.5, the shares are trading above an estimated future cash flow value of ¥1,356.43, which implies the stock screens as overvalued using this method.
This gap matters. A lower DCF value suggests limited protection if earnings forecasts soften or if popular titles do not support current cash generation expectations. It raises a straightforward question for you: is the earnings-based discount enough compensation for that cash flow risk, or not?
Look into how the SWS DCF model arrives at its fair value.
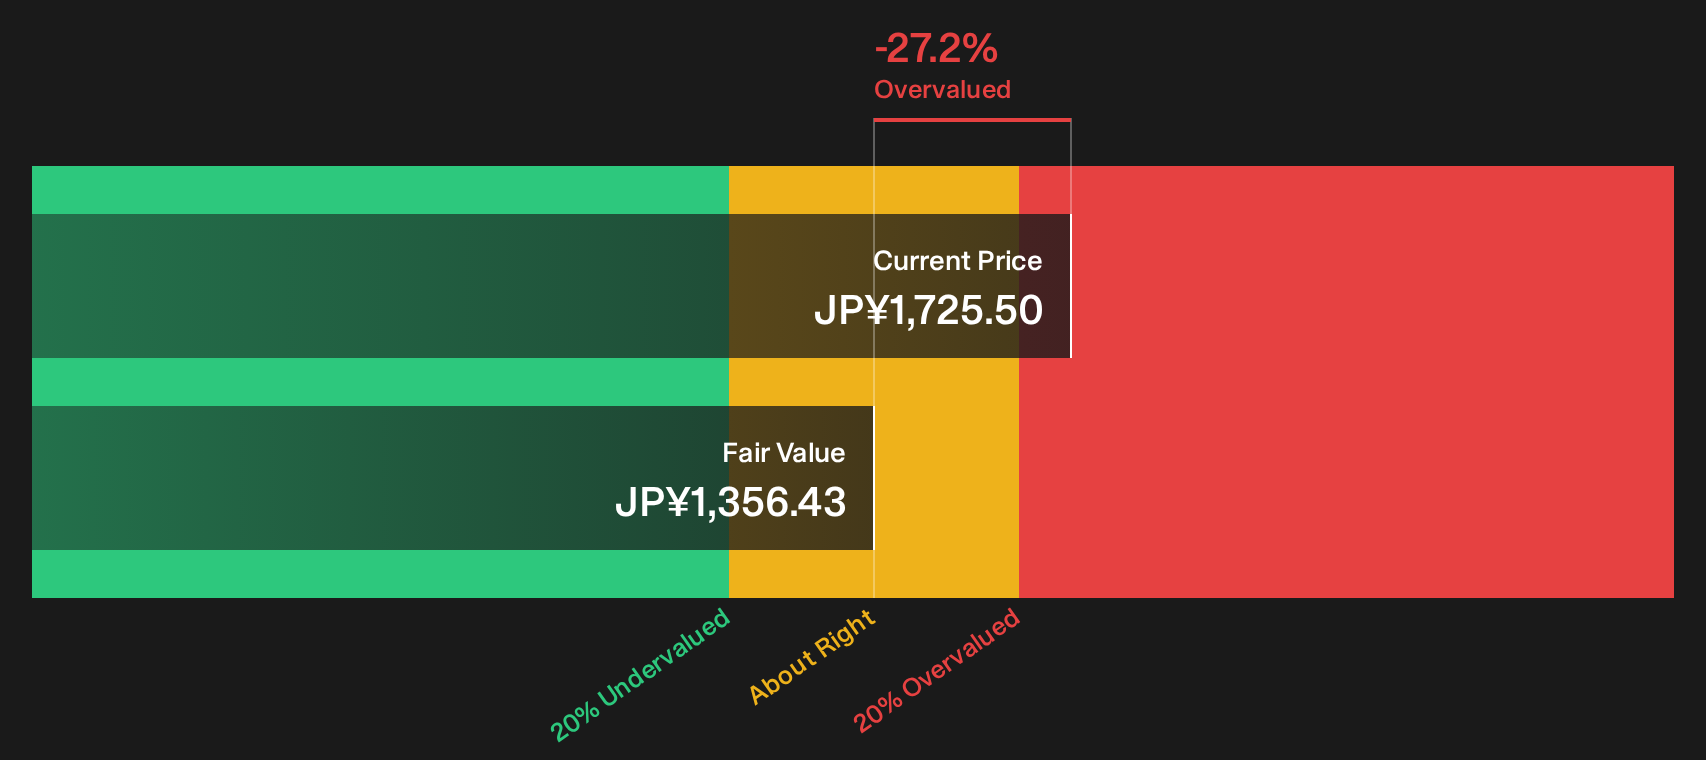
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Koei Tecmo Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Koei Tecmo Holdings can feel uncomfortable, especially when earnings metrics and cash flow values are pulling in different directions. Move quickly, review the numbers yourself, and consider both sides of the story with the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Koei Tecmo Holdings?
If Koei Tecmo Holdings has your attention, do not stop there. Broader opportunity hunting often starts where your first idea leaves off.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive entry points using our 16 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that pair resilience with higher yields through our 29 dividend fortresses.
- Prioritise financial durability by filtering for companies with robust cash positions and prudent leverage using our list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com